HDB Concessionary Loan Rate: Why Is It Still 2.6%?
The HDB loan rate is the CPF OA rate plus 0.1 percentage point: 2.6% a year. How the peg works, what it costs on a S$300,000 loan and what could move it.
The HDB concessionary loan costs 2.6% a year in Q4 2026. It has cost 2.6% in every quarter since Q2 2015.
The rate is a peg: the CPF Ordinary Account (OA) rate plus 0.1 percentage point.
How the peg works
The OA rate is 2.5%. That is the legal minimum, and it has applied in every quarter for years.
Add 0.1 percentage point and you get the HDB rate. CPF confirmed the figure in its news release of 22 September 2026, which covers 1 October to 31 December 2026.
The rate is reviewed every quarter.
| Item | Rate | Period |
|---|---|---|
| CPF OA interest | 2.5% a year (the minimum) | 1 Oct to 31 Dec 2026 |
| Spread added by the peg | 0.1 percentage point | Same in every release read since Q2 2015 |
| HDB concessionary loan | 2.6% a year | 1 Oct to 31 Dec 2026 |
Source: CPF news release of 22 September 2026 (checked 4 October 2026).
Why it has not moved
The OA rate follows a formula based on bank interest rates, but it cannot fall below 2.5%. The formula gave only 0.32% for May to July 2026, according to CPF’s interest page. The floor wins every time.
So the HDB rate is the floor plus the spread. Until the formula climbs above 2.5%, nothing changes.
- 3-month compounded SORA
- HDB concessionary loan rate
- CPF Ordinary Account rate
Latest: SORA 1.36% (13 Nov 2026); HDB loan 2.60% (Q4 2026), unchanged on Q4 2025; CPF OA 2.50% (Q4 2026), unchanged on Q4 2025.
The HDB rate follows the OA rate by formula and has not moved since 2015. A bank loan priced off SORA moves with the line for SORA, plus the bank's spread.
Table view
| Period | 3-month compounded SORA | HDB concessionary loan rate | CPF Ordinary Account rate |
|---|---|---|---|
| Nov 2026 | 1.36% | – | – |
| Oct 2026 | 1.30% | – | – |
| Q4 2026 | – | 2.60% | 2.50% |
| Sep 2026 | 1.23% | – | – |
| Aug 2026 | 1.19% | – | – |
| Jul 2026 | 1.14% | – | – |
| Q3 2026 | – | 2.60% | 2.50% |
| Jun 2026 | 1.08% | – | – |
| May 2026 | 1.06% | – | – |
| Apr 2026 | 1.03% | – | – |
| Q2 2026 | – | 2.60% | 2.50% |
| Mar 2026 | 1.07% | – | – |
| Feb 2026 | 1.12% | – | – |
| Jan 2026 | 1.15% | – | – |
| Q1 2026 | – | 2.60% | 2.50% |
| Dec 2025 | 1.19% | – | – |
| Nov 2025 | 1.25% | – | – |
| Oct 2025 | 1.32% | – | – |
| Q4 2025 | – | 2.60% | 2.50% |
| Sep 2025 | 1.45% | – | – |
| Aug 2025 | 1.56% | – | – |
| Jul 2025 | 1.85% | – | – |
| Q3 2025 | – | 2.60% | 2.50% |
| Jun 2025 | 2.05% | – | – |
| May 2025 | 2.27% | – | – |
| Apr 2025 | 2.36% | – | – |
| Q2 2025 | – | 2.60% | 2.50% |
| Mar 2025 | 2.55% | – | – |
| Feb 2025 | 2.73% | – | – |
| Jan 2025 | 2.90% | – | – |
| Q1 2025 | – | 2.60% | 2.50% |
| Dec 2024 | 3.03% | – | – |
| Nov 2024 | 3.21% | – | – |
| Oct 2024 | 3.38% | – | – |
| Q4 2024 | – | 2.60% | 2.50% |
| Sep 2024 | 3.49% | – | – |
| Aug 2024 | 3.57% | – | – |
| Jul 2024 | 3.64% | – | – |
| Q3 2024 | – | 2.60% | 2.50% |
| Jun 2024 | 3.63% | – | – |
| May 2024 | 3.66% | – | – |
| Apr 2024 | 3.65% | – | – |
| Q2 2024 | – | 2.60% | 2.50% |
| Mar 2024 | 3.68% | – | – |
| Feb 2024 | 3.65% | – | – |
| Jan 2024 | 3.65% | – | – |
| Q1 2024 | – | 2.60% | 2.50% |
| Dec 2023 | 3.70% | – | – |
| Nov 2023 | 3.75% | – | – |
| Oct 2023 | 3.75% | – | – |
| Q4 2023 | – | 2.60% | 2.50% |
| Sep 2023 | 3.70% | – | – |
| Aug 2023 | 3.70% | – | – |
| Jul 2023 | 3.67% | – | – |
| Q3 2023 | – | 2.60% | 2.50% |
| Jun 2023 | 3.65% | – | – |
| May 2023 | 3.62% | – | – |
| Apr 2023 | 3.61% | – | – |
| Q2 2023 | – | 2.60% | 2.50% |
| Mar 2023 | 3.58% | – | – |
| Feb 2023 | 3.22% | – | – |
| Jan 2023 | 3.14% | – | – |
| Q1 2023 | – | 2.60% | 2.50% |
| Dec 2022 | 3.03% | – | – |
| Nov 2022 | 2.92% | – | – |
| Oct 2022 | 2.46% | – | – |
| Q4 2022 | – | 2.60% | 2.50% |
| Sep 2022 | 2.07% | – | – |
| Aug 2022 | 1.60% | – | – |
| Jul 2022 | 1.27% | – | – |
| Q3 2022 | – | 2.60% | 2.50% |
| Jun 2022 | 0.77% | – | – |
| May 2022 | 0.53% | – | – |
| Apr 2022 | 0.32% | – | – |
| Q2 2022 | – | 2.60% | 2.50% |
| Mar 2022 | 0.28% | – | – |
| Feb 2022 | 0.25% | – | – |
| Jan 2022 | 0.21% | – | – |
| Q1 2022 | – | 2.60% | 2.50% |
| Dec 2021 | 0.19% | – | – |
| Nov 2021 | 0.16% | – | – |
| Oct 2021 | 0.16% | – | – |
| Q4 2021 | – | 2.60% | 2.50% |
| Sep 2021 | 0.13% | – | – |
| Aug 2021 | 0.13% | – | – |
| Jul 2021 | 0.13% | – | – |
| Q3 2021 | – | 2.60% | 2.50% |
| Jun 2021 | 0.13% | – | – |
| May 2021 | 0.17% | – | – |
| Apr 2021 | 0.19% | – | – |
| Q2 2021 | – | 2.60% | 2.50% |
| Mar 2021 | 0.22% | – | – |
| Feb 2021 | 0.20% | – | – |
| Jan 2021 | 0.17% | – | – |
| Q1 2021 | – | 2.60% | 2.50% |
| Dec 2020 | 0.17% | – | – |
| Nov 2020 | 0.12% | – | – |
| Oct 2020 | 0.12% | – | – |
| Q4 2020 | – | 2.60% | 2.50% |
| Sep 2020 | 0.10% | – | – |
| Aug 2020 | 0.10% | – | – |
| Jul 2020 | 0.08% | – | – |
| Q3 2020 | – | 2.60% | 2.50% |
| Jun 2020 | 0.14% | – | – |
| May 2020 | 0.27% | – | – |
| Apr 2020 | 0.53% | – | – |
| Q2 2020 | – | 2.60% | 2.50% |
| Mar 2020 | 0.88% | – | – |
| Feb 2020 | 1.14% | – | – |
| Jan 2020 | 1.20% | – | – |
| Q1 2020 | – | 2.60% | 2.50% |
| Dec 2019 | 1.26% | – | – |
| Nov 2019 | 1.31% | – | – |
| Oct 2019 | 1.46% | – | – |
| Q4 2019 | – | 2.60% | 2.50% |
| Sep 2019 | 1.53% | – | – |
| Aug 2019 | 1.59% | – | – |
| Jul 2019 | 1.67% | – | – |
| Q3 2019 | – | 2.60% | 2.50% |
| Jun 2019 | 1.72% | – | – |
| May 2019 | 1.68% | – | – |
| Apr 2019 | 1.62% | – | – |
| Q2 2019 | – | 2.60% | 2.50% |
| Mar 2019 | 1.54% | – | – |
| Feb 2019 | 1.59% | – | – |
| Jan 2019 | 1.55% | – | – |
| Q1 2019 | – | 2.60% | 2.50% |
Source: MAS, CPF Board. Data to 13 Nov 2026.
The chart shows the contrast. Market rates, here 3-month SORA, rise and fall.
The HDB loan line stays flat. A flat line is a feature if you value a rate you can plan around. It is a cost if bank rates sit below it.
What 2.6% costs on a real loan
Take a round loan of S$300,000 over 25 years. It uses the standard instalment formula with monthly compounding.
| Annual rate | Monthly instalment | Total interest over 25 years |
|---|---|---|
| 1.6% | S$1,214 | S$64,187 |
| 2.6% (HDB loan) | S$1,361 | S$108,303 |
| 3.6% | S$1,518 | S$155,402 |
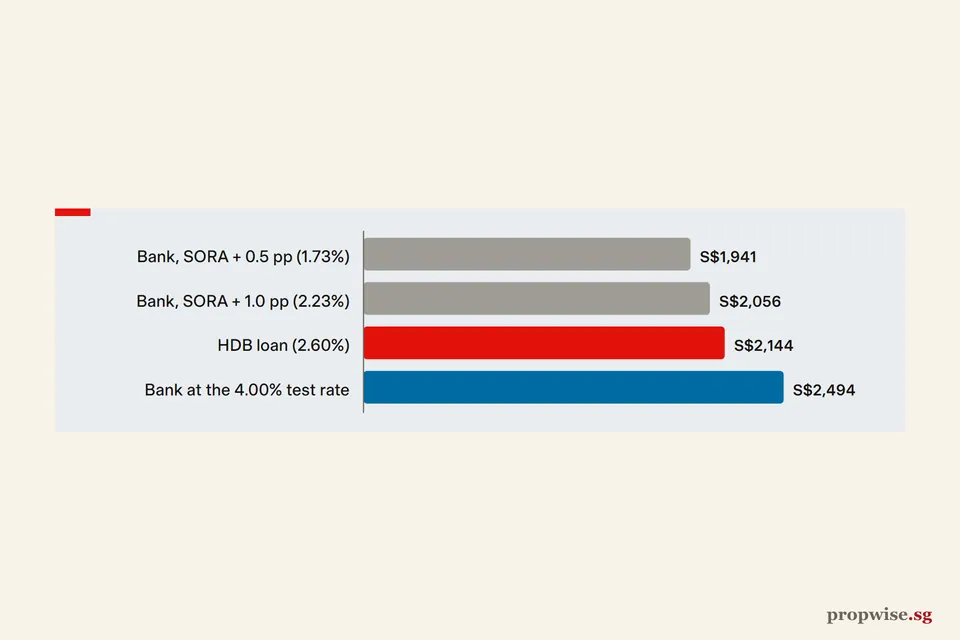
Each percentage point moves the monthly bill by about S$150 on this loan. A flat 2.6% means you know the figure for the whole of a quarter and, so far, for every quarter since 2015.
The table is a sense of scale, nothing more. A real loan depends on the loan size, the tenure and the date you take it. Our HDB loan versus bank loan comparison sets the two side by side for the median flat.
What would change the rate
Two things could do it.
The first is a change in the OA rate itself. CPF would announce it before the quarter starts, as it did on 22 September 2026 for the current quarter. The HDB rate would follow by the same 0.1 percentage point.
The second is a change in the spread. The peg has stayed at 0.1 percentage point in every release we read from Q2 2015 to Q4 2026.
Watch the CPF news releases around the end of each quarter. They give the next quarter’s rates. If you hold an HDB loan, the rate on your statement follows the same number.
Where to see the history
Every version of this rule, with its source, is on the rules page. The rate for each quarter is on the chart above.