Mortgage Calculator: S$800K Loan Needs S$7,700 Monthly Income
A walkthrough of the Propwise mortgage calculator on one S$800,000 loan: the monthly instalment, the 4% stress test and the 55% TDSR check, step by step.
A S$800,000 bank loan over 25 years at 3.0% costs S$3,794 a month. The bank tests you at 4.0%, which is S$4,223 a month, and that figure must fit within 55% of your gross income. With no other debts, that means about S$7,700 a month.
This walkthrough follows one loan through the Propwise mortgage calculator, step by step.
Step 1: the instalment
Enter the loan amount, the tenure and the interest rate. The calculator gives the monthly instalment that clears the loan by the last month.
For S$800,000 over 25 years, the instalment depends on the rate. Today the 3-month compounded SORA, the benchmark many floating-rate home loans follow, is 1.35% as at 11 Nov 2026. Banks add a margin on top. Use the rate on your own offer letter. We use 3.0% here as an example.
- 3-month compounded SORA (Singapore)
- US federal funds rate (effective)
Latest: SORA 1.35% (11 Nov 2026); Fed 3.88% (9 Nov 2026), unchanged on 9 Nov 2025.
SORA is the benchmark for floating-rate home loans in Singapore. The US rate is shown for context: it moves SORA only indirectly, through the Singapore dollar and bank funding costs.
Table view
| Period | 3-month compounded SORA (Singapore) | US federal funds rate (effective) |
|---|---|---|
| Nov 2026 | 1.35% | 3.88% |
| Oct 2026 | 1.30% | 3.88% |
| Sep 2026 | 1.23% | 3.88% |
| Aug 2026 | 1.18% | 3.63% |
| Jul 2026 | 1.14% | 3.63% |
| Jun 2026 | 1.08% | 3.63% |
| May 2026 | 1.06% | 3.62% |
| Apr 2026 | 1.03% | 3.64% |
| Mar 2026 | 1.07% | 3.64% |
| Feb 2026 | 1.12% | 3.64% |
| Jan 2026 | 1.15% | 3.64% |
| Dec 2025 | 1.19% | 3.64% |
| Nov 2025 | 1.25% | 3.89% |
| Oct 2025 | 1.32% | 4.11% |
| Sep 2025 | 1.46% | 4.09% |
| Aug 2025 | 1.56% | 4.33% |
| Jul 2025 | 1.86% | 4.33% |
| Jun 2025 | 2.06% | 4.33% |
| May 2025 | 2.27% | 4.33% |
| Apr 2025 | 2.40% | 4.33% |
| Mar 2025 | 2.55% | 4.33% |
| Feb 2025 | 2.73% | 4.33% |
| Jan 2025 | 2.90% | 4.33% |
| Dec 2024 | 3.08% | 4.33% |
| Nov 2024 | 3.21% | 4.58% |
| Oct 2024 | 3.39% | 4.83% |
| Sep 2024 | 3.49% | 4.83% |
| Aug 2024 | 3.57% | 5.33% |
| Jul 2024 | 3.64% | 5.33% |
| Jun 2024 | 3.63% | 5.33% |
| May 2024 | 3.66% | 5.33% |
| Apr 2024 | 3.65% | 5.33% |
| Mar 2024 | 3.68% | 5.33% |
| Feb 2024 | 3.64% | 5.33% |
| Jan 2024 | 3.66% | 5.33% |
| Dec 2023 | 3.70% | 5.33% |
| Nov 2023 | 3.75% | 5.33% |
| Oct 2023 | 3.75% | 5.33% |
| Sep 2023 | 3.70% | 5.33% |
| Aug 2023 | 3.70% | 5.33% |
| Jul 2023 | 3.68% | 5.33% |
| Jun 2023 | 3.65% | 5.07% |
| May 2023 | 3.61% | 5.08% |
| Apr 2023 | 3.61% | 4.83% |
| Mar 2023 | 3.58% | 4.83% |
| Feb 2023 | 3.23% | 4.58% |
| Jan 2023 | 3.12% | 4.33% |
| Dec 2022 | 3.03% | 4.33% |
| Nov 2022 | 2.87% | 3.83% |
| Oct 2022 | 2.45% | 3.08% |
| Sep 2022 | 2.07% | 3.08% |
| Aug 2022 | 1.55% | 2.33% |
| Jul 2022 | 1.27% | 2.32% |
| Jun 2022 | 0.72% | 1.58% |
| May 2022 | 0.52% | 0.83% |
| Apr 2022 | 0.32% | 0.33% |
| Mar 2022 | 0.27% | 0.33% |
| Feb 2022 | 0.25% | 0.08% |
| Jan 2022 | 0.20% | 0.08% |
| Dec 2021 | 0.19% | 0.08% |
| Nov 2021 | 0.16% | 0.08% |
| Oct 2021 | 0.16% | 0.07% |
| Sep 2021 | 0.13% | 0.08% |
| Aug 2021 | 0.13% | 0.08% |
| Jul 2021 | 0.13% | 0.10% |
| Jun 2021 | 0.14% | 0.10% |
| May 2021 | 0.17% | 0.05% |
| Apr 2021 | 0.19% | 0.07% |
| Mar 2021 | 0.23% | 0.07% |
| Feb 2021 | 0.20% | 0.07% |
| Jan 2021 | 0.17% | 0.07% |
| Dec 2020 | 0.17% | 0.09% |
| Nov 2020 | 0.12% | 0.08% |
| Oct 2020 | 0.12% | 0.09% |
| Sep 2020 | 0.10% | 0.09% |
| Aug 2020 | 0.10% | 0.09% |
| Jul 2020 | 0.08% | 0.09% |
| Jun 2020 | 0.14% | 0.08% |
| May 2020 | 0.27% | 0.05% |
| Apr 2020 | 0.53% | 0.05% |
| Mar 2020 | 0.90% | 0.10% |
| Feb 2020 | 1.14% | 1.58% |
| Jan 2020 | 1.20% | 1.55% |
| Dec 2019 | 1.27% | 1.55% |
| Nov 2019 | 1.31% | 1.55% |
| Oct 2019 | 1.46% | 1.83% |
| Sep 2019 | 1.53% | 1.83% |
| Aug 2019 | 1.59% | 2.12% |
| Jul 2019 | 1.67% | 2.40% |
| Jun 2019 | 1.72% | 2.40% |
| May 2019 | 1.68% | 2.38% |
| Apr 2019 | 1.62% | 2.44% |
| Mar 2019 | 1.54% | 2.43% |
| Feb 2019 | 1.59% | 2.40% |
| Jan 2019 | 1.52% | 2.40% |
Source: MAS, FRED. Data to 11 Nov 2026.
The chart shows how far SORA has moved since 2019. A loan that tracks it moves with it, so today’s instalment is a starting point.
Step 2: the stress test
MAS makes banks test your loan at a higher rate. The floor for a home loan is 4.0%. If your loan could reach a higher rate over its life, the bank uses that rate. This applies to an Option to Purchase on or after 30 September 2022.
At 4.0%, the same S$800,000 over 25 years comes to S$4,223 a month. That is S$429 more than the S$3,794 you would pay at 3.0%. You still pay the lower figure. The higher one is the bank’s test.
Step 3: the TDSR check
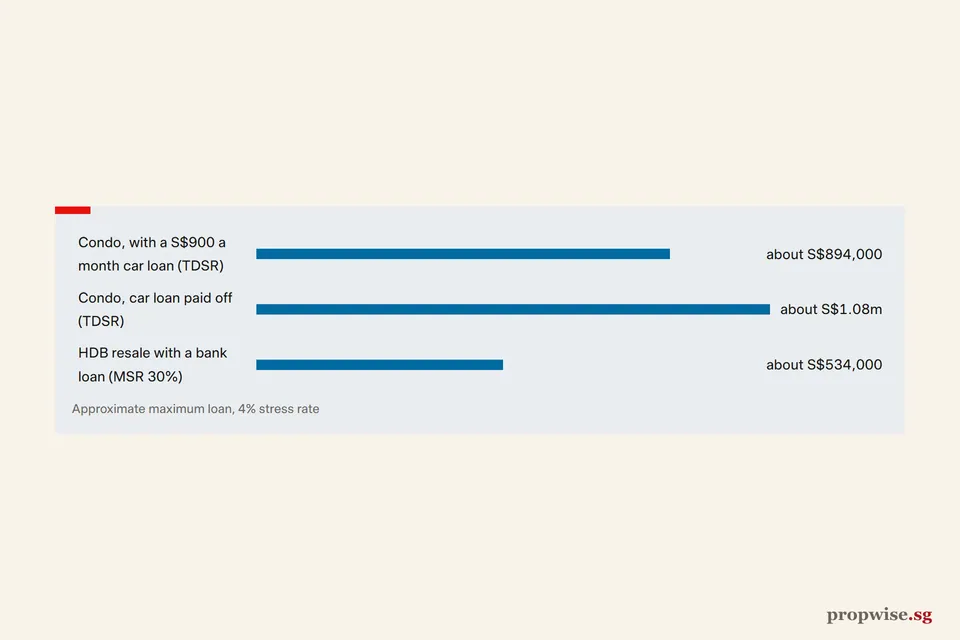
The Total Debt Servicing Ratio (TDSR) caps all your monthly debt repayments at 55% of gross monthly income. This applies to an Option to Purchase on or after 16 December 2021. The bank uses the stress-test instalment in the sum.
Divide S$4,223 by 0.55 and you get about S$7,700. Any other debt goes into the same 55%. A car loan of S$600 a month lifts the income needed to about S$8,770.
| Loan | At 3.0% (what you pay) | At 4.0% (what the bank tests) | Income needed at 55% TDSR |
|---|---|---|---|
| 25 years | S$3,794 | S$4,223 | S$7,700 |
| 30 years | S$3,373 | S$3,819 | S$6,950 |
Source: MAS (TDSR and stress rate); instalments worked out for an example loan (October 2026).
The table shows the trade in tenure. A 30-year loan lowers the stress-test instalment to S$3,819 and the income needed to about S$6,950. MAS allows bank loans for private homes of up to 35 years. A tenure above 30 years cuts the loan-to-value limit for a first loan from 75% to 55%. So does a loan that runs past the borrower’s age of 65. A longer loan also means more interest paid in total.
Step 4: for an HDB flat, add the MSR
A bank loan for an HDB flat has a second test. The Mortgage Servicing Ratio (MSR) limits the instalment alone to 30% of gross monthly income, on top of TDSR. The calculator shows both ratios side by side, so a flat buyer sees the tighter one.
What to try next
Change one input at a time. Add a car loan, move the tenure from 25 to 30 years, or raise the rate by one percentage point. The income line moves each time, and it shows which input matters most for your own loan.
For the full rules, including income haircuts and which debts count, see our guide to TDSR and MSR.