How Much Can You Borrow? TDSR 55%, MSR 30%, LTV 75% (2026)
How much you can borrow for a Singapore home: TDSR 55%, MSR 30%, LTV 75%, the 4% stress test, worked examples and how to qualify.
The Total Debt Servicing Ratio (TDSR) caps all your debt payments at 55% of gross income. The Mortgage Servicing Ratio (MSR) caps an HDB flat or new EC loan at 30%. The loan-to-value (LTV) limit caps a first bank loan at 75% of the price, and the smallest limit wins (MAS).
What are the borrowing limits in 2026?
Two limits work on your income. Banks test both at a stress rate well above what most borrowers pay.
| Limit | What it caps | Level | Rate the lender tests at |
|---|---|---|---|
| TDSR | All monthly debt payments, including the new loan | 55% of gross monthly income | At least 4% |
| MSR, bank loan | Home-loan payments on an HDB flat or a new EC | 30% of gross monthly income | At least 4% |
| MSR, HDB loan | The HDB loan payment | 30% of gross monthly income | At least 3% |
Source: MAS, HDB. Rules in force on 31 October 2026.
Three more limits work on the price. The LTV limit depends on how many housing loans you already have.
| Your situation | Largest bank loan (LTV) | Minimum cash down payment |
|---|---|---|
| No other housing loan | 75% of price or valuation | 5% |
| No other loan, long tenure or past age 65 | 55% | 10% |
| One other housing loan | 45% (25% if long) | 25% |
| Two or more other loans | 35% (15% if long) | 25% |
| HDB loan | 75% | None (CPF can pay it all) |
Source: MAS, HDB. Rules in force on 31 October 2026.
“Long” means a tenure over 30 years (25 years for an HDB flat), or a loan that runs past age 65. The longest tenures are 35 years for a private home and 30 for an HDB flat on a bank loan.
HDB loans run up to 25 years, as MAS and HDB set out. Each rule’s history is on our rules page: TDSR, MSR, LTV, minimum cash and the stress rate.
Why does the 4% stress test shrink your loan?
Banks size your loan at the higher of the actual rate or a medium-term rate of 4% for homes. HDB uses 3%, or its loan rate if that is higher. The floor has stood at 4% since 30 September 2022.
Three-month SORA, the benchmark for most floating-rate loans, was 1.36% on 13 Nov 2026. Banks add their own spread on top. Even so, the payment the bank tests is well above the one you will pay.
Latest: SORA 1.36% (13 Nov 2026).
SORA is the benchmark for floating-rate home loans in Singapore. Your bank adds its own spread.
Table view
| Period | 3-month compounded SORA |
|---|---|
| Nov 2026 | 1.36% |
| Oct 2026 | 1.30% |
| Sep 2026 | 1.23% |
| Aug 2026 | 1.18% |
| Jul 2026 | 1.14% |
| Jun 2026 | 1.08% |
| May 2026 | 1.06% |
| Apr 2026 | 1.03% |
| Mar 2026 | 1.07% |
| Feb 2026 | 1.12% |
| Jan 2026 | 1.15% |
| Dec 2025 | 1.19% |
| Nov 2025 | 1.25% |
| Oct 2025 | 1.32% |
| Sep 2025 | 1.46% |
| Aug 2025 | 1.56% |
| Jul 2025 | 1.86% |
| Jun 2025 | 2.06% |
| May 2025 | 2.27% |
| Apr 2025 | 2.40% |
| Mar 2025 | 2.55% |
| Feb 2025 | 2.73% |
| Jan 2025 | 2.90% |
| Dec 2024 | 3.08% |
| Nov 2024 | 3.21% |
| Oct 2024 | 3.39% |
| Sep 2024 | 3.49% |
| Aug 2024 | 3.57% |
| Jul 2024 | 3.64% |
| Jun 2024 | 3.63% |
| May 2024 | 3.66% |
| Apr 2024 | 3.65% |
| Mar 2024 | 3.68% |
| Feb 2024 | 3.64% |
| Jan 2024 | 3.66% |
| Dec 2023 | 3.70% |
| Nov 2023 | 3.75% |
| Oct 2023 | 3.75% |
| Sep 2023 | 3.70% |
| Aug 2023 | 3.70% |
| Jul 2023 | 3.68% |
| Jun 2023 | 3.65% |
| May 2023 | 3.61% |
| Apr 2023 | 3.61% |
| Mar 2023 | 3.58% |
| Feb 2023 | 3.23% |
| Jan 2023 | 3.12% |
Source: MAS. Data to 13 Nov 2026.
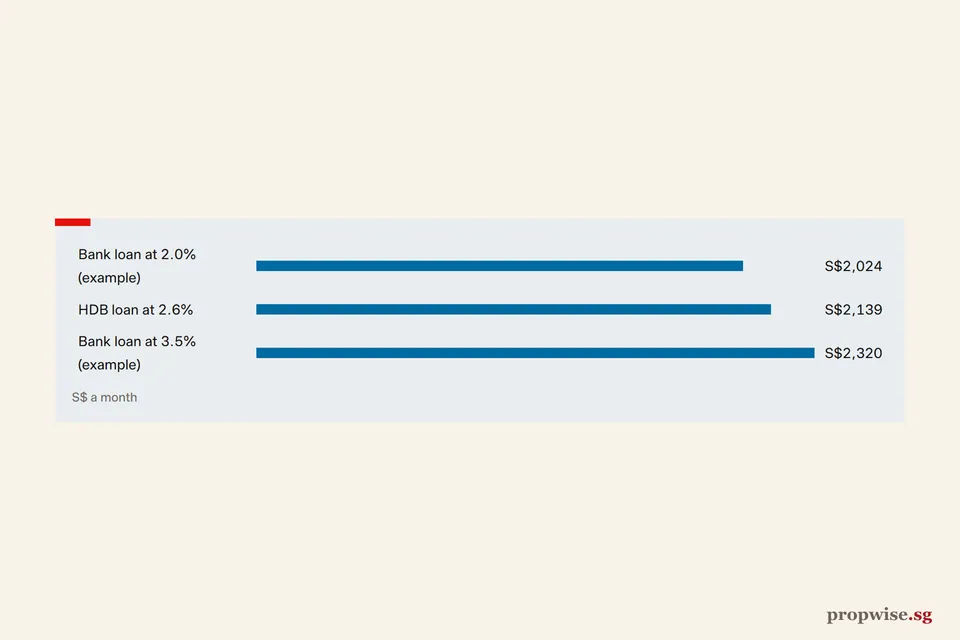
Take a S$900,000 loan over 30 years: at 1.8% the payment is about S$3,237 a month. At the 4% stress rate it is about S$4,297, and that is the figure the bank checks against your income. The test is a raincoat the bank makes you buy on a sunny day.
How much can you borrow on your income?
Say you are 35 and buying a condo alone. Your fixed salary is S$8,000 a month, your bonus averages S$2,000 a month, and you pay S$900 a month on a car loan.
| Step | Calculation | Result |
|---|---|---|
| Income counted | S$8,000 + 70% × S$2,000 | S$9,400 |
| TDSR limit | 55% × S$9,400 | S$5,170 |
| Less car loan | S$5,170 − S$900 | S$4,270 for the mortgage |
| Largest loan | S$4,270 a month at 4% over 30 years | about S$894,000 |
Source: MAS. Rules in force on 31 October 2026.
Pay off the car loan first and the whole S$5,170 goes to the mortgage. The largest loan rises to about S$1.08m. Clearing S$900 a month of car loan adds about S$189,000 to what you can borrow.
Now buy an HDB resale flat with a bank loan instead, where MSR caps the payment at 30% × S$9,400 = S$2,820 a month. At 4% over 25 years, that supports about S$534,000, car loan or not. TDSR still applies too, so the bank uses the lower of the two.
Approximate maximum loan, 4% stress rate
Source: MAS Notice 645 (TDSR) and MSR rules (October 2026). Condo loans use TDSR over 30 years; the HDB bank-loan case uses MSR over 25 years. The lowest of TDSR, MSR and LTV applies.
The chart puts the three cases side by side. The car loan costs the condo buyer S$189,000 of borrowing power. It costs the HDB buyer nothing here, because the tighter 30% MSR limit binds first.
How much cash do you need on top of the loan?
The LTV limit decides your down payment. On a S$1.5m condo, a first bank loan can be up to 75%, or S$1,125,000.
You pay at least 25%, or S$375,000, of which at least 5% (S$75,000) must be cash. The rest can come from CPF.
Now apply the income limit. The buyer above, with the car loan paid off, can borrow only about S$1.08m under TDSR. That is less than the LTV limit, so TDSR wins and the down payment grows to about S$417,000.
Down payment (price less maximum loan)
Source: MAS, loan tenure and LTV limits (27 March 2024 (page update date)). Minimum cash within the down payment: S$75,000 (first loan), S$150,000 (reduced LTV), S$375,000 (second loan). Stamp duties are extra: BSD S$44,600, and ABSD S$300,000 for a second home.
A second housing loan changes the picture. LTV falls to 45% and the cash minimum rises to 25%. Stamp duty comes on top: on a S$1.5m second home, BSD and ABSD add S$344,600, as our ABSD guide shows.
How do banks count your income?
Banks use gross monthly income, without employer CPF. MAS Notice 645 sets the minimum haircuts, and a bank may apply stricter ones.
| Income or asset | How much counts |
|---|---|
| Fixed salary | 100% |
| Variable income (bonus, commission, allowances) | Up to 70% |
| Rental income | Up to 70%, with a stamped tenancy and at least 6 months left |
| Cash and deposits pledged to the bank for 4 years | 100% of the value, spread over 48 months |
| Other financial assets pledged for 4 years | 70% of the value, spread over 48 months |
| Any financial asset not pledged | 30% of the value, spread over 48 months |
Source: MAS.
Savings make a large difference for retirees and the self-employed. S$500,000 in unpledged savings counts as 30% × S$500,000 ÷ 48, or about S$3,125 a month. Pledge the same sum in cash for four years and it counts as about S$10,417 a month.
Does your age change how much you can borrow?
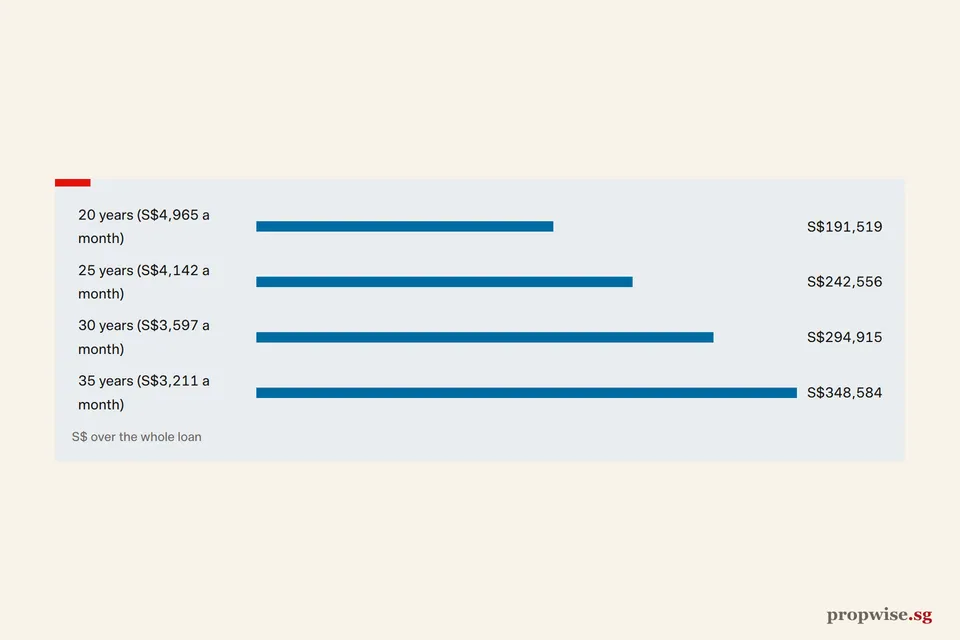
Yes. Banks set the tenure from the income-weighted average age of the borrowers. A shorter tenure means a higher monthly payment, and so a smaller loan under TDSR.
A borrower aged 54 who earns S$10,000 a month has S$5,500 for debts under TDSR. Over 30 years at 4%, that supports about S$1.15m. A loan that ends at age 65 runs only 11 years and supports about S$587,000.
Approximate maximum loan at 4%
Source: MAS Notice 645 (TDSR) (October 2026).
A younger, working co-borrower raises both the income and the tenure. Every borrower must also own the property, under MAS Notice 632. If someone guarantees your loan because you fail TDSR alone, MAS requires the bank to make that person a co-borrower.
When does TDSR not apply?
MAS exempts some loans from TDSR:
- Refinancing a home you live in. Owner-occupiers can switch banks even if their income has fallen.
- Refinancing an investment property, if you commit to reduce the loan by at least 3% within three years, or meet the other MAS conditions. Our refinancing guide explains the options.
- Bridging loans repaid within six months.
- Equity loans where all borrowing secured on the property is 50% or less of its market value.
HDB sizes its own loans. Instalments can be up to 30% of income, tested at 3%. Family income must be within S$16,000 a month for applications from 24 August 2026, according to HDB.
How can you borrow more?
- Clear other debts first. A car loan has the largest effect, because its payment is large and fixed.
- Cancel unused credit lines. With no monthly payment on record, a bank can count interest on the whole credit limit.
- Keep proof of variable income. Banks count only 70% of it, and only what 12 months of payslips or your Notice of Assessment shows.
- Pledge savings if you need more income. Unpledged savings count at 30%; cash pledged for four years counts in full.
- Get an In-Principle Approval before you pay an option fee. For an HDB loan, get an HDB Flat Eligibility letter, valid for nine months.
TDSR is a ceiling, and a ceiling makes a poor target. Our 3/3/5 affordability guide suggests keeping the mortgage under a third of income.
Where to go next
Run your own numbers in our mortgage calculator. Read how the LTV limit works in detail, compare an HDB loan with a bank loan, and see why mortgage applications fail.
Rules and rates as at 31 October 2026.
1 reader comment
Wendy
Hi, how does this TDSR affect the chance for a car loan, given that one is currently on a home loan?