CPF SA, MediSave and RA Interest Rate: 4% Floor Runs to 2027
The CPF Special, MediSave and Retirement Accounts pay 4% a year, and the floor now runs to 31 Dec 2027. What the rule says and why home owners watch it.
The CPF Special, MediSave and Retirement Accounts (SMRA) pay 4% a year for 1 October to 31 December 2026. The Government has extended the 4% minimum for another year, to 31 December 2027, in CPF’s release of 22 September 2026.
These accounts are for retirement and healthcare. Home loans and purchases draw on the Ordinary Account (OA).
The rule today
| Item | Rule |
|---|---|
| Rate, 1 Oct to 31 Dec 2026 | 4% a year on the Special, MediSave and Retirement Accounts |
| How the rate is set | 12-month average yield of 10-year Singapore Government Securities (10YSGS) plus 1%, with a 4% floor |
| Latest result of the formula | 3.06% (Aug 2025 to Jul 2026) |
| Floor | Extended to 31 Dec 2027 |
Source: CPF news release, 22 September 2026 and CPF’s interest page, updated 15 September 2026.
The formula gives 3.06%. That is 0.94 percentage point below the floor (4.00% minus 3.06%). So the floor sets the rate.
CPF says the extension gives members “certainty on their CPF returns” in an uncertain interest-rate environment. A floor works like the ground floor of a lift: the rate can go up from here, but not down.
What the accounts are for
CPF’s account overview describes the roles:
- Special Account (SA): retirement savings.
- MediSave Account (MA): medical expenses such as hospitalisation, and insurance premiums.
- Retirement Account (RA): created at age 55, when the SA closes. It pays lifelong monthly payouts under CPF LIFE.
- Ordinary Account (OA): used mainly for housing.
CPF’s page on using CPF for a home (updated 6 July 2026) lists the OA for the purchase and the downpayment. It also lists the OA for the housing loan, and for stamp and legal fees.
It does not list the SA or MA. So the 4% does not apply to money you spend on a home.
How the rate has moved
| Period | SA and MA | RA |
|---|---|---|
| Q1 2008 to Q2 2023 | 4.00% | 4.00% |
| Q3 2023 | 4.01% | 4.00% |
| Q4 2023 | 4.04% | 4.00% |
| Q1 2024 | 4.08% | 4.08% |
| Q2 2024 | 4.05% | 4.05% |
| Q3 2024 | 4.08% | 4.08% |
| Q4 2024 | 4.14% | 4.14% |
| Q1 2025 to Q4 2026 | 4.00% | 4.00% |
Source: CPF’s historical interest table and quarterly releases, checked on 4 October 2026. The Q4 2023 and Q4 2024 rows match CPF’s releases for those quarters (Q4 2023, Q4 2024).
The rate sat at the floor for more than 15 years. It rose slightly above it from Q3 2023. It peaked at 4.14% in Q4 2024, the highest in the table, and has been back at 4.00% since Q1 2025.
CPF’s table shows that the RA earned the SA and MA rate from Q1 2024.
A worked example
Take S$10,000 held for one year. This is a round number, not a recommendation. It ignores monthly calculation, compounding and extra interest.
- At 4%: S$10,000 × 4% = S$400.
- At the formula result of 3.06%: S$10,000 × 3.06% = S$306. The floor is worth S$94 on this balance.
- In the OA at 2.5% (Q4 2026): S$10,000 × 2.5% = S$250.
Source: CPF Board news release, 22 Sep 2026. The S$ amounts are simplified: CPF works interest out monthly and credits it yearly.
Why a home owner reads this next to the OA rate
The OA pays 2.5%. The HDB concessionary loan costs 2.6% for Q4 2026.
The SMRA rate is 1.5 percentage points above the OA rate. Our companion article on the OA rate explains the OA side.
- 3-month compounded SORA
- HDB concessionary loan rate
- CPF Ordinary Account rate
Latest: SORA 1.24% (15 Oct 2026); HDB loan 2.60% (Q4 2026); CPF OA 2.50% (Q4 2026).
The HDB rate follows the OA rate by formula and has not moved since 2015. A bank loan priced off SORA moves with the line for SORA, plus the bank's spread.
Table view
| Period | 3-month compounded SORA | HDB concessionary loan rate | CPF Ordinary Account rate |
|---|---|---|---|
| Oct 2026 | 1.24% | – | – |
| Q4 2026 | – | 2.60% | 2.50% |
| Sep 2026 | 1.23% | – | – |
| Aug 2026 | 1.19% | – | – |
| Jul 2026 | 1.14% | – | – |
| Q3 2026 | – | 2.60% | 2.50% |
| Jun 2026 | 1.08% | – | – |
| May 2026 | 1.06% | – | – |
| Apr 2026 | 1.03% | – | – |
| Q2 2026 | – | 2.60% | 2.50% |
| Mar 2026 | 1.07% | – | – |
| Feb 2026 | 1.12% | – | – |
| Jan 2026 | 1.15% | – | – |
| Q1 2026 | – | 2.60% | 2.50% |
| Dec 2025 | 1.19% | – | – |
| Nov 2025 | 1.25% | – | – |
| Oct 2025 | 1.32% | – | – |
| Q4 2025 | – | 2.60% | 2.50% |
| Sep 2025 | 1.45% | – | – |
| Aug 2025 | 1.56% | – | – |
| Jul 2025 | 1.85% | – | – |
| Q3 2025 | – | 2.60% | 2.50% |
| Jun 2025 | 2.05% | – | – |
| May 2025 | 2.27% | – | – |
| Apr 2025 | 2.36% | – | – |
| Q2 2025 | – | 2.60% | 2.50% |
| Mar 2025 | 2.55% | – | – |
| Feb 2025 | 2.73% | – | – |
| Jan 2025 | 2.90% | – | – |
| Q1 2025 | – | 2.60% | 2.50% |
| Dec 2024 | 3.03% | – | – |
| Nov 2024 | 3.21% | – | – |
| Oct 2024 | 3.38% | – | – |
| Q4 2024 | – | 2.60% | 2.50% |
| Sep 2024 | 3.49% | – | – |
| Aug 2024 | 3.57% | – | – |
| Jul 2024 | 3.64% | – | – |
| Q3 2024 | – | 2.60% | 2.50% |
| Jun 2024 | 3.63% | – | – |
| May 2024 | 3.66% | – | – |
| Apr 2024 | 3.65% | – | – |
| Q2 2024 | – | 2.60% | 2.50% |
| Mar 2024 | 3.68% | – | – |
| Feb 2024 | 3.65% | – | – |
| Jan 2024 | 3.65% | – | – |
| Q1 2024 | – | 2.60% | 2.50% |
| Dec 2023 | 3.70% | – | – |
| Nov 2023 | 3.75% | – | – |
| Oct 2023 | 3.75% | – | – |
| Q4 2023 | – | 2.60% | 2.50% |
| Sep 2023 | 3.70% | – | – |
| Aug 2023 | 3.70% | – | – |
| Jul 2023 | 3.67% | – | – |
| Q3 2023 | – | 2.60% | 2.50% |
| Jun 2023 | 3.65% | – | – |
| May 2023 | 3.62% | – | – |
| Apr 2023 | 3.61% | – | – |
| Q2 2023 | – | 2.60% | 2.50% |
| Mar 2023 | 3.58% | – | – |
| Feb 2023 | 3.22% | – | – |
| Jan 2023 | 3.14% | – | – |
| Q1 2023 | – | 2.60% | 2.50% |
| Dec 2022 | 3.03% | – | – |
| Nov 2022 | 2.92% | – | – |
| Oct 2022 | 2.46% | – | – |
| Q4 2022 | – | 2.60% | 2.50% |
| Sep 2022 | 2.07% | – | – |
| Aug 2022 | 1.60% | – | – |
| Jul 2022 | 1.27% | – | – |
| Q3 2022 | – | 2.60% | 2.50% |
| Jun 2022 | 0.77% | – | – |
| May 2022 | 0.53% | – | – |
| Apr 2022 | 0.32% | – | – |
| Q2 2022 | – | 2.60% | 2.50% |
| Mar 2022 | 0.28% | – | – |
| Feb 2022 | 0.25% | – | – |
| Jan 2022 | 0.21% | – | – |
| Q1 2022 | – | 2.60% | 2.50% |
| Dec 2021 | 0.19% | – | – |
| Nov 2021 | 0.16% | – | – |
| Oct 2021 | 0.16% | – | – |
| Q4 2021 | – | 2.60% | 2.50% |
| Sep 2021 | 0.13% | – | – |
| Aug 2021 | 0.13% | – | – |
| Jul 2021 | 0.13% | – | – |
| Q3 2021 | – | 2.60% | 2.50% |
| Jun 2021 | 0.13% | – | – |
| May 2021 | 0.17% | – | – |
| Apr 2021 | 0.19% | – | – |
| Q2 2021 | – | 2.60% | 2.50% |
| Mar 2021 | 0.22% | – | – |
| Feb 2021 | 0.20% | – | – |
| Jan 2021 | 0.17% | – | – |
| Q1 2021 | – | 2.60% | 2.50% |
| Dec 2020 | 0.17% | – | – |
| Nov 2020 | 0.12% | – | – |
| Oct 2020 | 0.12% | – | – |
| Q4 2020 | – | 2.60% | 2.50% |
| Sep 2020 | 0.10% | – | – |
| Aug 2020 | 0.10% | – | – |
| Jul 2020 | 0.08% | – | – |
| Q3 2020 | – | 2.60% | 2.50% |
| Jun 2020 | 0.14% | – | – |
| May 2020 | 0.27% | – | – |
| Apr 2020 | 0.53% | – | – |
| Q2 2020 | – | 2.60% | 2.50% |
| Mar 2020 | 0.88% | – | – |
| Feb 2020 | 1.14% | – | – |
| Jan 2020 | 1.20% | – | – |
| Q1 2020 | – | 2.60% | 2.50% |
| Dec 2019 | 1.26% | – | – |
| Nov 2019 | 1.31% | – | – |
| Oct 2019 | 1.46% | – | – |
| Q4 2019 | – | 2.60% | 2.50% |
| Sep 2019 | 1.53% | – | – |
| Aug 2019 | 1.59% | – | – |
| Jul 2019 | 1.67% | – | – |
| Q3 2019 | – | 2.60% | 2.50% |
| Jun 2019 | 1.72% | – | – |
| May 2019 | 1.68% | – | – |
| Apr 2019 | 1.62% | – | – |
| Q2 2019 | – | 2.60% | 2.50% |
| Mar 2019 | 1.54% | – | – |
| Feb 2019 | 1.59% | – | – |
| Jan 2019 | 1.55% | – | – |
| Q1 2019 | – | 2.60% | 2.50% |
Source: MAS, CPF Board. Data to 15 Oct 2026.
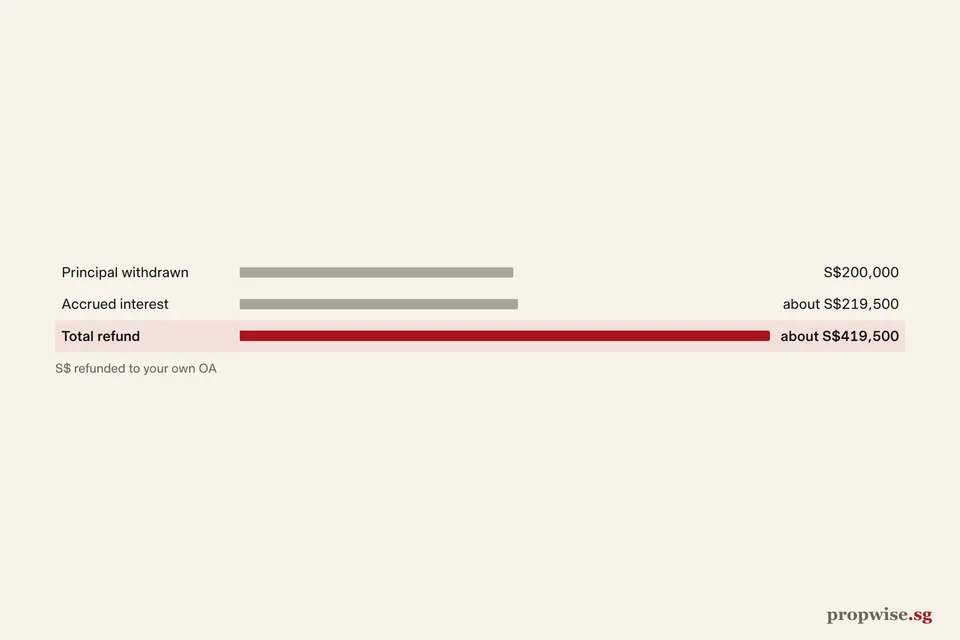
Money you spend on a home leaves the OA. CPF says you refund the principal plus accrued interest when you sell. For members below 55 the refund goes back to the OA.
CPF also warns that the more OA you use for property, the less CPF is left for retirement.
Our guides cover CPF and your home, buying before age 55 and the HDB home loan.