Does Population Growth Push Up Singapore Property Prices? (2026)
Does population growth lift Singapore property prices? Official data for 2009 to 2026 show years when people rose and prices fell. See why headcount misleads.
Population growth does not reliably move Singapore property prices. Between 2013 and 2016 the population rose 3.9% and private home prices fell 9.1%. Between 2016 and 2021 the population shrank 2.7% and prices rose 16.8%. Headcount matters less than who the new people are, whether they buy or rent, and how many homes the Government builds.
At a glance
- Singapore’s total population was 6.21 million in June 2026, up 1.6% in a year. Most of the growth was non-residents, not citizens or PRs.
- Since 2013, the population has grown about 15% and the URA private price index about 42.5%. In two of the three sub-periods since 2013, the two moved in opposite directions.
- Foreigners pay 60% ABSD and cannot buy HDB flats, so a rising foreign headcount lifts rental demand more than purchase demand.
- Interest rates, land supply and cooling measures explain more of the price cycles than headcount does.
What the population looks like in 2026
The National Population and Talent Division’s Population in Brief 2026 gives the June 2026 count:
| Group | June 2026 | Change on June 2025 |
|---|---|---|
| Citizens | 3.68 million | +0.7% |
| Permanent residents | 0.55 million | +0.5% |
| Non-residents | 1.98 million | +3.7% |
| Total | 6.21 million | +1.6% |
The report says the non-resident rise came mainly from Work Permit Holders, especially in construction for projects such as Changi Terminal 5, then from migrant domestic workers. Citizens are ageing: 21.4% were aged 65 or older in 2026, and the resident total fertility rate was 0.87 in 2025.
The 2013 Population White Paper, which the original version of this article questioned, said the total population could range between 6.5 million and 6.9 million by 2030. Since 2018 the Government has said the total is likely to be significantly below 6.9 million. To reach 6.9 million, the total would have to grow about 2.7% a year from today. Last year’s growth was 1.6%.
Population against prices: what the data show
The table sets the June population count against the URA private residential price index for Q2 of the same year. Population figures are from the 2026 and 2014 editions.
| Period | Population change | Private price change |
|---|---|---|
| 2009 to 2013 | +8.3% | +61.6% |
| 2013 to 2016 | +3.9% | −9.1% |
| 2016 to 2021 | −2.7% | +16.8% |
| 2021 to 2026 | +13.8% | +34.2% |
| 2013 to 2026 | +15.0% | +42.5% |
Only the first and last periods fit a simple “more people, higher prices” story. The middle two do not. In 2013 to 2016, cooling measures and the Total Debt Servicing Ratio arrived, and prices fell while the population grew steadily. From 2016 to 2021, the non-resident population fell by about 207,000, mostly during COVID-19, yet prices rose. A handful of data points show that the link is unstable.
Latest: Population 6,208,523 (2026), up 1.6% on 2025.
The total includes non-residents, such as work permit holders. Foreigners cannot buy HDB flats and pay 60% ABSD on private homes.
Table view
| Period | Total population |
|---|---|
| 2026 | 6,208,523 |
| 2025 | 6,111,175 |
| 2024 | 6,036,860 |
| 2023 | 5,917,648 |
| 2022 | 5,637,022 |
| 2021 | 5,453,566 |
| 2020 | 5,685,807 |
| 2019 | 5,703,569 |
| 2018 | 5,638,676 |
| 2017 | 5,612,253 |
| 2016 | 5,607,283 |
| 2015 | 5,535,002 |
| 2014 | 5,469,724 |
| 2013 | 5,399,162 |
| 2012 | 5,312,437 |
| 2011 | 5,183,688 |
| 2010 | 5,076,732 |
| 2009 | 4,987,573 |
| 2008 | 4,839,396 |
| 2007 | 4,588,599 |
| 2006 | 4,401,365 |
| 2005 | 4,265,762 |
| 2004 | 4,166,664 |
| 2003 | 4,114,826 |
| 2002 | 4,175,950 |
| 2001 | 4,138,012 |
| 2000 | 4,027,887 |
| 1999 | 3,958,723 |
| 1998 | 3,927,213 |
| 1997 | 3,796,038 |
| 1996 | 3,670,704 |
| 1995 | 3,524,506 |
| 1994 | 3,419,048 |
| 1993 | 3,313,471 |
| 1992 | 3,230,698 |
| 1991 | 3,135,083 |
| 1990 | 3,047,132 |
Source: Department of Statistics. Data to 2026.
- Policy measures (select one for details)
Latest: Private 222.5 (Q3 2026), up 3.4% on Q3 2025.
The index is a market average, not the price of any single home. Marked policy measures are shown for context only.
Table view
| Period | Private homes (URA price index) |
|---|---|
| Q3 2026 | 222.5 |
| Q2 2026 | 219.4 |
| Q1 2026 | 218.3 |
| Q4 2025 | 216.4 |
| Q3 2025 | 215.1 |
| Q2 2025 | 213.2 |
| Q1 2025 | 211.1 |
| Q4 2024 | 209.4 |
| Q3 2024 | 204.7 |
| Q2 2024 | 206.1 |
| Q1 2024 | 204.3 |
| Q4 2023 | 201.5 |
| Q3 2023 | 196.0 |
| Q2 2023 | 194.4 |
| Q1 2023 | 194.8 |
| Q4 2022 | 188.6 |
| Q3 2022 | 187.8 |
| Q2 2022 | 180.9 |
| Q1 2022 | 174.8 |
| Q4 2021 | 173.6 |
| Q3 2021 | 165.3 |
| Q2 2021 | 163.5 |
| Q1 2021 | 162.2 |
| Q4 2020 | 157.0 |
| Q3 2020 | 153.8 |
| Q2 2020 | 152.6 |
| Q1 2020 | 152.1 |
| Q4 2019 | 153.6 |
| Q3 2019 | 152.8 |
| Q2 2019 | 150.8 |
| Q1 2019 | 148.6 |
| Q4 2018 | 149.6 |
| Q3 2018 | 149.7 |
| Q2 2018 | 149.0 |
| Q1 2018 | 144.1 |
| Q4 2017 | 138.7 |
| Q3 2017 | 137.6 |
| Q2 2017 | 136.6 |
| Q1 2017 | 136.7 |
| Q4 2016 | 137.2 |
| Q3 2016 | 137.9 |
| Q2 2016 | 140.0 |
| Q1 2016 | 140.6 |
| Q4 2015 | 141.6 |
| Q3 2015 | 142.3 |
| Q2 2015 | 144.2 |
| Q1 2015 | 145.5 |
| Q4 2014 | 147.0 |
| Q3 2014 | 148.6 |
| Q2 2014 | 149.7 |
| Q1 2014 | 151.3 |
| Q4 2013 | 153.2 |
| Q3 2013 | 154.6 |
| Q2 2013 | 154.0 |
| Q1 2013 | 152.4 |
| Q4 2012 | 151.5 |
| Q3 2012 | 148.8 |
| Q2 2012 | 147.9 |
| Q1 2012 | 147.2 |
| Q4 2011 | 147.4 |
| Q3 2011 | 147.0 |
| Q2 2011 | 145.1 |
| Q1 2011 | 142.3 |
| Q4 2010 | 139.2 |
| Q3 2010 | 135.5 |
| Q2 2010 | 131.7 |
| Q1 2010 | 125.1 |
| Q4 2009 | 118.4 |
| Q3 2009 | 110.3 |
| Q2 2009 | 95.3 |
| Q1 2009 | 100.0 |
| Q4 2008 | 116.4 |
| Q3 2008 | 123.9 |
| Q2 2008 | 126.9 |
| Q1 2008 | 126.7 |
| Q4 2007 | 122.1 |
| Q3 2007 | 114.4 |
| Q2 2007 | 105.6 |
| Q1 2007 | 97.6 |
| Q4 2006 | 93.1 |
| Q3 2006 | 89.6 |
| Q2 2006 | 87.3 |
| Q1 2006 | 85.8 |
| Q4 2005 | 84.5 |
| Q3 2005 | 83.3 |
| Q2 2005 | 82.3 |
| Q1 2005 | 81.9 |
| Q4 2004 | 81.3 |
| Q3 2004 | 80.7 |
| Q2 2004 | 80.4 |
| Q1 2004 | 80.3 |
| Q4 2003 | 80.6 |
| Q3 2003 | 80.7 |
| Q2 2003 | 81.1 |
| Q1 2003 | 81.6 |
| Q4 2002 | 82.3 |
| Q3 2002 | 82.6 |
| Q2 2002 | 82.2 |
| Q1 2002 | 82.8 |
| Q4 2001 | 83.8 |
| Q3 2001 | 87.6 |
| Q2 2001 | 90.3 |
| Q1 2001 | 91.1 |
| Q4 2000 | 94.9 |
| Q3 2000 | 97.6 |
| Q2 2000 | 100.4 |
| Q1 2000 | 98.9 |
| Q4 1999 | 95.9 |
| Q3 1999 | 91.1 |
| Q2 1999 | 84.3 |
| Q1 1999 | 75.4 |
| Q4 1998 | 71.5 |
| Q3 1998 | 78.3 |
| Q2 1998 | 90.1 |
| Q1 1998 | 98.3 |
| Q4 1997 | 108.4 |
| Q3 1997 | 113.0 |
| Q2 1997 | 118.2 |
| Q1 1997 | 119.2 |
| Q4 1996 | 123.7 |
| Q3 1996 | 127.2 |
| Q2 1996 | 129.7 |
| Q1 1996 | 122.3 |
| Q4 1995 | 117.9 |
| Q3 1995 | 112.7 |
| Q2 1995 | 111.1 |
| Q1 1995 | 109.8 |
| Q4 1994 | 106.9 |
| Q3 1994 | 104.5 |
| Q2 1994 | 93.6 |
| Q1 1994 | 82.1 |
| Q4 1993 | 75.1 |
| Q3 1993 | 71.1 |
| Q2 1993 | 64.9 |
| Q1 1993 | 58.3 |
| Q4 1992 | 55.3 |
| Q3 1992 | 53.8 |
| Q2 1992 | 51.8 |
| Q1 1992 | 49.9 |
| Q4 1991 | 47.6 |
| Q3 1991 | 46.8 |
| Q2 1991 | 45.6 |
| Q1 1991 | 42.1 |
| Q4 1990 | 40.3 |
| Q3 1990 | 42.0 |
| Q2 1990 | 41.8 |
| Q1 1990 | 40.9 |
Policy measures marked on this chart (26)
- 2025-07-03 Seller's Stamp Duty holding period back to four years, rates raised by 4 pp
- 2024-08-19 HDB loan LTV cut to 75% and Enhanced CPF Housing Grant raised
- 2023-04-26 ABSD rates raised, April 2023
- 2023-02-14 CPF Housing Grant raised for first-time resale buyers, Budget 2023
- 2023-02-14 Buyer's Stamp Duty raised for higher-value properties, Budget 2023
- 2022-09-29 Property measures, September 2022: higher TDSR and MSR rate floor, HDB loan LTV 80%, 15-month wait-out
- 2021-12-15 Property cooling measures, December 2021: higher ABSD, TDSR 55%, HDB loan LTV 85%
- 2018-07-05 Property cooling measures, July 2018: higher ABSD and lower LTV limits
- 2018-02-19 Budget 2018: Proximity Housing Grant enhanced
- 2018-02-19 Budget 2018: top BSD rate raised to 4% above S$1m
- 2017-03-10 SSD holding period cut to 3 years; TDSR relaxed for equity withdrawal
- 2013-08-27 HDB loan and resale measures, August 2013
- 2013-06-28 MAS introduces the Total Debt Servicing Ratio (TDSR) framework
- 2013-01-11 Property cooling measures, January 2013
- 2012-10-05 Maximum loan tenure of 35 years and tighter LTV limits, October 2012
- 2011-12-07 Additional Buyer's Stamp Duty introduced, December 2011
- 2011-01-13 Property cooling measures, January 2011
- 2010-08-30 HDB measures after National Day Rally 2010: DBSS income ceiling, 5-year MOP for non-subsidised flats
- 2010-08-30 Property cooling measures, August 2010
- 2010-02-19 Seller's Stamp Duty introduced and LTV limit cut to 80%, February 2010
- 2009-09-14 Interest-only loans and Interest Absorption Scheme disallowed, September 2009
- 2005-07-19 Property policy review, July 2005: LTV limit raised to 90%, CPF housing rules eased, foreign ownership rules eased
- 2001-10-12 Second off-budget package, October 2001: property tax rebate, stamp duty cut, gains tax removed, land sales eased
- 1998-06-29 Off-budget property measures, June 1998: land sales suspended, stamp duty deferred
- 1997-11-18 Property relief, November 1997: seller's stamp duty suspended, land sales deferred
- 1996-05-14 Anti-speculation measures, May 1996: seller's stamp duty, tax on short-term gains, 80% loan limit
Source: URA. Data to Q3 2026.
Why a bigger headcount does not mean more buyers
Most of the growth is non-residents. From 2021 to 2026, the resident population (citizens and PRs) rose about 6.1%, to 4.23 million, while non-residents rose about 35%. Foreigners cannot buy HDB flats, and they pay 60% ABSD on any residential purchase. Many arrive on fixed-term passes. That kind of growth is more likely to show up in rental demand than in purchases.
% growth, 2021 to 2026
Source: National Population and Talent Division, Population in Brief 2026 (June 2026). The resident population (citizens and PRs) was 4.23 million in 2026.
Households matter more than people. Home demand comes from household formation: marriages, couples moving out of parents’ homes, and upgraders. The same report shows citizen marriages fell to 21,671 in 2025 from 22,955 in 2024, and citizen births fell to 26,071 from 29,237.
| Citizens | 2024 | 2025 |
|---|---|---|
| Marriages | 22,955 | 21,671 |
| Births | 29,237 | 26,071 |
Source: National Population and Talent Division, Population in Brief 2026 (June 2026).
Supply responds. The Government sets land sales and BTO volumes with population in mind. The 2026 Government Land Sales Confirmed List is 9,320 private units, more than 50% above the 10-year average, and HDB plans about 19,600 BTO flats in 2026. More people can lead to more homes and higher prices.
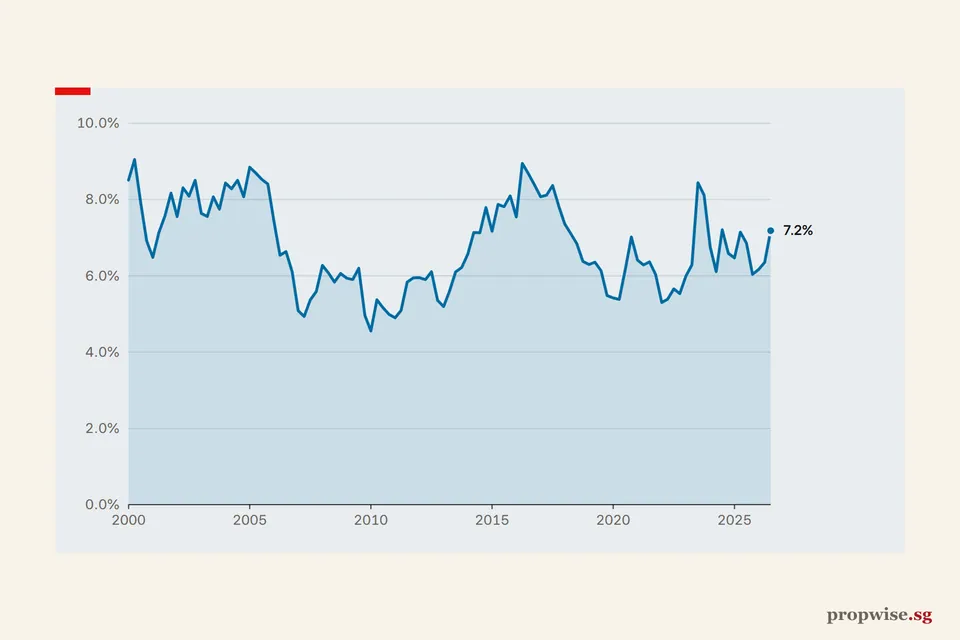
Rents show the limit. If headcount drove rents directly, a 1.6% rise in population would tighten the rental market. Yet URA reports that private rents rose only 1.3% quarter-on-quarter in Q3 2026, and 7.2% of completed private homes were vacant.
- Core Central Region
- Rest of Central Region
- Outside Central Region
Latest: CCR 2.1% (Q3 2026); RCR 1.9% (Q3 2026); OCR 1.8% (Q3 2026).
Change on the URA rental index: each quarter against the same quarter a year earlier.
Table view
| Period | Core Central Region | Rest of Central Region | Outside Central Region |
|---|---|---|---|
| Q3 2026 | 2.1% | 1.9% | 1.8% |
| Q2 2026 | 1.9% | 2.2% | 1.2% |
| Q1 2026 | 2.6% | 2.2% | 1.6% |
| Q4 2025 | 2.5% | 2.8% | 1.3% |
| Q3 2025 | 2.7% | 2.5% | 2.6% |
| Q2 2025 | 1.5% | 2.4% | 2.3% |
| Q1 2025 | -0.4% | 1.0% | 0.8% |
| Q4 2024 | -2.4% | -1.3% | -1.3% |
| Q3 2024 | -4.8% | -2.8% | -3.3% |
| Q2 2024 | -4.8% | -2.6% | -4.2% |
| Q1 2024 | -2.9% | 0.7% | -0.1% |
Source: URA. Data to Q3 2026.
What does move prices
Past cycles line up better with credit and policy: interest rates, loan limits, stamp duties and supply. Our guides on how interest rates affect property prices and how land supply works cover these in turn. For the current market read, see the 2026 outlook.
How to use population news
- Split the number. Ask how much of any increase is citizens and PRs (who can buy) and how much is non-residents (who mostly add to rental demand).
- Look at your segment. A rise in construction Work Permit Holders does little for a suburban condo’s resale price.
- Check the supply pipeline near you before you pay for “future demand”.
- Do not pay for a forecast. If a price only works when the population hits a target, it is a bet on a number the Government can change.
Bottom line
Population growth is a background factor. The official data show years in which people increased and prices fell, and years in which people fell and prices rose. Judge a property by what you pay, what you can borrow at today’s rates, and what is being built nearby.