Will Singapore Property Prices Crash? How to Prepare (2026)
Will Singapore property prices crash? Past crashes, what could trigger the next one, how today's rules change the odds, and how to stress-test your home loan.
Nobody can tell you when the next property crash will come, and anyone who gives you a date is guessing. What you can know is how past Singapore crashes happened, what would have to go wrong for one to happen now, and whether your own finances would survive it. As at October 2026, private prices are still rising slowly, HDB resale prices have dipped for three straight quarters, and the household debt numbers look healthy. A crash would need a real shock.
At a glance
- Singapore has had four big private-price falls since the mid-1990s: about −45% (1996–98), −20% (2000–04), −25% (2008–09) and −12% (2013–17).
- In Q3 2026 private home prices rose 1.4% quarter-on-quarter (flash estimate). HDB resale prices fell 0.2% quarter-on-quarter, a third small dip in a row.
- Today’s loan rules (TDSR at a 4% stress rate, 75% loan limit, 20% ABSD on a citizen’s second home) make the forced selling that drives crashes less likely.
- The main risks to watch are a jump in unemployment, a rebound in interest rates from today’s lows, and a large wave of new private supply.
- The best way to prepare is the same in any market: borrow what you can still pay at 4%, keep cash for 6–12 months of instalments, and know how you would exit before you buy.
Where the market stands in October 2026
URA’s full Q3 2026 figures show the private price index up 1.4% on the quarter, after +0.5% in Q2. Landed homes rose 2.9% on the quarter. Outside the city centre, homes rose 2.3% on the quarter, and core central region prices rose 0.3%. The index is at a record high.
Public housing is cooling. The HDB resale price index fell 0.1% quarter-on-quarter in Q1 2026 and 0.3% in Q2, then 0.1% quarter-on-quarter in Q3. That is a gentle drift of about 0.6% over the year, and resale volumes rose. You can see the same picture in our look at million-dollar HDB flats.
The economy is steady. MTI raised its 2026 growth forecast to 4.5–5.5% on 11 August 2026. Overall unemployment was 1.9% in June 2026, but retrenchments rose to 4,620 in Q2 from 3,830 in Q1.
Interest rates are low. MAS notes that three-month compounded SORA halved to around 1.1% by Q2 2026, and fixed home-loan packages fell to around 1.5%, from 2.5% a year earlier. Rates have started to turn: after the US Federal Reserve raised rates on 16 September 2026, banks lifted their packages to around 1.5–1.8% floating and 2.0–2.2% fixed, according to The Business Times (2 October 2026) and CNA.
What past Singapore crashes looked like
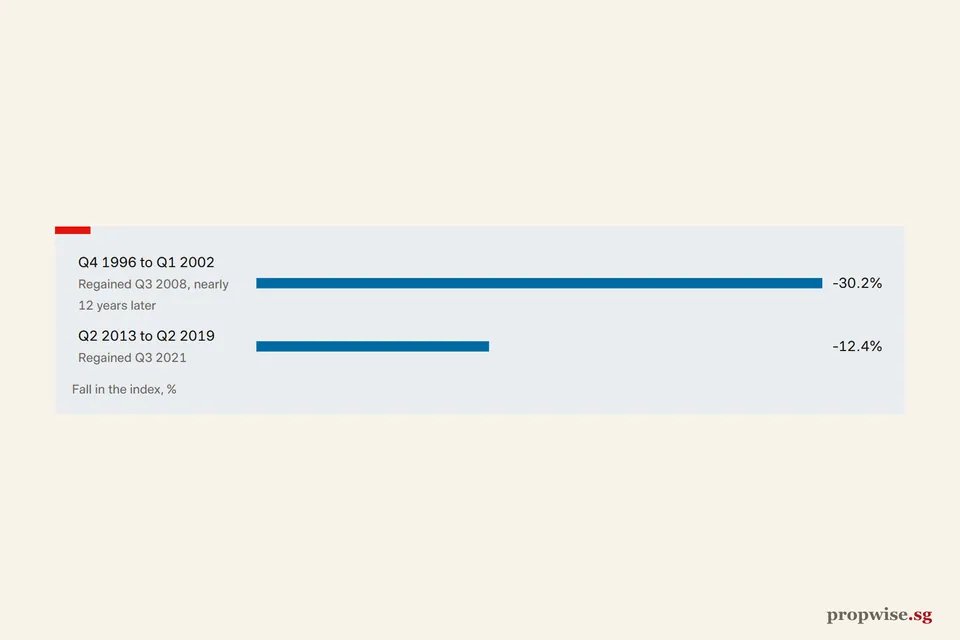
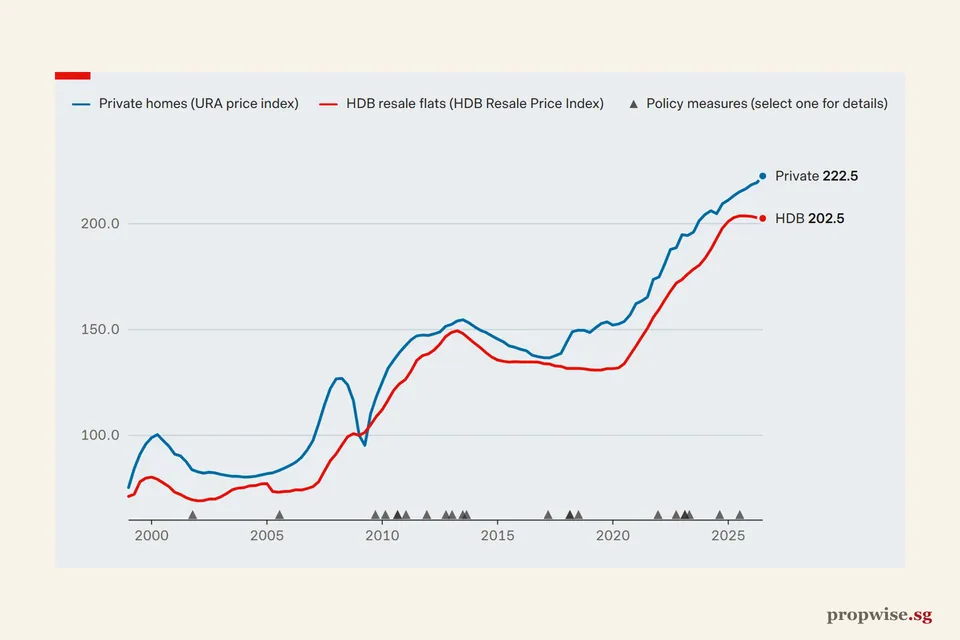
Here are the big falls in the URA private residential price index and the HDB resale price index. The trough is the lowest quarter; “back to peak” is when the index first regained its old high in nominal terms.
| Episode | Index | Peak → trough | Fall (peak to trough) | Back to peak |
|---|---|---|---|---|
| Asian financial crisis | URA private | Q2 1996 → Q4 1998 | −44.9% | Q2 2010 |
| Dot-com bust, SARS | URA private | Q2 2000 → Q1 2004 | −20.0% | Q2 2007 |
| Global financial crisis | URA private | Q2 2008 → Q2 2009 | −24.9% | Q2 2010 |
| Cooling measures, TDSR | URA private | Q3 2013 → Q2 2017 | −11.6% | Q4 2020 |
| COVID-19 | URA private | Q4 2019 → Q1 2020 | −1.0% | Q3 2020 |
| Late 1990s to 2002 | HDB resale | Q4 1996 → Q1 2002 | −30.2% | Q3 2008 |
| Cooling measures | HDB resale | Q2 2013 → Q2 2019 | −12.4% | Q3 2021 |
Fall from peak, per cent
Source: URA private residential price index (data.gov.sg) (figures as in the article, October 2026).
- Policy measures (select one for details)
Latest: Private 222.5 (Q3 2026), up 3.4% on Q3 2025.
The index is a market average, not the price of any single home. Marked policy measures are shown for context only.
Table view
| Period | Private homes (URA price index) |
|---|---|
| Q3 2026 | 222.5 |
| Q2 2026 | 219.4 |
| Q1 2026 | 218.3 |
| Q4 2025 | 216.4 |
| Q3 2025 | 215.1 |
| Q2 2025 | 213.2 |
| Q1 2025 | 211.1 |
| Q4 2024 | 209.4 |
| Q3 2024 | 204.7 |
| Q2 2024 | 206.1 |
| Q1 2024 | 204.3 |
| Q4 2023 | 201.5 |
| Q3 2023 | 196.0 |
| Q2 2023 | 194.4 |
| Q1 2023 | 194.8 |
| Q4 2022 | 188.6 |
| Q3 2022 | 187.8 |
| Q2 2022 | 180.9 |
| Q1 2022 | 174.8 |
| Q4 2021 | 173.6 |
| Q3 2021 | 165.3 |
| Q2 2021 | 163.5 |
| Q1 2021 | 162.2 |
| Q4 2020 | 157.0 |
| Q3 2020 | 153.8 |
| Q2 2020 | 152.6 |
| Q1 2020 | 152.1 |
| Q4 2019 | 153.6 |
| Q3 2019 | 152.8 |
| Q2 2019 | 150.8 |
| Q1 2019 | 148.6 |
| Q4 2018 | 149.6 |
| Q3 2018 | 149.7 |
| Q2 2018 | 149.0 |
| Q1 2018 | 144.1 |
| Q4 2017 | 138.7 |
| Q3 2017 | 137.6 |
| Q2 2017 | 136.6 |
| Q1 2017 | 136.7 |
| Q4 2016 | 137.2 |
| Q3 2016 | 137.9 |
| Q2 2016 | 140.0 |
| Q1 2016 | 140.6 |
| Q4 2015 | 141.6 |
| Q3 2015 | 142.3 |
| Q2 2015 | 144.2 |
| Q1 2015 | 145.5 |
| Q4 2014 | 147.0 |
| Q3 2014 | 148.6 |
| Q2 2014 | 149.7 |
| Q1 2014 | 151.3 |
| Q4 2013 | 153.2 |
| Q3 2013 | 154.6 |
| Q2 2013 | 154.0 |
| Q1 2013 | 152.4 |
| Q4 2012 | 151.5 |
| Q3 2012 | 148.8 |
| Q2 2012 | 147.9 |
| Q1 2012 | 147.2 |
| Q4 2011 | 147.4 |
| Q3 2011 | 147.0 |
| Q2 2011 | 145.1 |
| Q1 2011 | 142.3 |
| Q4 2010 | 139.2 |
| Q3 2010 | 135.5 |
| Q2 2010 | 131.7 |
| Q1 2010 | 125.1 |
| Q4 2009 | 118.4 |
| Q3 2009 | 110.3 |
| Q2 2009 | 95.3 |
| Q1 2009 | 100.0 |
| Q4 2008 | 116.4 |
| Q3 2008 | 123.9 |
| Q2 2008 | 126.9 |
| Q1 2008 | 126.7 |
| Q4 2007 | 122.1 |
| Q3 2007 | 114.4 |
| Q2 2007 | 105.6 |
| Q1 2007 | 97.6 |
| Q4 2006 | 93.1 |
| Q3 2006 | 89.6 |
| Q2 2006 | 87.3 |
| Q1 2006 | 85.8 |
| Q4 2005 | 84.5 |
| Q3 2005 | 83.3 |
| Q2 2005 | 82.3 |
| Q1 2005 | 81.9 |
| Q4 2004 | 81.3 |
| Q3 2004 | 80.7 |
| Q2 2004 | 80.4 |
| Q1 2004 | 80.3 |
| Q4 2003 | 80.6 |
| Q3 2003 | 80.7 |
| Q2 2003 | 81.1 |
| Q1 2003 | 81.6 |
| Q4 2002 | 82.3 |
| Q3 2002 | 82.6 |
| Q2 2002 | 82.2 |
| Q1 2002 | 82.8 |
| Q4 2001 | 83.8 |
| Q3 2001 | 87.6 |
| Q2 2001 | 90.3 |
| Q1 2001 | 91.1 |
| Q4 2000 | 94.9 |
| Q3 2000 | 97.6 |
| Q2 2000 | 100.4 |
| Q1 2000 | 98.9 |
| Q4 1999 | 95.9 |
| Q3 1999 | 91.1 |
| Q2 1999 | 84.3 |
| Q1 1999 | 75.4 |
| Q4 1998 | 71.5 |
| Q3 1998 | 78.3 |
| Q2 1998 | 90.1 |
| Q1 1998 | 98.3 |
| Q4 1997 | 108.4 |
| Q3 1997 | 113.0 |
| Q2 1997 | 118.2 |
| Q1 1997 | 119.2 |
| Q4 1996 | 123.7 |
| Q3 1996 | 127.2 |
| Q2 1996 | 129.7 |
| Q1 1996 | 122.3 |
| Q4 1995 | 117.9 |
| Q3 1995 | 112.7 |
| Q2 1995 | 111.1 |
| Q1 1995 | 109.8 |
| Q4 1994 | 106.9 |
| Q3 1994 | 104.5 |
| Q2 1994 | 93.6 |
| Q1 1994 | 82.1 |
| Q4 1993 | 75.1 |
| Q3 1993 | 71.1 |
| Q2 1993 | 64.9 |
| Q1 1993 | 58.3 |
| Q4 1992 | 55.3 |
| Q3 1992 | 53.8 |
| Q2 1992 | 51.8 |
| Q1 1992 | 49.9 |
| Q4 1991 | 47.6 |
| Q3 1991 | 46.8 |
| Q2 1991 | 45.6 |
| Q1 1991 | 42.1 |
| Q4 1990 | 40.3 |
| Q3 1990 | 42.0 |
| Q2 1990 | 41.8 |
| Q1 1990 | 40.9 |
Policy measures marked on this chart (26)
- 2025-07-03 Seller's Stamp Duty holding period back to four years, rates raised by 4 pp
- 2024-08-19 HDB loan LTV cut to 75% and Enhanced CPF Housing Grant raised
- 2023-04-26 ABSD rates raised, April 2023
- 2023-02-14 CPF Housing Grant raised for first-time resale buyers, Budget 2023
- 2023-02-14 Buyer's Stamp Duty raised for higher-value properties, Budget 2023
- 2022-09-29 Property measures, September 2022: higher TDSR and MSR rate floor, HDB loan LTV 80%, 15-month wait-out
- 2021-12-15 Property cooling measures, December 2021: higher ABSD, TDSR 55%, HDB loan LTV 85%
- 2018-07-05 Property cooling measures, July 2018: higher ABSD and lower LTV limits
- 2018-02-19 Budget 2018: Proximity Housing Grant enhanced
- 2018-02-19 Budget 2018: top BSD rate raised to 4% above S$1m
- 2017-03-10 SSD holding period cut to 3 years; TDSR relaxed for equity withdrawal
- 2013-08-27 HDB loan and resale measures, August 2013
- 2013-06-28 MAS introduces the Total Debt Servicing Ratio (TDSR) framework
- 2013-01-11 Property cooling measures, January 2013
- 2012-10-05 Maximum loan tenure of 35 years and tighter LTV limits, October 2012
- 2011-12-07 Additional Buyer's Stamp Duty introduced, December 2011
- 2011-01-13 Property cooling measures, January 2011
- 2010-08-30 HDB measures after National Day Rally 2010: DBSS income ceiling, 5-year MOP for non-subsidised flats
- 2010-08-30 Property cooling measures, August 2010
- 2010-02-19 Seller's Stamp Duty introduced and LTV limit cut to 80%, February 2010
- 2009-09-14 Interest-only loans and Interest Absorption Scheme disallowed, September 2009
- 2005-07-19 Property policy review, July 2005: LTV limit raised to 90%, CPF housing rules eased, foreign ownership rules eased
- 2001-10-12 Second off-budget package, October 2001: property tax rebate, stamp duty cut, gains tax removed, land sales eased
- 1998-06-29 Off-budget property measures, June 1998: land sales suspended, stamp duty deferred
- 1997-11-18 Property relief, November 1997: seller's stamp duty suspended, land sales deferred
- 1996-05-14 Anti-speculation measures, May 1996: seller's stamp duty, tax on short-term gains, 80% loan limit
Source: URA. Data to Q3 2026.
Three lessons stand out.
- Shock crashes are fast. Policy-driven falls are slow. The 2008–09 fall took four quarters and then reversed sharply when rates were cut. The 2013–17 decline was a four-year grind caused by TDSR and stamp duties.
- “Prices always recover” depends on your timeline. A buyer at the 1996 peak waited about 14 years just to get back to the purchase price, before costs and interest. Our article Do property prices always recover? goes deeper.
- The index hides the pain. It is an average; buyers of peak-priced new launches or high-quantum homes often lost more.
How property busts actually happen
Prices crash when many owners must sell at the same time and few buyers can borrow. The usual chain:
- A shock hits incomes or rates. Examples are a recession, a banking scare, or a sharp rate rise.
- Stretched owners fall behind. Owners who borrowed at the limit cannot meet their instalments, especially if they lose their jobs.
- Banks tighten. Valuations fall, so lenders lend less against each property, and fewer buyers qualify.
- Forced sales set new, lower prices. Each sale gives the bank’s valuer a lower benchmark, and the cycle feeds itself.
- 1A shock hits incomes or ratesA recession, a banking scare or a sharp rate rise.
- 2Stretched owners fall behindOwners who borrowed at the limit cannot meet instalments, especially after a job loss.
- 3Banks tightenValuations fall, lenders lend less against each property and fewer buyers qualify.
- 4Forced sales set lower pricesEach sale gives the valuer a lower benchmark and the cycle feeds itself.
Source: Propwise summary of the article text; rules from MAS (October 2026).
The real driver is the supply and demand of credit. A glut of new homes hurts when it meets a credit squeeze or a jobs shock. On its own, it usually means slower price growth and developer discounts. That is why unemployment is the real killer in property: a job loss turns a paper loss into a forced sale.
Why a 1997-style crash is less likely now, but not impossible
Several rules now in force work against the forced-selling chain:
- TDSR of 55%, tested at 4%. MAS rules cap all your monthly debt repayments at 55% of gross income, calculated at a medium-term rate of at least 4%, even though actual packages now cost about 1.5–2.2%. Most borrowers therefore have a built-in cushion.
- Lower loan limits. Banks lend at most 75% on a first housing loan and 45% on a second. HDB loans are capped at 75%, down from 90% before December 2021.
- High transaction taxes. ABSD for a Singapore citizen’s second home is 20%, and 60% for foreigners. Since 4 July 2025, Seller’s Stamp Duty applies to homes sold within four years, at up to 16%. These rules keep short-term speculators, the first to panic, out of the market.
- Healthy household balance sheets. The MAS Financial Stability Review (September 2026) puts the housing non-performing loan ratio at 0.2% in Q2 2026. Household debt edged up to 1.08 times disposable income, below its 10-year average. In MAS’s stress test (income down about 10%, mortgage rates up 200 basis points), about 1% of borrowers could run into negative cash flow with savings covering less than six months.
The risks are real too:
- Supply. The 2026 Government Land Sales Confirmed List will yield about 9,320 units, more than 50% above the 10-year average. MAS counts about 32,000 unsold units in the pipeline. If demand weakens, that stock will press on prices, especially for new launches.
- Rates. Many 2026 buyers took loans at about 1.5%, and packages are already edging up after the September Fed hike. If rates climb back towards 2023 levels, instalments jump, as the worked example below shows. MAS itself warns of “the risk of further rises in global interest rates”.
- External shocks. MAS names a sharp AI-related downturn, energy prices and geopolitics as risks. Singapore’s open economy also feels US tariff changes.
Policy cuts both ways too: the government cools the market when prices run ahead of incomes, so do not expect quick rescues for speculators in a downturn.
Stress-test your own position
The question that matters is “would I be forced to sell if prices crashed?” Here is a worked example.
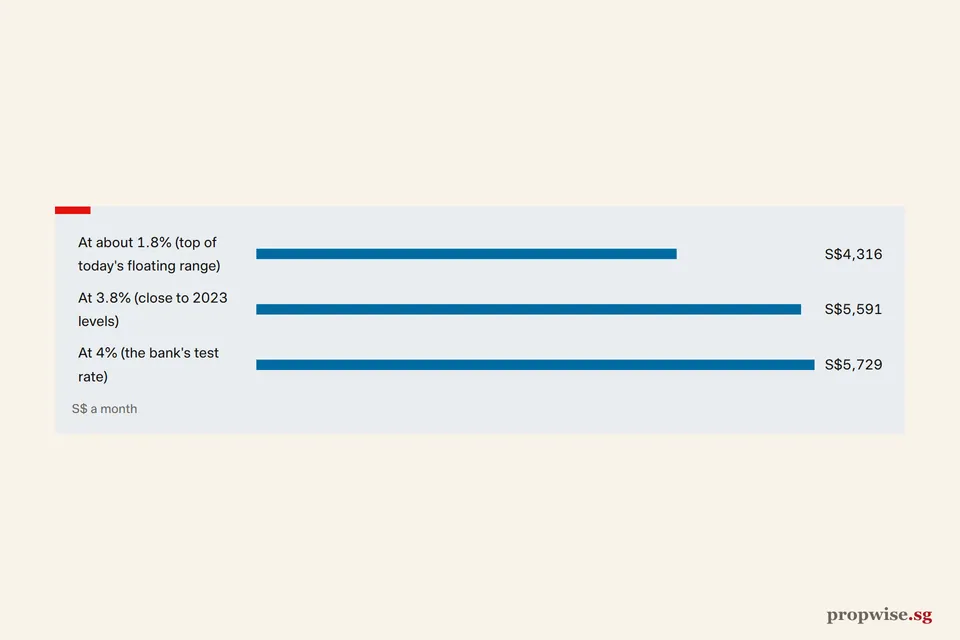
Say you buy a S$1.5 million condo with a 75% bank loan of S$1.125 million over 30 years.
| Interest rate | Monthly instalment |
|---|---|
| 2.0% (around today’s fixed packages) | S$4,158 |
| 3.0% | S$4,743 |
| 4.0% (the TDSR stress rate) | S$5,371 |
S$ per month
Source: TDSR stress rate from MAS (October 2026).
At 4%, the S$5,371 instalment must fit within 55% of your income, so you need a gross household income of at least about S$9,770 a month with no other debts. If your income only passes at today’s rates, you have no safety margin.
Now the downside. Your 25% down payment (S$375,000, from cash and CPF) is the first loss. Prices would have to fall 25% before the home is worth less than the loan on day one. After three years of payments at 2%, the loan is down to about S$1.04 million, so it would take a fall of about 31%. Negative equity alone does not force a sale. Margin calls on home loans are rare in Singapore, but whether the bank can ask for a top-up depends on your loan terms, so read the letter of offer. The danger comes when negative equity meets a job loss or a refinancing.
Run your own numbers at 2%, 3% and 4% with the Propwise mortgage calculator.
Five ways to prepare, whether you own or are waiting to buy
- Borrow for the bad year, not the good one. Make sure you can pay at 4% on one income, or on the lower of two incomes plus savings. If you can’t, take a smaller loan or a cheaper home.
- Build holding power. Keep 6–12 months of instalments, maintenance and property tax in cash. Do not count on your CPF OA as a buffer if you already use it to service the loan.
- Be honest about investment property. A citizen buying a S$1.2 million second home pays S$32,600 in BSD and S$240,000 in ABSD, about 22.7% of the price. The property must rise about that much before you break even, before agent fees and interest. In a flat or falling market, that hole is deep. Our guide when is the right time to enter the market looks at timing.
- Plan your exit at the entrance. Know your SSD window (four years for homes bought since 4 July 2025), your HDB MOP, and what you would do if you had to sell in a weak market. Could rent cover the instalment?
- If you are waiting for a crash, get ready, not stuck. Past bargain windows (2003–05, early 2009) went to buyers who had cash, loan approval and a shortlist when others were scared. But waiting has a cost too: the private index has risen about 60% since its 2017 trough. A “meaningful correction” in Singapore has more often been a slow grind than a crash.
Be sceptical of forecasts in both directions: people who say prices “never fall” and people who predict a crash every year are both selling something. See Should you believe expert forecasts?
Bottom line
Singapore property can fall a lot. It fell about 45% in the late 1990s and 25% in 2008–09. But a crash needs forced sellers, and today’s loan limits, stress tests and stamp duties make it harder for many owners to become forced sellers at once. The data in October 2026 points to a market that is flat to slightly up, with supply and interest rates as the main things to watch. You can control how much you borrow, how much cash you keep, and whether you would have to sell at the bottom.
2 reader comments
Rama Kasi
I liked your article. Very sensible and truly a great guide for ordinary investors. Thank you.
Karen Yap
Hi, is our property in singapore a surprime like the US and will wipe out the banks when the ultimate crash comes?