7 Singapore Property Investment Myths That Cost Money (2026)
Seven Singapore property investment myths tested against 2026 rules and data: rising prices, rent covering the mortgage, ABSD, lease decay and forecasts.
The most expensive property myths in Singapore are not outright lies. Each one holds a grain of truth: prices usually rise over long periods, rent does cover part of the mortgage, and leverage does magnify gains. What the myth leaves out is the cost, the timing and the risk. Here are seven beliefs worth testing against 2026 rules and numbers before you commit a six- or seven-figure sum.
At a glance
- Singapore property prices have fallen for years at a time, and HDB resale prices have dipped for three straight quarters in 2026.
- A rent that matches the mortgage instalment still leaves you short once tax, fees and repairs are paid.
- A 20% ABSD on a second home needs roughly 4% a year price growth over five years just to break even.
- Leases run down. Buyers of older flats get less CPF and grant support, and en bloc sales are never guaranteed.
- Many of the loudest market voices, from agents to developers to course sellers, earn more when you buy. Weigh their forecasts with that in mind.
Myth 1: “Property prices always go up in the long run”
Over decades, Singapore prices have risen. But “the long run” can be longer than your holding power.
URA’s private residential price index fell 45% from its peak in the second quarter of 1996 to the end of 1998. It fell again by about 12% between the third quarter of 2013 and the second quarter of 2017, a slide of nearly four years. HDB’s resale price index fell about 12% from its 2013 peak and did not bottom out until 2019. Someone who bought at the 2013 peak with a large loan, then lost their job in 2016, could have been forced to sell at a loss.
Even the long-run numbers depend on when you start. Measured from the 1996 peak to the second quarter of 2026, private prices rose only about 1.8% a year.
Fall from peak, per cent
Source: URA private residential price index (data.gov.sg) (Q2 2026); HDB resale price index (data.gov.sg).
Right now, the two markets are moving apart. URA’s private price index rose 1.4% in Q3 2026 (flash estimate), while HDB’s resale price index fell 0.2%, its third straight quarterly dip. Supply is also rising: the Government Land Sales programme for 2026 offers 9,320 private homes on its Confirmed Lists, more than 50% above the 10-year average. None of this means prices will fall. It means they do not move in one direction only. Our article on whether property prices always recover looks at past cycles in more detail.
- Private homes (URA price index)
- HDB resale flats (HDB Resale Price Index)
- Policy measures (select one for details)
Latest: Private 219.4 (Q2 2026); HDB 202.8 (Q2 2026).
Table view
| Period | Private homes (URA price index) | HDB resale flats (HDB Resale Price Index) |
|---|---|---|
| Q2 2026 | 219.4 | 202.8 |
| Q1 2026 | 218.3 | 203.4 |
| Q4 2025 | 216.4 | 203.6 |
| Q3 2025 | 215.1 | 203.7 |
| Q2 2025 | 213.2 | 202.9 |
| Q1 2025 | 211.1 | 201.0 |
| Q4 2024 | 209.4 | 197.9 |
| Q3 2024 | 204.7 | 192.9 |
| Q2 2024 | 206.1 | 187.9 |
| Q1 2024 | 204.3 | 183.7 |
| Q4 2023 | 201.5 | 180.4 |
| Q3 2023 | 196.0 | 178.5 |
| Q2 2023 | 194.4 | 176.2 |
| Q1 2023 | 194.8 | 173.6 |
| Q4 2022 | 188.6 | 171.9 |
| Q3 2022 | 187.8 | 168.1 |
| Q2 2022 | 180.9 | 163.9 |
| Q1 2022 | 174.8 | 159.5 |
| Q4 2021 | 173.6 | 155.7 |
| Q3 2021 | 165.3 | 150.6 |
| Q2 2021 | 163.5 | 146.4 |
| Q1 2021 | 162.2 | 142.2 |
| Q4 2020 | 157.0 | 138.1 |
| Q3 2020 | 153.8 | 133.9 |
| Q2 2020 | 152.6 | 131.9 |
| Q1 2020 | 152.1 | 131.5 |
| Q4 2019 | 153.6 | 131.5 |
| Q3 2019 | 152.8 | 130.9 |
| Q2 2019 | 150.8 | 130.8 |
| Q1 2019 | 148.6 | 131.0 |
| Q4 2018 | 149.6 | 131.4 |
| Q3 2018 | 149.7 | 131.6 |
| Q2 2018 | 149.0 | 131.7 |
| Q1 2018 | 144.1 | 131.6 |
| Q4 2017 | 138.7 | 132.6 |
| Q3 2017 | 137.6 | 132.8 |
| Q2 2017 | 136.6 | 133.7 |
| Q1 2017 | 136.7 | 133.9 |
| Q4 2016 | 137.2 | 134.6 |
| Q3 2016 | 137.9 | 134.7 |
| Q2 2016 | 140.0 | 134.7 |
| Q1 2016 | 140.6 | 134.7 |
| Q4 2015 | 141.6 | 134.8 |
| Q3 2015 | 142.3 | 134.6 |
| Q2 2015 | 144.2 | 135.0 |
| Q1 2015 | 145.5 | 135.6 |
| Q4 2014 | 147.0 | 137.0 |
| Q3 2014 | 148.6 | 139.1 |
| Q2 2014 | 149.7 | 141.5 |
| Q1 2014 | 151.3 | 143.5 |
| Q4 2013 | 153.2 | 145.8 |
| Q3 2013 | 154.6 | 148.1 |
| Q2 2013 | 154.0 | 149.4 |
| Q1 2013 | 152.4 | 148.6 |
| Q4 2012 | 151.5 | 146.7 |
| Q3 2012 | 148.8 | 143.1 |
| Q2 2012 | 147.9 | 140.3 |
| Q1 2012 | 147.2 | 138.5 |
| Q4 2011 | 147.4 | 137.7 |
| Q3 2011 | 147.0 | 135.4 |
| Q2 2011 | 145.1 | 130.4 |
| Q1 2011 | 142.3 | 126.4 |
| Q4 2010 | 139.2 | 124.4 |
| Q3 2010 | 135.5 | 121.3 |
| Q2 2010 | 131.7 | 116.6 |
| Q1 2010 | 125.1 | 112.1 |
| Q4 2009 | 118.4 | 109.0 |
| Q3 2009 | 110.3 | 105.0 |
| Q2 2009 | 95.3 | 101.4 |
| Q1 2009 | 100.0 | 100.0 |
| Q4 2008 | 116.4 | 100.8 |
| Q3 2008 | 123.9 | 99.4 |
| Q2 2008 | 126.9 | 95.4 |
| Q1 2008 | 126.7 | 91.3 |
| Q4 2007 | 122.1 | 88.0 |
| Q3 2007 | 114.4 | 83.2 |
| Q2 2007 | 105.6 | 78.1 |
| Q1 2007 | 97.6 | 75.8 |
| Q4 2006 | 93.1 | 74.9 |
| Q3 2006 | 89.6 | 74.2 |
| Q2 2006 | 87.3 | 74.3 |
| Q1 2006 | 85.8 | 73.6 |
| Q4 2005 | 84.5 | 73.5 |
| Q3 2005 | 83.3 | 73.2 |
| Q2 2005 | 82.3 | 73.5 |
| Q1 2005 | 81.9 | 77.2 |
| Q4 2004 | 81.3 | 77.1 |
| Q3 2004 | 80.7 | 76.3 |
| Q2 2004 | 80.4 | 76.2 |
| Q1 2004 | 80.3 | 75.3 |
| Q4 2003 | 80.6 | 75.1 |
| Q3 2003 | 80.7 | 74.3 |
| Q2 2003 | 81.1 | 72.5 |
| Q1 2003 | 81.6 | 71.0 |
| Q4 2002 | 82.3 | 69.9 |
| Q3 2002 | 82.6 | 69.9 |
| Q2 2002 | 82.2 | 69.2 |
| Q1 2002 | 82.8 | 69.1 |
| Q4 2001 | 83.8 | 69.6 |
| Q3 2001 | 87.6 | 70.6 |
| Q2 2001 | 90.3 | 72.1 |
| Q1 2001 | 91.1 | 73.2 |
| Q4 2000 | 94.9 | 75.8 |
| Q3 2000 | 97.6 | 77.6 |
| Q2 2000 | 100.4 | 79.3 |
| Q1 2000 | 98.9 | 80.3 |
| Q4 1999 | 95.9 | 79.8 |
| Q3 1999 | 91.1 | 78.1 |
| Q2 1999 | 84.3 | 72.2 |
| Q1 1999 | 75.4 | 71.2 |
Policy measures marked on this chart (23)
- 2025-07-03 Seller's Stamp Duty holding period back to four years, rates raised by 4 pp
- 2024-08-19 HDB loan LTV cut to 75% and Enhanced CPF Housing Grant raised
- 2023-04-26 ABSD rates raised, April 2023
- 2023-02-14 CPF Housing Grant raised for first-time resale buyers, Budget 2023
- 2023-02-14 Buyer's Stamp Duty raised for higher-value properties, Budget 2023
- 2022-09-29 Property measures, September 2022: higher TDSR and MSR rate floor, HDB loan LTV 80%, 15-month wait-out
- 2021-12-15 Property cooling measures, December 2021: higher ABSD, TDSR 55%, HDB loan LTV 85%
- 2018-07-05 Property cooling measures, July 2018: higher ABSD and lower LTV limits
- 2018-02-19 Budget 2018: Proximity Housing Grant enhanced
- 2018-02-19 Budget 2018: top BSD rate raised to 4% above S$1m
- 2017-03-10 SSD holding period cut to 3 years; TDSR relaxed for equity withdrawal
- 2013-08-27 HDB loan and resale measures, August 2013
- 2013-06-28 MAS introduces the Total Debt Servicing Ratio (TDSR) framework
- 2013-01-11 Property cooling measures, January 2013
- 2012-10-05 Maximum loan tenure of 35 years and tighter LTV limits, October 2012
- 2011-12-07 Additional Buyer's Stamp Duty introduced, December 2011
- 2011-01-13 Property cooling measures, January 2011
- 2010-08-30 HDB measures after National Day Rally 2010: DBSS income ceiling, 5-year MOP for non-subsidised flats
- 2010-08-30 Property cooling measures, August 2010
- 2010-02-19 Seller's Stamp Duty introduced and LTV limit cut to 80%, February 2010
- 2009-09-14 Interest-only loans and Interest Absorption Scheme disallowed, September 2009
- 2005-07-19 Property policy review, July 2005: LTV limit raised to 90%, CPF housing rules eased, foreign ownership rules eased
- 2001-10-12 Second off-budget package, October 2001: property tax rebate, stamp duty cut, gains tax removed, land sales eased
Myth 2: “The rent will pay the mortgage”
Say you buy a S$1.2m condo with a S$900,000 loan over 30 years at 2%. The instalment is about S$3,327 a month, and the unit rents for S$3,800. It looks covered.
It is not. Take off vacancy, agent fees, maintenance, property tax at the non-owner-occupied rates, repairs and income tax on the rental profit, and you are about S$990 a month out of pocket in year 1. Our return on investment guide shows the full calculation. Part of that shortfall is principal, so it builds your equity. But it is still cash you must find every month, from your salary, for years.
Banks know this. They assess your loan at a 4% stress-test rate, well above today’s rates, and cap all your debt repayments at a 55% Total Debt Servicing Ratio. Plan your own budget the same way.
Myth 3: “Capital gains will make up for poor cash flow”
This myth has been around for decades, and the 2026 rules make it more dangerous than ever.
A Singapore Citizen buying a second home pays 20% Additional Buyer’s Stamp Duty on top of Buyer’s Stamp Duty; a third home costs 30%. On a S$1.2m condo, that is S$240,000 you never get back. In our worked example, the investor needs about 4% a year growth over five years just to break even after ABSD, costs and negative cash flow. At 2% a year, the return is about −5% a year on the cash invested.
| Buyer | 1st home | 2nd home | 3rd home and later |
|---|---|---|---|
| Singapore citizen | 0% | 20% | 30% |
| Singapore permanent resident | 5% | 30% | 35% |
| Foreigner | 60% on every purchase | ||
| Entity (company, partnership and similar) | 65% | ||
| Trust | 65% | ||
| Housing developer | 40% (35% can be remitted if the project is completed and sold in time) | ||
And you cannot sell quickly if things go wrong. Homes bought from 4 Jul 2025 pay Seller’s Stamp Duty of 16% if sold within a year, falling to 4% in year 4. A deal that only works if prices rise fast is a bet, not an investment.
| When you sell | Seller’s Stamp Duty |
|---|---|
| Within 1 year of purchase | 16% |
| More than 1 year, up to 2 years | 12% |
| More than 2 years, up to 3 years | 8% |
| More than 3 years, up to 4 years | 4% |
Myth 4: “Decoupling or a 99-to-1 split is a safe way around ABSD”
Some buyers have tried to avoid ABSD by transferring a share of their home to one spouse (decoupling) or buying a new home in a 99%/1% split. IRAS can disregard any arrangement whose purpose is to reduce stamp duty and add a 50% surcharge, with no time limit on audits. By April 2024, IRAS had reviewed 187 cases, found avoidance in 166 and clawed back about S$60m.
Whether a particular arrangement counts as avoidance depends on the facts. That is exactly why “everyone does it” is not a safe basis for a seven-figure decision. Get a lawyer’s written advice on your own facts first.
Myth 5: “Any property is a good long-term investment if you just hold it”
Time helps only if the asset holds its value over that time, and leasehold property eventually does not. HDB flats and most private condos sit on 99-year leases. As the lease shortens, the pool of buyers who can finance your unit shrinks: buyers can use their CPF in full only if the remaining lease covers the youngest buyer to age 95, and the Enhanced CPF Housing Grant is paid in full only on the same condition. Fewer buyers with less money usually means weaker prices for older flats.
En bloc is not a plan either. Under changes to the collective sale rules tabled by the Ministry of Law in August 2026 and passed by Parliament on 8 September 2026, owners of developments 40 to 59 years old will need 70% consent instead of 80%, and 65% for developments 60 years and older. The law is not yet in force and the new thresholds have no start date yet, and they still need a developer willing to pay. Our guide to leasehold and lease decay explains how to value what is left.
| Age of development | Consent today | Consent under the new law |
|---|---|---|
| 40 to 59 years | 80% | 70% |
| 60 years or more | 80% | 65% |
Source: Ministry of Law, collective sale proposals (October 2026). Consent is by share value and area. The old rules apply until the new law starts.
Myth 6: “The experts quoted in the news know where prices are going”
The people most often quoted on the market are agency heads, developers and consultants. They know the market well, but most are paid when transactions happen. Forecasts made at the start of a year often miss, because the biggest moves in Singapore usually come from policy changes no one announces in advance: ABSD rose in December 2021 and again in April 2023, the HDB loan limit fell from 90% to 75% of the price in three steps between 2021 and 2024, and the SSD holding period went from three years to four in July 2025.
- 1December 2021ABSD risesAdditional Buyer's Stamp Duty goes up.
- 22021 to 2024HDB loan limit fallsThe limit drops from 90% to 75% of the price, in three steps.
- 3April 2023ABSD rises againA second increase in Additional Buyer's Stamp Duty.
- 4July 2025SSD holding period extendedThe Seller's Stamp Duty holding period goes from three years to four.
Source: MND, December 2021 measures (December 2021); MND, April 2023 measures; MAS, July 2025 SSD change; MyNiceHome, HDB loans guide.
Treat a forecast as one person’s view, ask how they are paid, and check their past calls. Our article on whether you should believe expert forecasts goes further.
Myth 7: “You must always be invested in property to beat inflation”
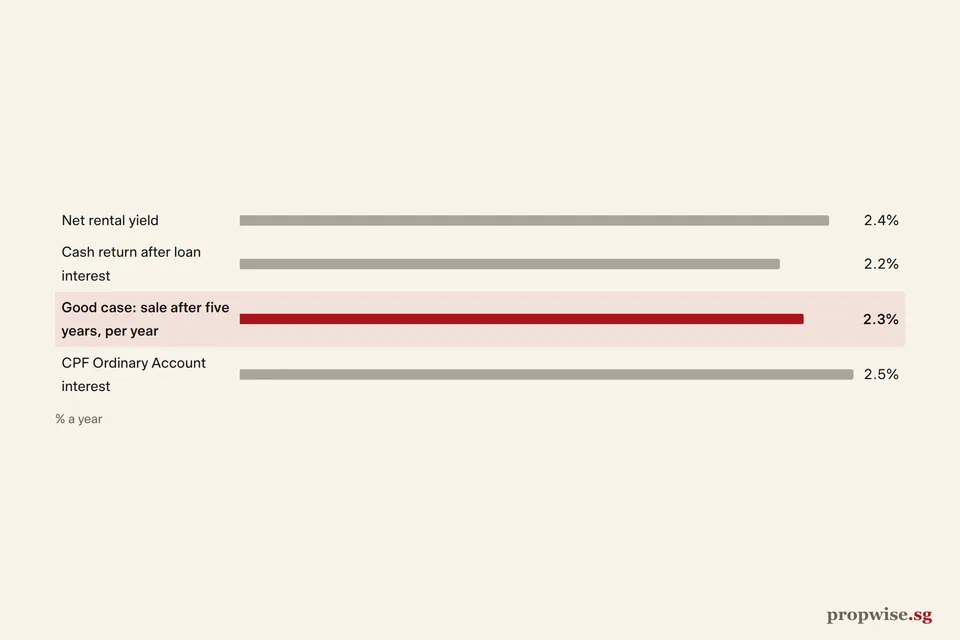
Never buy just to be in the market. Inflation matters, but it is not running away: MAS core inflation was 2.2% in August 2026. A property bought at the wrong price, with a thin yield and a large ABSD bill, can lag a CPF account for a decade. Cash in CPF earns 2.5% in the Ordinary Account and at least 4% in the Special, MediSave and Retirement Accounts with no tenants or repairs. A property has to beat that, after costs and with its extra risk, to be worth buying.
Per cent a year
Source: MAS, consumer price developments August 2026 (August 2026); CPF Board, interest rates.
The investors who do well over a full cycle usually keep cash and borrowing capacity in reserve, buy when the numbers work, and are prepared to wait when they do not. That is less exciting than a seminar promise of “millions from property”, but it is how most people avoid the big losses.
Bottom line
Every myth here survives because it is partly true. Prices do tend to rise over long periods, rent does help, and leverage does magnify gains. The question to ask of any pitch is what it leaves out: ABSD and SSD, negative cash flow, lease decay, policy changes and the chance of a long flat or falling market. If a deal still works after you add those back, it may be worth a closer look. If it only works on the optimistic case, walk away.