Freehold vs Leasehold in Singapore: What a Lease Is Worth
Freehold vs leasehold in Singapore: what a 99-year lease is worth as it runs down, the CPF age-95 rule, HDB loan limits and the new en bloc thresholds.
A leasehold home in Singapore is worth less than freehold, and the gap widens as the lease runs down. On discounting maths, a 60-year lease is worth 83% to 95% of freehold. In HDB resales, flats with 45 to 54 years left sold for a median 41% less per sqm than flats with 85 to 94 years left.
That last figure covers HDB resales from 2024 to September 2026, compared within the same town, flat type and year (our lease decay study). The rules below are as at October 2026. To value a leasehold home, work out what the remaining years are worth, and who will be able to buy it from you when you sell.
At a glance
- Most private condos and all HDB flats are on 99-year leases. When the lease ends, the land and building go back to the State.
- Decay is slow at first and fast later: going from 99 to 80 years left costs little, going from 40 to 20 costs a lot.
- Full CPF use needs the remaining lease to cover the youngest buyer to age 95. A shorter lease means pro-rated CPF and fewer buyers.
- An HDB loan can run only to the remaining lease minus 20 years.
- En bloc is a bonus. Lower consent thresholds for older estates have been passed and start on a date the Ministry of Law will announce.
What is leasehold in Singapore?
Singapore homes come in three main tenures: 99-year leasehold, 999-year leasehold and freehold. In practice, 999-year land is valued much like freehold.
The 99-year lease usually runs from the date the land lease was granted. That is often years before your purchase, or even before the project is completed. A new launch can have a few years of its lease used up before you get your keys.
When a 99-year lease ends, the land returns to the State, and owners get nothing for it. That is also true for HDB flats, unless the estate is redeveloped first.
A freehold building still ages and needs repairs. You own the land for ever, but you still manage the building on it.
How much is a lease worth as it runs down?
Think of a lease as a stream of future use or rent that stops on a fixed date. Its value today is the present value of that stream. A freehold property’s stream never stops.
The table shows the value of a lease as a percentage of an otherwise identical freehold property. It assumes constant net rent and three different discount rates.
| Years left on lease | At 3% | At 4% | At 5% |
|---|---|---|---|
| 99 | 94.6% | 97.9% | 99.2% |
| 80 | 90.6% | 95.7% | 98.0% |
| 60 | 83.0% | 90.5% | 94.6% |
| 50 | 77.2% | 85.9% | 91.3% |
| 40 | 69.3% | 79.2% | 85.8% |
| 30 | 58.8% | 69.2% | 76.9% |
| 20 | 44.6% | 54.4% | 62.3% |
% of freehold value
Source: Present value of a fixed-term income stream, figures from the table in this guide (October 2026). A reasoning tool, not a price list. At 3% the 60-year figure is 83.0% and the 30-year figure 58.8%; at 5% they are 94.6% and 76.9%.
Two lessons follow. Decay speeds up, so the last 40 years of a lease carry most of the loss. Low yields make lease length matter more. The lower the return buyers demand, the more value sits in the distant years that a leasehold owner never gets.
Rental yields on Singapore homes are low against prices, which suggests buyers accept low returns. At 3%, even a fresh 99-year lease is worth about 5% less than freehold on paper. A lease, in other words, is a slow-burning candle that is priced as if it were a lamp.
Say a property earns S$36,000 a year in net rent, and you discount at 5%. As freehold it is worth S$720,000 (36,000 ÷ 0.05). With 30 years left, the same income is worth about S$553,400, or 77% of the freehold value.
Value, S$
Source: Worked example in this guide (October 2026). Freehold = S$36,000 / 0.05. The 30-year lease is about 77% of that.
Real prices also reflect location, condition and market mood, so use the table as a reasoning tool. For more on discounting, see our guide to NPV and MIRR.
Do HDB resale prices show lease decay?
Yes, and earlier than the maths suggests. We compared HDB resales from 2024 to September 2026 with flats that had 85 to 94 years left (our study of HDB resale data). The gap was 12% at 75 to 84 years left, 24% at 55 to 64 and 41% at 45 to 54.
Source: HDB resale flat prices, as at Sep 2026. Paler bars (95 or more, under 45) rest on few groups (9 and 14). Gaps are not a forecast for any one flat.
The biggest step comes between 55 to 64 years left and 45 to 54 years left. That is roughly where CPF and loan limits start to bite for younger buyers. To see how prices differ across estates of different ages, compare the HDB town pages, and see the HDB resale price charts for the island-wide trend.
Why do short leases sell for even less?
Older leases fall in value faster than pure discounting suggests, because rules cut the number of people who can buy them with CPF or a loan.
CPF. The CPF Board lets you use CPF in full only if the remaining lease covers the youngest buyer using CPF to age 95. If it does not, you can use only a percentage of the price or valuation. For example:
- A 40-year-old buys a home with 55 years left. 40 + 55 = 95, so full CPF use is allowed.
- A 35-year-old buys the same home. 35 + 55 = 90, so CPF use is pro-rated, and the buyer needs more cash.
Source: CPF Board, terms for use of CPF under the Housing Scheme, Table 1 (last updated 7 Sep 2026). CPF calls the table a rough guide. Darker means more CPF can be used.
Every year of lease you use up shrinks the pool of younger buyers who can pay with CPF. That pool is your future resale market. The rule and its history are on our rules page.
HDB loans. An HDB loan runs for the shortest of 25 years, 65 minus the buyers’ average age, or the remaining lease minus 20 years (rule history). A flat with 40 years left can carry at most a 20-year HDB loan, which pushes up the monthly instalment.
Bank loans. Banks set their own policies on short leases on top of MAS limits. Ask the bank before you sign. Model the instalment at different tenures with the Propwise mortgage calculator.
How do you value a leasehold home?
- Find the true remaining lease. Ask for the lease start date, or check it in a title search. The “TOP year” in a listing is the wrong date.
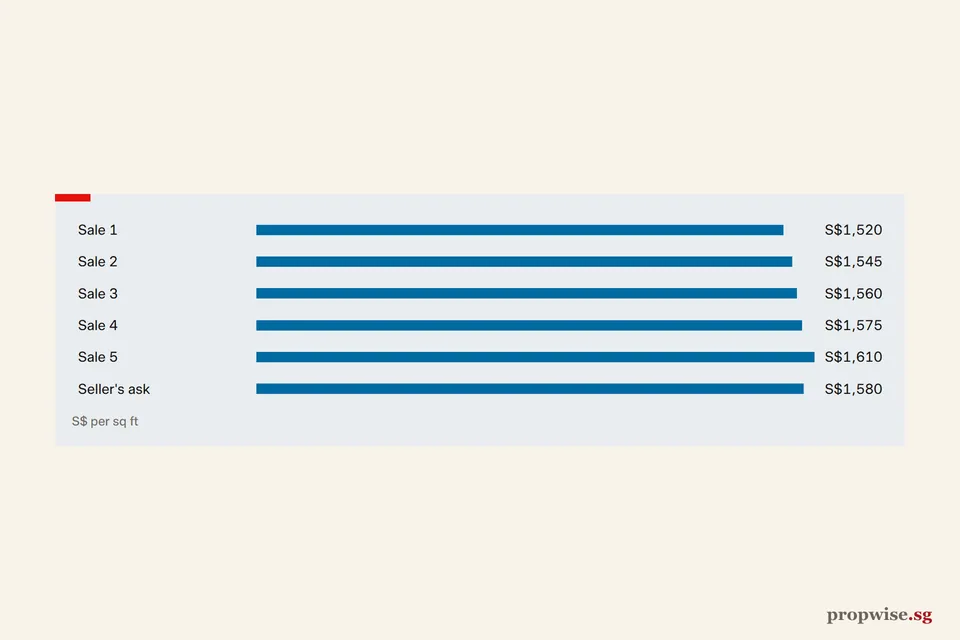
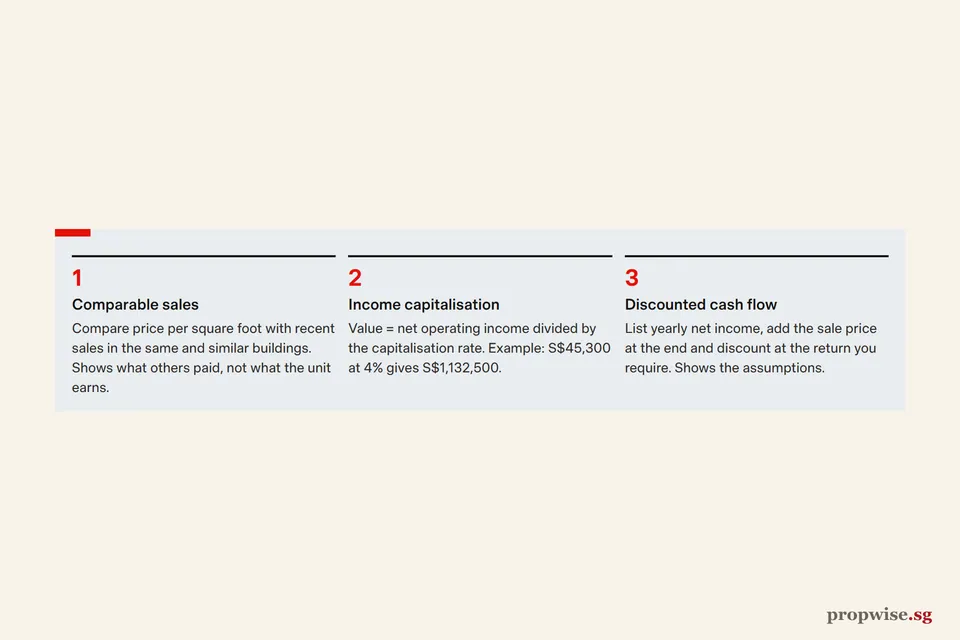
- Compare like with like. Use URA’s transaction search to compare prices per square foot nearby. Look at leasehold projects of similar age, newer leasehold projects and freehold projects. The gaps show how the local market prices lease decay.
- Value the lease at your exit. If you plan to sell in 15 years, a home with 70 years left today will have 55 left then. Will a 40-year-old buyer still be able to use full CPF? Will banks lend?
- Apply a discount rate you can defend. Use the table above, or your own figures, to test whether the asking price leaves room for decay.
- Count the running costs of age. Older estates may face rising maintenance fees and big repair bills paid from the sinking fund. Read the MCST’s accounts and minutes, and our checklist for buying into an older development.
- Set a walk-away price. Decide your maximum before you negotiate, and stick to it.
Can an en bloc sale rescue an old leasehold?
Sometimes. Many older leasehold condos trade on hopes of a collective sale. Treat that as a bonus, never the reason to buy.
Under current law, a collective sale needs owners holding 80% of share values and floor area in estates at least 10 years old, and 90% in younger ones. The Land Titles (Strata) (Amendment) Bill 2026 lowers this to 70% for estates aged 40 to 59 years, and 65% for estates aged 60 years or more.
Parliament passed the bill on 8 September 2026, after the second reading debate. The new thresholds apply from a commencement date that the Ministry of Law will announce. Until then, the 80% and 90% thresholds apply.
| Rule | Age of the estate | Owners needed (share values and floor area) |
|---|---|---|
| Current law | At least 10 years | 80% |
| Current law | Under 10 years | 90% |
| After the bill | 40 to 59 years | 70% |
| After the bill | 60 years or more | 65% |
Source: Ministry of Law, collective sale regime (2 October 2026); Parliament of Singapore, bills introduced. No commencement date had been announced as at 2 October 2026. Until then, the old thresholds apply. The bill also needs 35% of owners to sign before a sale begins, sets a six-month signing window (now 12) and a three-year cooling-off after a failed attempt.
The bill also makes a sale harder to start and quicker to close:
- 35% of owners must sign up before a sale can begin.
- Owners have a six-month window to sign, instead of 12 months.
- A failed attempt is followed by a three-year cooling-off period.
Lower thresholds may make old leasehold estates easier to sell en bloc. A sale still needs a developer who wants the site at a price owners accept. See our guide to en bloc sales for the process.
Who should buy leasehold, and who should buy freehold?
- Buying a home for life in your 50s or 60s? An older or shorter lease can make sense if the discount is large and the lease outlasts your own needs. Resale value matters less if you never plan to sell, but think about your heirs.
- Young buyer, or planning to sell? Lease decay and CPF rules work against you over time. Check how many years will be left at your likely exit.
- Investor? Rental yields on older leaseholds can look high. Check how much of that “yield” is your capital wasting away.
- Freehold? Pay the premium only if you will hold long enough to benefit, and if the location would hold value anyway. Freehold in a poor location is still a poor location, for ever.
Bottom line
Leasehold is a wasting asset, and the price should reflect how much of it is left. Value the lease you will have at your exit, and allow for the CPF age-95 rule and loan limits that thin out future buyers.
Treat en bloc as upside. If the asking price is close to freehold for a lease past its middle age, you are paying for years you will never own.