Is Property Still a Good Investment in Singapore in 2026?
Is property still a good investment in Singapore in 2026? The real returns, rental yields, ABSD and SSD costs, and a worked example of a second-property buy.
Property can still be a good investment in Singapore, but for most people it works far better as a home than as a second, leveraged investment. Prices have risen about 4.9% a year over the past decade, yet a citizen buying a second home pays 20% ABSD upfront, net rental yields are in the 2–3% range, and the 4-year Seller’s Stamp Duty locks your money in. Run the numbers before you believe anyone who says property “always” makes money.
At a glance
- Over the 10 years to Q3 2026, private home prices rose about 4.9% a year and HDB resale prices about 4.2% a year, or roughly 2.2–2.9% after inflation.
- A citizen’s second home costs 20% ABSD plus Buyer’s Stamp Duty. On a S$1.5m condo that is S$344,600, about 23% of the price.
- In our worked example the property must rise about 25% before you break even on sale. At 3% a year that takes almost 8 years.
- Net rental yields of about 2–2.5% beat today’s home-loan rates of about 1.5–2.2%, but not by much, and the spread turns negative if rates rise.
- The maths is far kinder to a first home with no ABSD, held for the long term.
What property has actually returned
Here are the annual price gains from the official URA private price index and HDB resale price index, set against consumer price inflation (to Q3 2026):
| Period | Private homes | HDB resale | Inflation |
|---|---|---|---|
| Last 10 years | 4.9% a year | 4.2% a year | 2.0% a year |
| Last 20 years | 4.7% a year | 5.1% a year | 2.2% a year |
| Last 30 years (from the 1996 peak) | 1.8% a year | 2.7% a year | 1.7% a year |
Three things to note. These are price changes only: rent adds to them, and costs and taxes take away. Leverage magnifies both gains and losses. And the starting point matters a lot: the 30-year buyer who started at the 1996 peak barely beat inflation. Our guide to whether prices always go up has the full history.
- Policy measures (select one for details)
Latest: Private 222.5 (Q3 2026), up 3.4% on Q3 2025.
The index is a market average, not the price of any single home. Marked policy measures are shown for context only.
Table view
| Period | Private homes (URA price index) |
|---|---|
| Q3 2026 | 222.5 |
| Q2 2026 | 219.4 |
| Q1 2026 | 218.3 |
| Q4 2025 | 216.4 |
| Q3 2025 | 215.1 |
| Q2 2025 | 213.2 |
| Q1 2025 | 211.1 |
| Q4 2024 | 209.4 |
| Q3 2024 | 204.7 |
| Q2 2024 | 206.1 |
| Q1 2024 | 204.3 |
| Q4 2023 | 201.5 |
| Q3 2023 | 196.0 |
| Q2 2023 | 194.4 |
| Q1 2023 | 194.8 |
| Q4 2022 | 188.6 |
| Q3 2022 | 187.8 |
| Q2 2022 | 180.9 |
| Q1 2022 | 174.8 |
| Q4 2021 | 173.6 |
| Q3 2021 | 165.3 |
| Q2 2021 | 163.5 |
| Q1 2021 | 162.2 |
| Q4 2020 | 157.0 |
| Q3 2020 | 153.8 |
| Q2 2020 | 152.6 |
| Q1 2020 | 152.1 |
| Q4 2019 | 153.6 |
| Q3 2019 | 152.8 |
| Q2 2019 | 150.8 |
| Q1 2019 | 148.6 |
| Q4 2018 | 149.6 |
| Q3 2018 | 149.7 |
| Q2 2018 | 149.0 |
| Q1 2018 | 144.1 |
| Q4 2017 | 138.7 |
| Q3 2017 | 137.6 |
| Q2 2017 | 136.6 |
| Q1 2017 | 136.7 |
| Q4 2016 | 137.2 |
| Q3 2016 | 137.9 |
| Q2 2016 | 140.0 |
| Q1 2016 | 140.6 |
| Q4 2015 | 141.6 |
| Q3 2015 | 142.3 |
| Q2 2015 | 144.2 |
| Q1 2015 | 145.5 |
| Q4 2014 | 147.0 |
| Q3 2014 | 148.6 |
| Q2 2014 | 149.7 |
| Q1 2014 | 151.3 |
| Q4 2013 | 153.2 |
| Q3 2013 | 154.6 |
| Q2 2013 | 154.0 |
| Q1 2013 | 152.4 |
| Q4 2012 | 151.5 |
| Q3 2012 | 148.8 |
| Q2 2012 | 147.9 |
| Q1 2012 | 147.2 |
| Q4 2011 | 147.4 |
| Q3 2011 | 147.0 |
| Q2 2011 | 145.1 |
| Q1 2011 | 142.3 |
| Q4 2010 | 139.2 |
| Q3 2010 | 135.5 |
| Q2 2010 | 131.7 |
| Q1 2010 | 125.1 |
| Q4 2009 | 118.4 |
| Q3 2009 | 110.3 |
| Q2 2009 | 95.3 |
| Q1 2009 | 100.0 |
| Q4 2008 | 116.4 |
| Q3 2008 | 123.9 |
| Q2 2008 | 126.9 |
| Q1 2008 | 126.7 |
| Q4 2007 | 122.1 |
| Q3 2007 | 114.4 |
| Q2 2007 | 105.6 |
| Q1 2007 | 97.6 |
| Q4 2006 | 93.1 |
| Q3 2006 | 89.6 |
| Q2 2006 | 87.3 |
| Q1 2006 | 85.8 |
| Q4 2005 | 84.5 |
| Q3 2005 | 83.3 |
| Q2 2005 | 82.3 |
| Q1 2005 | 81.9 |
| Q4 2004 | 81.3 |
| Q3 2004 | 80.7 |
| Q2 2004 | 80.4 |
| Q1 2004 | 80.3 |
| Q4 2003 | 80.6 |
| Q3 2003 | 80.7 |
| Q2 2003 | 81.1 |
| Q1 2003 | 81.6 |
| Q4 2002 | 82.3 |
| Q3 2002 | 82.6 |
| Q2 2002 | 82.2 |
| Q1 2002 | 82.8 |
| Q4 2001 | 83.8 |
| Q3 2001 | 87.6 |
| Q2 2001 | 90.3 |
| Q1 2001 | 91.1 |
| Q4 2000 | 94.9 |
| Q3 2000 | 97.6 |
| Q2 2000 | 100.4 |
| Q1 2000 | 98.9 |
| Q4 1999 | 95.9 |
| Q3 1999 | 91.1 |
| Q2 1999 | 84.3 |
| Q1 1999 | 75.4 |
| Q4 1998 | 71.5 |
| Q3 1998 | 78.3 |
| Q2 1998 | 90.1 |
| Q1 1998 | 98.3 |
| Q4 1997 | 108.4 |
| Q3 1997 | 113.0 |
| Q2 1997 | 118.2 |
| Q1 1997 | 119.2 |
| Q4 1996 | 123.7 |
| Q3 1996 | 127.2 |
| Q2 1996 | 129.7 |
| Q1 1996 | 122.3 |
| Q4 1995 | 117.9 |
| Q3 1995 | 112.7 |
| Q2 1995 | 111.1 |
| Q1 1995 | 109.8 |
| Q4 1994 | 106.9 |
| Q3 1994 | 104.5 |
| Q2 1994 | 93.6 |
| Q1 1994 | 82.1 |
| Q4 1993 | 75.1 |
| Q3 1993 | 71.1 |
| Q2 1993 | 64.9 |
| Q1 1993 | 58.3 |
| Q4 1992 | 55.3 |
| Q3 1992 | 53.8 |
| Q2 1992 | 51.8 |
| Q1 1992 | 49.9 |
| Q4 1991 | 47.6 |
| Q3 1991 | 46.8 |
| Q2 1991 | 45.6 |
| Q1 1991 | 42.1 |
| Q4 1990 | 40.3 |
| Q3 1990 | 42.0 |
| Q2 1990 | 41.8 |
| Q1 1990 | 40.9 |
Policy measures marked on this chart (26)
- 2025-07-03 Seller's Stamp Duty holding period back to four years, rates raised by 4 pp
- 2024-08-19 HDB loan LTV cut to 75% and Enhanced CPF Housing Grant raised
- 2023-04-26 ABSD rates raised, April 2023
- 2023-02-14 CPF Housing Grant raised for first-time resale buyers, Budget 2023
- 2023-02-14 Buyer's Stamp Duty raised for higher-value properties, Budget 2023
- 2022-09-29 Property measures, September 2022: higher TDSR and MSR rate floor, HDB loan LTV 80%, 15-month wait-out
- 2021-12-15 Property cooling measures, December 2021: higher ABSD, TDSR 55%, HDB loan LTV 85%
- 2018-07-05 Property cooling measures, July 2018: higher ABSD and lower LTV limits
- 2018-02-19 Budget 2018: Proximity Housing Grant enhanced
- 2018-02-19 Budget 2018: top BSD rate raised to 4% above S$1m
- 2017-03-10 SSD holding period cut to 3 years; TDSR relaxed for equity withdrawal
- 2013-08-27 HDB loan and resale measures, August 2013
- 2013-06-28 MAS introduces the Total Debt Servicing Ratio (TDSR) framework
- 2013-01-11 Property cooling measures, January 2013
- 2012-10-05 Maximum loan tenure of 35 years and tighter LTV limits, October 2012
- 2011-12-07 Additional Buyer's Stamp Duty introduced, December 2011
- 2011-01-13 Property cooling measures, January 2011
- 2010-08-30 HDB measures after National Day Rally 2010: DBSS income ceiling, 5-year MOP for non-subsidised flats
- 2010-08-30 Property cooling measures, August 2010
- 2010-02-19 Seller's Stamp Duty introduced and LTV limit cut to 80%, February 2010
- 2009-09-14 Interest-only loans and Interest Absorption Scheme disallowed, September 2009
- 2005-07-19 Property policy review, July 2005: LTV limit raised to 90%, CPF housing rules eased, foreign ownership rules eased
- 2001-10-12 Second off-budget package, October 2001: property tax rebate, stamp duty cut, gains tax removed, land sales eased
- 1998-06-29 Off-budget property measures, June 1998: land sales suspended, stamp duty deferred
- 1997-11-18 Property relief, November 1997: seller's stamp duty suspended, land sales deferred
- 1996-05-14 Anti-speculation measures, May 1996: seller's stamp duty, tax on short-term gains, 80% loan limit
Source: URA. Data to Q3 2026.
The cost wall: stamp duties and holding rules
The biggest change since this article was first written in 2015 is the cost of buying a second property. In 2015 a citizen paid 7% ABSD on a second home, and a foreigner 15%. Both went up in July 2018, again in December 2021 and again in April 2023. Today’s ABSD rates:
| Buyer | 1st property | 2nd | 3rd and later |
|---|---|---|---|
| Singapore Citizen | 0% | 20% | 30% |
| Singapore PR | 5% | 30% | 35% |
| Foreigner | 60% | 60% | 60% |
| Company or trust | 65% | 65% | 65% |
From the IRAS ABSD page and MAS (rates from 27 April 2023), as at 6 October 2026. Citizen rates only; other buyers pay more.
On top of that:
- Buyer’s Stamp Duty runs from 1% to 6%. It is S$44,600 on a S$1.5m home.
- Seller’s Stamp Duty of 16%, 12%, 8% or 4% applies if you sell within four years of buying (for purchases from 4 July 2025). Flipping is effectively over.
- Property tax on a home you do not live in starts at 12% of its annual value and rises to 36%.
- Loan limits: if you still have a housing loan, the bank can lend only 45% on the next one, and 25% must be cash.
As at 6 October 2026, using S$1,500,000 as the selling price. Rates: MAS, 3 July 2025 and the IRAS SSD page.
A warning on workarounds: arrangements whose main purpose is to cut ABSD, such as some “99-to-1” ownership splits, can be treated as tax avoidance. Whether a deal crosses the line depends on its facts, and IRAS can disregard the arrangement and add a 50% surcharge. By April 2024 it had reviewed 187 cases and found avoidance in 166, clawing back about S$60m.
Example: a S$1.5m condo as a second property
Say a married citizen couple who own their HDB flat outright buy a S$1.5m condo to rent out. These figures are an illustration. The rent, fees and growth rates are assumptions, not forecasts.
Upfront cash: a 25% downpayment of S$375,000 (part can come from CPF), BSD of S$44,600 and ABSD of S$300,000. Total: S$719,600, before legal fees.
S$
Source: IRAS, Additional Buyer's Stamp Duty (October 2026); IRAS, Buyer's Stamp Duty. Illustration. The 25% downpayment can be part CPF. The ABSD is the 20% second-home rate.
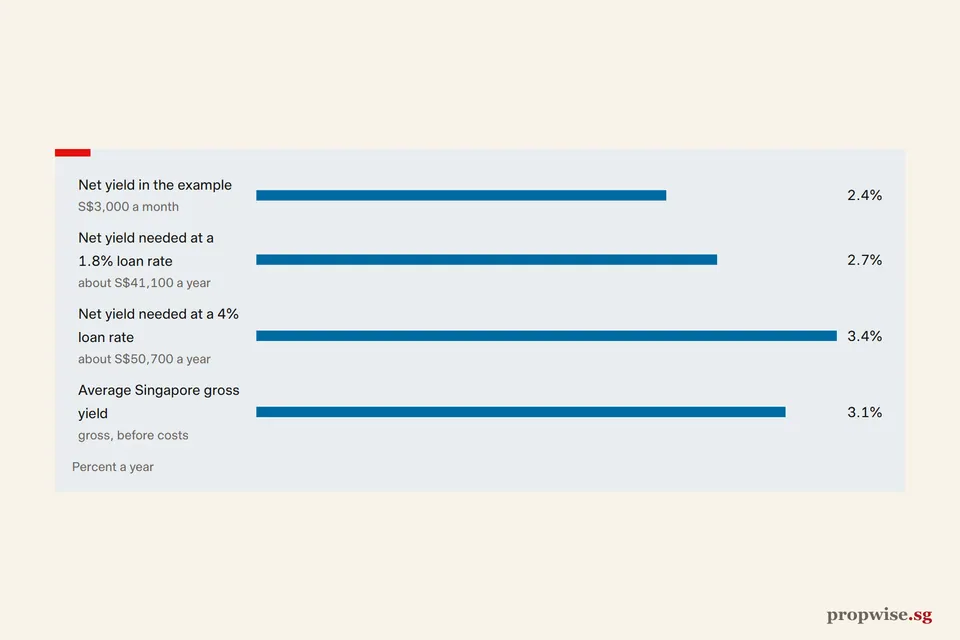
Running the property: at S$4,500 a month in rent, after non-owner-occupied property tax (S$9,120), maintenance (assumed S$4,800) and one month’s vacancy or agent fee, net rent is about S$35,580 a year, a 2.4% net yield. The S$1.125m loan at 1.75% (mid-range for floating packages after the September 2026 US rate hike, as reported by The Business Times and CNA) over 30 years costs S$4,019 a month, of which about S$19,460 is interest in year one. Rent minus interest leaves about S$16,100, a cash return of about 2.2% on the S$719,600 before income tax. (The instalment also repays principal, so you still top up about S$12,600 a year from your own pocket, but that part builds equity.)
Selling after five years, paying an assumed 2% agent fee:
| Price growth a year | Sale price | Result after duties, fee and five years of net rent | Same deal with 0% ABSD |
|---|---|---|---|
| 0% | S$1.50m | about −S$289,000 | about +S$11,000 |
| 3% | S$1.74m | about −S$55,000 | about +S$245,000 |
| 4.6% (the 10-year average to Q2 2026) | S$1.88m | about +S$82,000 | about +S$382,000 |
The lesson: the ABSD alone decides whether the deal works. To break even on the sale, the price must reach about S$1.88m, a 25.5% rise. That takes about 5 years at 4.6% a year and almost 8 years at 3% a year. Even in the good case, S$82,000 on S$719,600 over five years is about 2.3% a year, less than the CPF Ordinary Account pays (2.5%) with no risk. If interest rates rise to 3.5%, the rental income no longer covers the interest. See how interest rates affect property.
% a year
Source: CPF Board, CPF interest rates (October 2026). An illustration with assumed rent, costs and growth. Rental figures are before income tax. The sale case assumes 4.6% price growth a year for five years.
To test a deal of your own, use our guide to calculating property ROI and the mortgage calculator.
When property still makes sense
- Your own home. A first home carries no ABSD for citizens, replaces rent you would pay anyway, and forces you to save. That is where most Singaporeans have built wealth.
- A long holding period. Past downturns took 2 to 14 years to recover. If you can hold for 10 years or more without being forced to sell, short-term swings matter less.
- Buying below the market. Gains made at purchase, by paying less than recent transactions for a sound unit, are the only ones you control.
- Upgrading, not accumulating. Married couples can buy the next home first and get the ABSD refunded if they sell the old one within six months. That is a home move.
If you want property exposure without ABSD, large sums and illiquidity, REITs are the obvious comparison. See REITs or physical property and stocks or property.
A checklist before you buy to invest
- Does the net yield beat your loan rate at 4%? If not, you are betting only on price growth.
- Can you hold for at least four years, and ideally 10, through a downturn?
- Do you have a cash buffer for 6 to 12 months of instalments and vacancy?
- Have you counted every cost: ABSD, BSD, legal fees, property tax, maintenance, agent fees and income tax on rent?
- Is the “growth story” already in the price? New MRT lines and master plans are public. Sellers and developers price them in early.
- Who benefits from your purchase? Developers, agents and seminar trainers earn money when you buy, whatever happens to prices afterwards.
Bottom line
The game has changed for property in Singapore. With 20% to 60% ABSD, a 4-year SSD and modest yields, a second property bought as an investment needs strong price growth just to beat a CPF account. Property still works best as a home you can afford, hold for the long term and would be happy to live in if prices go nowhere. For our view of where prices are heading, see the Singapore property market outlook.