Stocks or property: which builds wealth faster in Singapore? (2026)
Stocks vs property in Singapore, 2026: 20 years of URA and STI data, what leverage really does, how ABSD changes the maths, and how to decide for yourself.
Neither asset is “easier” in Singapore. Over the last 20 years, private home prices and the Straits Times Index (STI) grew at broadly similar rates before income. What decides your result is how much you borrow, what you pay to get in and out, and whether you can hold through a bad patch. For a Singaporean who already owns a home, the 20% Additional Buyer’s Stamp Duty (ABSD) on a second property now tilts the maths hard.
At a glance
- From Q2 2006 to Q2 2026, URA’s private home price index rose about 4.7% a year. The STI rose about 3.8% a year on price alone, before dividends.
- Over the last 10 years the order flips: property about 4.6% a year, the STI about 6.2% a year on price alone. Your start date changes the answer.
- Property gives you leverage of up to 75% on a first loan. That magnifies gains and losses on your cash.
- A Singapore citizen buying a second home pays 20% ABSD, and the loan limit falls to 45%. On a S$1.2m condo, stamp duties alone come to about 23% of the price.
- Stocks cost little to buy, sell in seconds and can be bought in small amounts. Property is lumpy and illiquid, and its rent is taxable income.
What 20 years of data actually show
Here are the two benchmarks, side by side. Property is URA’s private residential price index (all residential, Q1 2009 = 100). Stocks are the STI’s month-end closes at the end of each June.
| Period | URA private home prices | STI (price only) |
|---|---|---|
| Q2 2006 to Q2 2026 (20 years) | 87.3 → 219.4, about 4.7% a year | 2,435 → 5,171, about 3.8% a year |
| Q2 2016 to Q2 2026 (10 years) | 140.0 → 219.4, about 4.6% a year | 2,841 → 5,171, about 6.2% a year |
| Worst fall in these records | −45% (Q2 1996 to Q4 1998) | −58% (Oct 2007 to Feb 2009, month-end closes) |
% a year
Source: URA private residential price index (data.gov.sg) (Q2 2026); STI month-end closes (TradingView) (June 2026). Propwise calculation. Neither is a total return; costs and tax are left out.
Two caveats matter more than the headline figures.
First, neither column is a total return. The STI figures leave out dividends; the SPDR STI ETF showed a trailing yield of about 3.1% in early October 2026. The property figures leave out rent, and also leave out stamp duty, property tax, maintenance and agent fees.
Second, start dates make or break the comparison. A buyer at the 1996 property peak waited until 2010 for the index to pass its old high. A buyer at the 2013 peak saw prices fall 11.6% by mid-2017. Stocks have equally ugly windows. “Property always goes up if you hold 10 years” is not something the data support.
- Policy measures (select one for details)
Latest: Private 219.4 (Q2 2026).
The index is a market average, not the price of any single home. Marked policy measures are shown for context only.
Table view
| Period | Private homes (URA price index) |
|---|---|
| Q2 2026 | 219.4 |
| Q1 2026 | 218.3 |
| Q4 2025 | 216.4 |
| Q3 2025 | 215.1 |
| Q2 2025 | 213.2 |
| Q1 2025 | 211.1 |
| Q4 2024 | 209.4 |
| Q3 2024 | 204.7 |
| Q2 2024 | 206.1 |
| Q1 2024 | 204.3 |
| Q4 2023 | 201.5 |
| Q3 2023 | 196.0 |
| Q2 2023 | 194.4 |
| Q1 2023 | 194.8 |
| Q4 2022 | 188.6 |
| Q3 2022 | 187.8 |
| Q2 2022 | 180.9 |
| Q1 2022 | 174.8 |
| Q4 2021 | 173.6 |
| Q3 2021 | 165.3 |
| Q2 2021 | 163.5 |
| Q1 2021 | 162.2 |
| Q4 2020 | 157.0 |
| Q3 2020 | 153.8 |
| Q2 2020 | 152.6 |
| Q1 2020 | 152.1 |
| Q4 2019 | 153.6 |
| Q3 2019 | 152.8 |
| Q2 2019 | 150.8 |
| Q1 2019 | 148.6 |
| Q4 2018 | 149.6 |
| Q3 2018 | 149.7 |
| Q2 2018 | 149.0 |
| Q1 2018 | 144.1 |
| Q4 2017 | 138.7 |
| Q3 2017 | 137.6 |
| Q2 2017 | 136.6 |
| Q1 2017 | 136.7 |
| Q4 2016 | 137.2 |
| Q3 2016 | 137.9 |
| Q2 2016 | 140.0 |
| Q1 2016 | 140.6 |
| Q4 2015 | 141.6 |
| Q3 2015 | 142.3 |
| Q2 2015 | 144.2 |
| Q1 2015 | 145.5 |
| Q4 2014 | 147.0 |
| Q3 2014 | 148.6 |
| Q2 2014 | 149.7 |
| Q1 2014 | 151.3 |
| Q4 2013 | 153.2 |
| Q3 2013 | 154.6 |
| Q2 2013 | 154.0 |
| Q1 2013 | 152.4 |
| Q4 2012 | 151.5 |
| Q3 2012 | 148.8 |
| Q2 2012 | 147.9 |
| Q1 2012 | 147.2 |
| Q4 2011 | 147.4 |
| Q3 2011 | 147.0 |
| Q2 2011 | 145.1 |
| Q1 2011 | 142.3 |
| Q4 2010 | 139.2 |
| Q3 2010 | 135.5 |
| Q2 2010 | 131.7 |
| Q1 2010 | 125.1 |
| Q4 2009 | 118.4 |
| Q3 2009 | 110.3 |
| Q2 2009 | 95.3 |
| Q1 2009 | 100.0 |
| Q4 2008 | 116.4 |
| Q3 2008 | 123.9 |
| Q2 2008 | 126.9 |
| Q1 2008 | 126.7 |
| Q4 2007 | 122.1 |
| Q3 2007 | 114.4 |
| Q2 2007 | 105.6 |
| Q1 2007 | 97.6 |
| Q4 2006 | 93.1 |
| Q3 2006 | 89.6 |
| Q2 2006 | 87.3 |
| Q1 2006 | 85.8 |
| Q4 2005 | 84.5 |
| Q3 2005 | 83.3 |
| Q2 2005 | 82.3 |
| Q1 2005 | 81.9 |
| Q4 2004 | 81.3 |
| Q3 2004 | 80.7 |
| Q2 2004 | 80.4 |
| Q1 2004 | 80.3 |
| Q4 2003 | 80.6 |
| Q3 2003 | 80.7 |
| Q2 2003 | 81.1 |
| Q1 2003 | 81.6 |
| Q4 2002 | 82.3 |
| Q3 2002 | 82.6 |
| Q2 2002 | 82.2 |
| Q1 2002 | 82.8 |
| Q4 2001 | 83.8 |
| Q3 2001 | 87.6 |
| Q2 2001 | 90.3 |
| Q1 2001 | 91.1 |
| Q4 2000 | 94.9 |
| Q3 2000 | 97.6 |
| Q2 2000 | 100.4 |
| Q1 2000 | 98.9 |
| Q4 1999 | 95.9 |
| Q3 1999 | 91.1 |
| Q2 1999 | 84.3 |
| Q1 1999 | 75.4 |
| Q4 1998 | 71.5 |
| Q3 1998 | 78.3 |
| Q2 1998 | 90.1 |
| Q1 1998 | 98.3 |
| Q4 1997 | 108.4 |
| Q3 1997 | 113.0 |
| Q2 1997 | 118.2 |
| Q1 1997 | 119.2 |
| Q4 1996 | 123.7 |
| Q3 1996 | 127.2 |
| Q2 1996 | 129.7 |
| Q1 1996 | 122.3 |
| Q4 1995 | 117.9 |
| Q3 1995 | 112.7 |
| Q2 1995 | 111.1 |
| Q1 1995 | 109.8 |
| Q4 1994 | 106.9 |
| Q3 1994 | 104.5 |
| Q2 1994 | 93.6 |
| Q1 1994 | 82.1 |
| Q4 1993 | 75.1 |
| Q3 1993 | 71.1 |
| Q2 1993 | 64.9 |
| Q1 1993 | 58.3 |
| Q4 1992 | 55.3 |
| Q3 1992 | 53.8 |
| Q2 1992 | 51.8 |
| Q1 1992 | 49.9 |
| Q4 1991 | 47.6 |
| Q3 1991 | 46.8 |
| Q2 1991 | 45.6 |
| Q1 1991 | 42.1 |
| Q4 1990 | 40.3 |
| Q3 1990 | 42.0 |
| Q2 1990 | 41.8 |
| Q1 1990 | 40.9 |
Policy measures marked on this chart (26)
- 2025-07-03 Seller's Stamp Duty holding period back to four years, rates raised by 4 pp
- 2024-08-19 HDB loan LTV cut to 75% and Enhanced CPF Housing Grant raised
- 2023-04-26 ABSD rates raised, April 2023
- 2023-02-14 CPF Housing Grant raised for first-time resale buyers, Budget 2023
- 2023-02-14 Buyer's Stamp Duty raised for higher-value properties, Budget 2023
- 2022-09-29 Property measures, September 2022: higher TDSR and MSR rate floor, HDB loan LTV 80%, 15-month wait-out
- 2021-12-15 Property cooling measures, December 2021: higher ABSD, TDSR 55%, HDB loan LTV 85%
- 2018-07-05 Property cooling measures, July 2018: higher ABSD and lower LTV limits
- 2018-02-19 Budget 2018: Proximity Housing Grant enhanced
- 2018-02-19 Budget 2018: top BSD rate raised to 4% above S$1m
- 2017-03-10 SSD holding period cut to 3 years; TDSR relaxed for equity withdrawal
- 2013-08-27 HDB loan and resale measures, August 2013
- 2013-06-28 MAS introduces the Total Debt Servicing Ratio (TDSR) framework
- 2013-01-11 Property cooling measures, January 2013
- 2012-10-05 Maximum loan tenure of 35 years and tighter LTV limits, October 2012
- 2011-12-07 Additional Buyer's Stamp Duty introduced, December 2011
- 2011-01-13 Property cooling measures, January 2011
- 2010-08-30 HDB measures after National Day Rally 2010: DBSS income ceiling, 5-year MOP for non-subsidised flats
- 2010-08-30 Property cooling measures, August 2010
- 2010-02-19 Seller's Stamp Duty introduced and LTV limit cut to 80%, February 2010
- 2009-09-14 Interest-only loans and Interest Absorption Scheme disallowed, September 2009
- 2005-07-19 Property policy review, July 2005: LTV limit raised to 90%, CPF housing rules eased, foreign ownership rules eased
- 2001-10-12 Second off-budget package, October 2001: property tax rebate, stamp duty cut, gains tax removed, land sales eased
- 1998-06-29 Off-budget property measures, June 1998: land sales suspended, stamp duty deferred
- 1997-11-18 Property relief, November 1997: seller's stamp duty suspended, land sales deferred
- 1996-05-14 Anti-speculation measures, May 1996: seller's stamp duty, tax on short-term gains, 80% loan limit
Private home prices are still rising. URA’s figure for Q3 2026 (flash estimate) was +1.4% q/q.
Leverage: the real reason property feels like it wins
Most people never buy stocks with borrowed money, but almost everyone buys property that way. That is the main reason property “made more money” for the people you know.
For a first housing loan, MAS caps the loan-to-value ratio at 75%. Put down 25%, and a 10% rise in price is a 40% gain on your cash before costs. A 10% fall is a 40% loss of that cash. And the loan still has to be repaid in full.
Leverage also has rules that stocks do not:
- Debt limits. Under the Total Debt Servicing Ratio, all your monthly debt repayments may not exceed 55% of gross income. Banks test this at a 4% interest rate, even though packages cost about 1.5–1.8% floating and 2.0–2.2% fixed in late September 2026 (The Business Times, 2 Oct 2026).
- No daily margin call. A margin loan on shares can be called the week prices drop. A home loan generally keeps running while you pay the instalments. But a price fall still bites when you refinance or have to sell.
- Rates move. Singapore home loans now track SORA or are fixed for a short period. Compounded 3-month SORA was around 1.24% on 14 Oct 2026, down from a peak of about 3.7–3.8% in late 2023. A borrower who sized a loan at today’s rate can see the instalment jump sharply within a few years.
- 3-month compounded SORA (Singapore)
- US federal funds rate (effective)
Latest: SORA 1.24% (14 Oct 2026); Fed 3.88% (13 Oct 2026).
SORA is the benchmark for floating-rate home loans in Singapore. The US rate is shown for context: it moves SORA only indirectly, through the Singapore dollar and bank funding costs.
Table view
| Period | 3-month compounded SORA (Singapore) | US federal funds rate (effective) |
|---|---|---|
| Oct 2026 | 1.24% | 3.88% |
| Sep 2026 | 1.23% | 3.88% |
| Aug 2026 | 1.18% | 3.63% |
| Jul 2026 | 1.14% | 3.63% |
| Jun 2026 | 1.08% | 3.63% |
| May 2026 | 1.06% | 3.62% |
| Apr 2026 | 1.03% | 3.64% |
| Mar 2026 | 1.07% | 3.64% |
| Feb 2026 | 1.12% | 3.64% |
| Jan 2026 | 1.15% | 3.64% |
| Dec 2025 | 1.19% | 3.64% |
| Nov 2025 | 1.25% | 3.89% |
| Oct 2025 | 1.32% | 4.11% |
| Sep 2025 | 1.46% | 4.09% |
| Aug 2025 | 1.56% | 4.33% |
| Jul 2025 | 1.86% | 4.33% |
| Jun 2025 | 2.06% | 4.33% |
| May 2025 | 2.27% | 4.33% |
| Apr 2025 | 2.40% | 4.33% |
| Mar 2025 | 2.55% | 4.33% |
| Feb 2025 | 2.73% | 4.33% |
| Jan 2025 | 2.90% | 4.33% |
| Dec 2024 | 3.08% | 4.33% |
| Nov 2024 | 3.21% | 4.58% |
| Oct 2024 | 3.39% | 4.83% |
| Sep 2024 | 3.49% | 4.83% |
| Aug 2024 | 3.57% | 5.33% |
| Jul 2024 | 3.64% | 5.33% |
| Jun 2024 | 3.63% | 5.33% |
| May 2024 | 3.66% | 5.33% |
| Apr 2024 | 3.65% | 5.33% |
| Mar 2024 | 3.68% | 5.33% |
| Feb 2024 | 3.64% | 5.33% |
| Jan 2024 | 3.66% | 5.33% |
| Dec 2023 | 3.70% | 5.33% |
| Nov 2023 | 3.75% | 5.33% |
| Oct 2023 | 3.75% | 5.33% |
| Sep 2023 | 3.70% | 5.33% |
| Aug 2023 | 3.70% | 5.33% |
| Jul 2023 | 3.68% | 5.33% |
| Jun 2023 | 3.65% | 5.07% |
| May 2023 | 3.61% | 5.08% |
| Apr 2023 | 3.61% | 4.83% |
| Mar 2023 | 3.58% | 4.83% |
| Feb 2023 | 3.23% | 4.58% |
| Jan 2023 | 3.12% | 4.33% |
| Dec 2022 | 3.03% | 4.33% |
| Nov 2022 | 2.87% | 3.83% |
| Oct 2022 | 2.45% | 3.08% |
| Sep 2022 | 2.07% | 3.08% |
| Aug 2022 | 1.55% | 2.33% |
| Jul 2022 | 1.27% | 2.32% |
| Jun 2022 | 0.72% | 1.58% |
| May 2022 | 0.52% | 0.83% |
| Apr 2022 | 0.32% | 0.33% |
| Mar 2022 | 0.27% | 0.33% |
| Feb 2022 | 0.25% | 0.08% |
| Jan 2022 | 0.20% | 0.08% |
| Dec 2021 | 0.19% | 0.08% |
| Nov 2021 | 0.16% | 0.08% |
| Oct 2021 | 0.16% | 0.07% |
| Sep 2021 | 0.13% | 0.08% |
| Aug 2021 | 0.13% | 0.08% |
| Jul 2021 | 0.13% | 0.10% |
| Jun 2021 | 0.14% | 0.10% |
| May 2021 | 0.17% | 0.05% |
| Apr 2021 | 0.19% | 0.07% |
| Mar 2021 | 0.23% | 0.07% |
| Feb 2021 | 0.20% | 0.07% |
| Jan 2021 | 0.17% | 0.07% |
| Dec 2020 | 0.17% | 0.09% |
| Nov 2020 | 0.12% | 0.08% |
| Oct 2020 | 0.12% | 0.09% |
| Sep 2020 | 0.10% | 0.09% |
| Aug 2020 | 0.10% | 0.09% |
| Jul 2020 | 0.08% | 0.09% |
| Jun 2020 | 0.14% | 0.08% |
| May 2020 | 0.27% | 0.05% |
| Apr 2020 | 0.53% | 0.05% |
| Mar 2020 | 0.90% | 0.10% |
| Feb 2020 | 1.14% | 1.58% |
| Jan 2020 | 1.20% | 1.55% |
| Dec 2019 | 1.27% | 1.55% |
| Nov 2019 | 1.31% | 1.55% |
| Oct 2019 | 1.46% | 1.83% |
| Sep 2019 | 1.53% | 1.83% |
| Aug 2019 | 1.59% | 2.12% |
| Jul 2019 | 1.67% | 2.40% |
| Jun 2019 | 1.72% | 2.40% |
| May 2019 | 1.68% | 2.38% |
| Apr 2019 | 1.62% | 2.44% |
| Mar 2019 | 1.54% | 2.43% |
| Feb 2019 | 1.59% | 2.40% |
| Jan 2019 | 1.52% | 2.40% |
You can model your own instalment at different rates with the Propwise mortgage calculator.
The cost of getting in and out
This is where the 2011 version of this article has aged most. Stocks cost a brokerage fee of a fraction of a percent. Property in 2026 costs this:
- Buyer’s Stamp Duty (BSD) of 1% to 6% in tiers (IRAS). On S$1.2m it is S$32,600.
- ABSD (IRAS): 0% on a citizen’s first home, 20% on the second and 30% on the third. Permanent residents pay 5%, 30% and 35%. Foreigners pay 60%.
- Seller’s Stamp Duty (SSD) if you sell a home bought from 4 July 2025 within four years: 16%, 12%, 8% or 4% of the price.
- Property tax on a home you rent out starts at 12% of annual value and rises to 36% (IRAS rates).
| Buyer | 1st home | 2nd home | 3rd home and later |
|---|---|---|---|
| Singapore citizen | 0% | 20% | 30% |
| Singapore permanent resident | 5% | 30% | 35% |
| Foreigner | 60% on every purchase | ||
| Entity (company, partnership and similar) | 65% | ||
| Trust | 65% | ||
| Housing developer | 40% (35% can be remitted if the project is completed and sold in time) | ||
When the first version of this article appeared in early 2011, Singapore had no ABSD at all. A citizen’s second home now attracts 20%. That single change is the biggest reason the old “buy a second property and let the tenant pay the loan” advice no longer works as a default.
A worked example: a second property vs an index fund
Say you are a Singapore citizen who already owns your home, with no other housing loan. You are deciding between a S$1.2m resale condo to rent out and putting the same cash into an STI index fund. All figures are illustrative.
Upfront cash for the condo
| Item | Amount |
|---|---|
| Down payment (45% LTV, so the loan is S$540,000) | S$660,000 |
| BSD | S$32,600 |
| ABSD at 20% | S$240,000 |
| Total, before legal and valuation fees | S$932,600 |
S$
Source: IRAS, Additional Buyer's Stamp Duty (October 2026); IRAS, Buyer's Stamp Duty. Total S$932,600 before legal and valuation fees. Stamp duties alone are S$272,600.
Year-one income from the condo (assumed rent S$3,500 a month)
| Item | Amount |
|---|---|
| Gross rent | S$42,000 |
| Property tax (assume annual value of S$42,000, non-owner-occupied rates) | −S$6,000 |
| Maintenance fees (assume S$400 a month) | −S$4,800 |
| Interest on S$540,000 at about 1.5% | −S$8,100 |
| One month’s rent for vacancy and agent fees | −S$3,500 |
| Net, before income tax | S$19,600 |
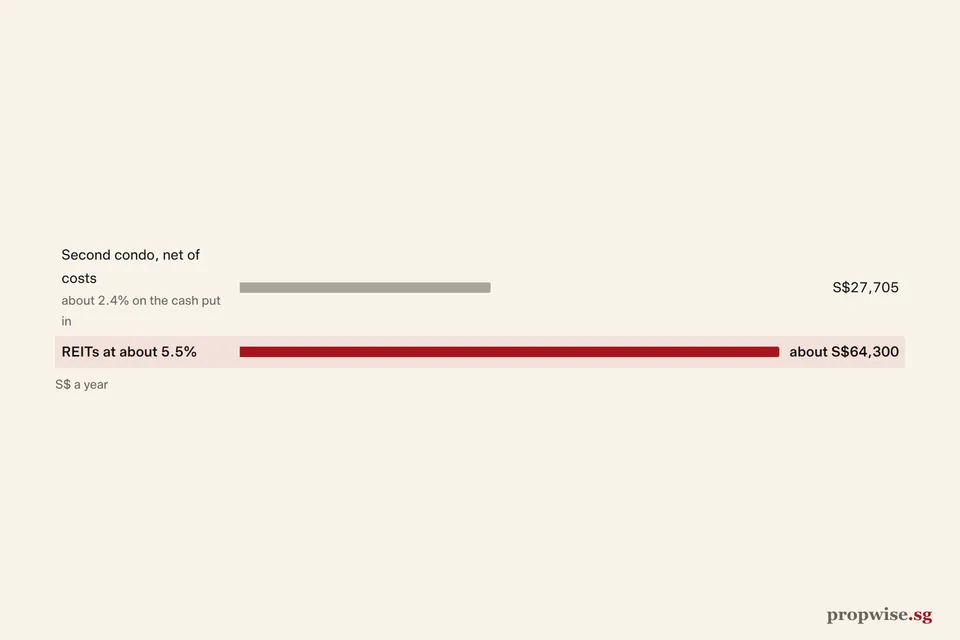
That is about 2.1% on the S$932,600 you put in. The rest of your return has to come from price growth. If the condo rises 4.6% a year, in line with the last decade, that adds about S$55,000 in year one. If prices go flat, it adds nothing, and the S$272,600 you paid in stamp duty is a sunk cost. At 4.6% a year, it takes about four and a half years of price growth just to earn back the stamp duty.
The same S$932,600 in an STI fund at a 3.1% yield pays about S$28,900 a year in dividends. You need no tenant, pay no stamp duty, and can sell part of it any day. Its price can also fall 30% to 50% in a crash, as it has before. And you have no leverage to boost the upside.
% of S$932,600 put in
Source: SPDR STI ETF trailing yield (TradingView) (early October 2026). Condo: assumed rent S$3,500 a month, net S$19,600 before income tax (about 2.1%); price growth not included. Fund: S$28,900 a year at a 3.1% yield, before any fall in price. Both illustrative.
Neither answer is “right”. The example shows that for a second property, the hurdle is now high. The deal works only if you are confident of solid price growth over a long hold, and you can carry the loan if the rent stops.
Where the old arguments still hold, and where they don’t
The 2011 version of this article made five claims for property. Here is how they stand in 2026:
- “Banks lend more against property.” Still true for a first loan (75%). It is far less true for a second (45%) or third (35%), and not true for buyers who borrow through a company (15%).
- “You can’t lose everything in property.” A home rarely goes to zero, but your equity can. Leasehold homes also lose value as the lease runs down. Single stocks can go to zero; a broad index fund is a different risk.
- “You can buy property below market value.” Sometimes, from motivated sellers. URA’s transaction search makes prices far more transparent than in 2011, so true bargains are rarer.
- “You can add value.” Yes, through renovation, layout fixes and good tenant management. This is real work, not passive income.
- “The tenant pays your loan.” In the example above, rent covers the interest easily at 2026 rates. Whether it would at 3.5% interest, after ABSD, is the real question.
How to decide what fits you
- Start with your home. For most Singaporeans, the first property is a home, not an investment, and it carries no ABSD. Get that decision right before you compare investments.
- Count the full cost. Compare after stamp duties, tax and fees, not headline price growth against headline index levels.
- Match the asset to your time frame. With SSD, property money is locked up for at least four years. Stocks suit money you may need sooner, but only if you can live with sharp drops.
- Stress-test your income. Ask what happens if you lose your job for six months, or rates double. Leverage is what turns a dip into a forced sale.
- Consider the middle ground. REITs give property income without ABSD, lumpiness or tenants. See our guide to investing in Singapore REITs.
If you go the property route, read our list of common property investment mistakes first.
Bottom line
Over 20 years, Singapore private property and the STI grew at similar single-digit rates before income. Property won for many households because of leverage and forced saving, not because bricks are magic. In 2026, ABSD, SSD and the 4% stress test make a second property a heavy, long-term bet. That bet can still pay off. But run the numbers for your own situation, including the bad scenarios, before you choose. Nothing here is personal financial advice.
13 reader comments
The Journalist
I personally feel that many of the points in this article is bias towards property which could give readers some wrong perspective. Therefore I’ll try to reply with one that is bias towards stocks.
1. Property gives more leverage than stocks.
Not entirely true. There are brokerages that allows up to 5 times leverage when you purchase certain stocks using the margin accounts, depending on the riskiness of the counters you purchase. It is also not always true that you can get 80% financing for your property. This is dependent on the valuation of the property, your credit rating, as well as government/bank policies.The calculation of margin call isn’t accurate. There is usually an initial margin and maintenance margin level to be kept. In real estate, should a property bubble bursting occur, believe you me, the banks will come and bother you. In stocks the margin call limits your downside, but in real estate, if property prices collapse and you are unable to service your monthly installments, you can lose alot more.
2.You may lose everything in stock investing
This is true. A listed company can file for bankruptcy and you may lose everything in your stock. The value of a property never drops to zero, but as I’ve pointed out previously, it is possible to lose everything in property investing as well. Just think negative sale.3.You can pay lower than market price to buy a house
Totally untrue. In the stock market, with a well regulated and controlled exchange, the price of a stock is the end result of supply and demand, meaning to say it will be transacted ONLY at market price. You can’t pay less but you surely cannot pay a single cent more as well. If the price of a stock is $1, you can still queue to buy at $0.90. Because the stock market is liquid and “live”, a $0.90 price can possibly be hit. The only difference is, if you manage to get it at $0.90, you’re still buying it at market price. The same reason of “some owners selling property 10% lower than market value” is the same reason why a $1.00 can drop to $0.90.The “market value” of a property is hard to measure which is why there is no way to measure if it is 10% lower or 10% higher. The “value” of a property can depend on many factors such as, past transacted prices, the condition, the facing, the floor, the age, the valuation (which can be inflated), the asking price, amenities, facilities, location etc etc. Nobody can put an exact figure on a value of a property, and this is why a stock market actually protects investors from overpaying.
4. You can enhance the value of the property
At a cost which does not necessarily translate to an equal increase in the value of your house.5. You can let others help you pay for your property
This is possible only when price of property is low and rental yield is high. As of current moment, the price of property in Singapore is at a rate that makes it very difficult to do this. In an ideal world, this concept is lovely, but in a practical world, there are many risks involved.Let’s look at the example given, $1mil property with a 70% loan for a period of 25 years at 3% interest rate. The monthly repayment should actually by more than $3000, approximately $3,300, not $2,655. If you can rent if out for $3,000 you will not be able to cover the instalment. If you can rent if out for $3,500, you might still not be able to cover. Why? $3,500 rental includes your monthly maintenance fees. An average monthly maintenance fee in Singapore is about $250-300 per month, meaning you only pocketed about $3,250. You will need to pay property tax every year and for such a property, we can estimate the property tax to about $2,500 per year. That makes your net profit from rental merely $3,042. On top of this, you can expect your property to be tenanted 100% of the time. There will be period where you’re advertising for new tenants, or period where you’re renovating your house. You still have to pay your installments during these no income period. Money is also spend on renovating/cleaning/repainting etc everytime an old tenant vacates. Conclusion is, it is almost impossible to let others pay for your property in current times as how you’ve mentioned.
I do however agree with your final points that there are times when one form of investment is better than the other. With all due respect, I’m writing such a comment only to let your readers see the other side of the coin.
Mr. Propwise
Hi Journalist,
Thanks for your comments. They are well argued. Here are my responses:
1. On leverage, I think for the majority of people they will still be able to get more leverage with a property.
As for “margin calls”, it is unlikely for the bank to ask for a top up unless prices fall more than 30%. If you are 5x leveraged on stocks, your margin call will DEFINITELY come much earlier.
2. It is true that you can lose all your equity in a property investment and more. But as long as you can hold on and you don’t get asked for a top up by the bank, your property is very likely to recover in the long term (unlike a company that has gone bust).
3. Your point has really to do with the transparency and level of information in the market. Property is an opaque and imperfect market as there aren’t “live” prices like stocks. That’s where the opportunity is.
4. It’s up to you to evaluate if the cost of the enhancements will add even greater value to the property. If not, you can choose not to do it.
5. Yes of course it doesn’t apply for all properties. The smart property investor will look for a property that has a high enough rental yield to get positive cash flow (among various investment strategies).
Thanks for your comment!
Jeffrey Ong
The post is extremely biased. It’s obvious that Mr Propwise wants readers to invest in properties. If you buy an Emerging Market mutual fund or ETF, the returns are 18% per annum in the last 15 years. If you invest in Singapore residential properties, the returns are only 6% per annum. If you leverage 80%, the returns increase to around 15%, still lower than emerging markets ETF. If you buy any emerging market fund or ETF, e.g. Latin America, Indonesia, Russia, BRIC, CHina etc, the returns are around 18-20% per annum.
I am an investor of both properties and stocks for the last 15 years and I can tell you there are several advantages stocks have over properties.
1. Stocks are more liquid than properties. If the market turn for the worse, I can exit my stocks or unit trust portfolio almost immediately. For properties, it takes around 3 months to even 6 to find a willing buyer. Sometimes, you can’t even find a buyer in turbulent times.
2. If you buy an ETF or mutual fund, it comprises more than 50 stocks so the chances of going zero is virtually zero.
3. In a bearish market or recesssion, you can short sell stocks and make 20 – 50% in a year, whereas you cannot short the physical property market.
4. Transaction cost of property is around 2 – 3%, including legal, agent, stamp fees. Stocks cost less than 1%.
5. If the Singapore property market falls, you can’t easily move your investments overseas unless you do a lot of research. You can always diversify to overseas stocks easily. Just pick up the phone to call your dealer, log into your internet trading account or call your relationship manager to buy an emerging market fund.
Mr. Propwise
Hi Jeffrey,
Thanks for your comments. You make some good points. I’d just like to clarify that I did not write this post but it is an extract from my book which I got from an interview with Dennis Ng. As for your points:
1. Agree completely with you.
2. True that an ETF or mutual fund is unlikely to fall to 0. As for your return, well it all depends on your timing. I could not find an ETF or mutual fund that has returned 18% for the last 15 years (I think emerging markets ETFs are quite a recent phenomenon). Could you name some specific funds that have done so well over this time period?
3. True but short selling is both difficult and risky, and very few people can do it well.
4. Agreed. Transaction costs for property are definitely higher than stocks.
5. This has to do with the liquidity argument above.
As I’ve argued elsewhere, the smart investor will invest in stocks AND properties depending on where the cycle is.
BUT for the average person, property is the most trusted way to build wealth over a long period of time.
Jeffrey
http://www.fundsupermart.com/main/fundinfo/topFunds.svdo
Please check fundsupermart hyperlink above. I invested in most of them. Top 5 performing funds:
1. Aberdeen Indonesia Equity 23.88% per annum
2. Aberdeen Thailand Equity 20.05% per annum
3. LionGlobal Thailand 19.36% per annum
4. United Gold and General Fund 18.16% per annum
5. First State Regional India Fund 17.4% per annumFor indices over 10 years, check out:
1. Russian RTS Index 20.95% per annum
2. Brazil BOVESPA Index 16.09% per annum
3. Mumbai SENSEX 14.71% per annum.
4. Thai SET 13.83% per annum.
5. Hang Seng Mainland 100 11.15%.Please take a look at the URA residential property index. Many Singaporeans swear by property as the way to become rich but I beg to differ. In 1997, Singapore’s property reached the peak and crashed 40%. It rose a bit in 1999 before crashing to a new low. It didn’t reach 1997’s peak until 2010. Mind you, the returns for property if you invested in 1997 was practically ZERO. Timing is everything and it’s not true that property is always a better bet than stocks.
One must remain nimble and buy property when the risk adjusted return is better than stocks and do the opposite when the risk adjusted return is better in stocks. Also, with CFDs, I can short the market and make 20 – 40% in a bear market while you can only long properties. I will have more bullets to buy properties and CFDs when the property and stock market crash in 2012/13 because I don’t just hold cash, but I made double digit returns then.
Mr. Propwise
Hi Jeffrey,
Thanks for this – I’m happy to hear that you’ve had such great returns. You obviously have a knack for picking the top performing funds, and good timing to know when to short the market.
I can only speak from my own experience, and the observations of people around me. I know only a couple of people who have been as successful with the stock market as you have been, and a whole lot more (who didn’t necessarily know what they were doing) who built their wealth via property.
Stocker
Completely agree with Mr Propwise. You are convincingly amazing!
Curious
Hi guys, after looking at the discussion. I was just wondering is it a good time to enter into property stocks which has the best of both worlds. For example, SC Global, isn’t it better to buy their shares now than buying their physical inventory? The shares k be put into lending scheme and enjoy extra return on top of dividends. It is fuss free compared with collecting rental.
Please correct me and advise thanks
Propwise.sg
Hi Curious, the problem with buying the shares of developers is that there could be a disconnect between the property prices and their share prices. For example, over the past year, even as property prices continued to appreciate, the share prices of most developers have fallen significantly.
Geoffrey
After the 5th anti-speculation measure, I’m even more convinced in my argument that one must not invest in only properties but must diversify across different asset classes. Property prices in Singapore will always be subjected to government intervention because it is politically sensitive and has systemic banking risk. Stock market fluctuations are often left alone by the government. With this measure, I will be diversifying my money into overseas properties and stocks.
People have short memories. Those who bought properties in 1997 never broke even until 2010. That’s a good 13 years! The Straits Times Index was 1800 back in 1997, fell to 900 in 1998, rose to 2700 in 2000, fell to 1300 in 2003, rose to 3831 in Nov 2007, fell to 1450 in Mar 2009. Today it is at 2650. It has appreciated far more than real estate!
Michael Tan
Hi Geoffrey, Even the straits Times Index goes to so high, we may not be able to make money. As for my expreince all of my stock brought in 1994 has never recover in prices till now. Even some I still hold it now. Remain only less then 10 percents in money, don’t forget the Malaysia Clob, all the money is freeze till when they return is all most less then 5 %, and the currency also had drop to rm2.45 equal to $1 sing. I had loss almost $400,000 at that time investing in stock market. I was almost broke.
My friend told told me where you fell, you had to get up from there, so I deside to go in to invest again I buy Capital Land two years ago at 4 to 4.20 I think you guy can see what is the prices now right. I loss again more then 100k. So my lesson is that even if you had a chance to make gain or profit in stock sold it to take profit. What ever goes up will come down in stock market this is where the rich make money from you.
But not in the property market.
For my view on property market.
And I buy my first 3 room flat 1996 at open market, as I was broke in the stock market and could not affort to buy bigger one, so I bourght a HDB 3 room at $158,000/ + renovation $40,000/ ++ Interst rate for 5 years $18,000/+ total $216,000/ After staying for 11 years for free, I sold it for $268,000/ If add the 11 years rental of $1,100 per month = $145,000 + $52,000 profit = $197,000/ Saved. Now that 3 room is $350,000/ if I can keep it.Even during the property market cruse time, 1998 I saw my neigbhour selling his 3 room flat two floor below mine, same block as my at $180,000/
Then in 2006 I want to change my HDB to a 5 room flat. Simei Prices in 2006 $295k till I find one in 2008 the prices $400,000 so I quickly buy, now is around $500,000 +
So I started to invest in Private And Commercial Property 2010, The prices has go up 30 – 150+ percent in value. and had rental yeild every month not included in the percentage.
As for the private condo. that i had brought, the monthly rental cannot cover my instatment So I had to top up $100 to $300 per month. I still think is worth it. If I put in the bank of $180,000/ what is the Interst rate every body should know. But I put into the property after the collecting rental and deduct the the bank interst rate I still had $2,000 left over as a passion income or call it a Private CPF, ( as I had to pay to the Bank for the moragate).
So I would recommend Jeffery and Geoffery to come out and teach some course for the new invester if you are so good in the stock market, Y keep it to your self and recommend some to the student to make money.
But for my own comments only, is, if you are buying a home to stay no matter a HDB or Condo or Landed property, just buy within your own burget and home that you like. you sure to earn in value. It’s just that simple, don’t need like stock to value it, and keep worrying the europe and US or China up or down.
So for investment in property also within in your arm length, like if there is no rental to collect you can still pay the instatment that’s will be fine, that may be for a year. And one more thing investing in property is a very slow process don’t think over night will increase in value or income. Maybe some time have for flipping. But for stock market or cassino can.
Hope more people to commend and to share their ideals. Happy investing to all of you no matter in property or stock market. Not cassino ya… CHEERS