FOMO and Property Investing: How to Avoid It (2026)
FOMO makes property buyers pay on someone else's deadline. See what past Singapore peaks cost, the real price of acting versus waiting, and a pause rule.
FOMO, the fear of missing out, makes you buy on a deadline someone else set. In property the deadline is usually a sales gallery, a queue or a headline about record prices. Singapore’s data show that buying at the top of a cycle is survivable only if you can hold, and that being forced to sell early can cost more than waiting a year. Decide your terms before you walk into the show flat, not after.
At a glance
- 2012 was the busiest year for new private home sales in the URA series since 1999, at 22,197 units. By 2014 sales were 67% lower, at 7,316.
- Buyers at the 1996, 2008 and 2013 price peaks all had paper gains by 2026, but they waited 14, 2 and about 7 years to get back to even.
- Worked example: waiting a year while prices rise 5% costs S$78,750 on a S$1.5m home. A forced sale in year three after a 6.7% fall costs S$256,600.
- A pause rule works: set your ceiling and your walk-away cost in writing, then wait a set time before paying any booking fee.
How FOMO sounds in a sales gallery
The scripts are familiar. “This is the last unit in that stack.” “Two other buyers are checking with their bank now.” “The developer will raise prices next phase.” “Smart investors are coming back.” Each one turns a purchase into a race. A race leaves no time to compare recent transactions, test your loan or ask whether you want this unit at all.
The same push comes from outside the gallery. Policy news, a new MRT line announcement and a headline about a sell-out all say that the window is closing. Real windows do close.
Units
Source: URA, private residential sales (October 2026). Sales in 2014 were 67% lower than in 2012.
What past peaks actually cost
The table shows what an average buyer at three market tops experienced. It uses the URA private home price index, so it describes the market and not any one unit.
| Entry quarter | Index | Worst fall after entry | Back above entry price | Gain to Q2 2026 | Per year |
|---|---|---|---|---|---|
| Q2 1996 | 129.7 | −44.9% (to Q4 1998) | Q2 2010, 14 years | +69.2% | 1.8% |
| Q2 2008 | 126.9 | −24.9% (to Q2 2009) | Q2 2010, 2 years | +72.9% | 3.1% |
| Q3 2013 | 154.6 | −11.6% (to Q2 2017) | Q4 2020, about 7 years | +41.9% | 2.8% |
Source: URA; nominal terms, ignoring costs, interest and the lease of any single home. Our guide on whether prices always go up adds inflation: the 1996 buyer’s gain of 1.8% a year was barely above the 1.7% a year of inflation.
Years
Source: URA private residential price index (data.gov.sg) (Q2 2026). Gain to Q2 2026: +69.2% (1996), +72.9% (2008), +41.9% (2013). Ignoring costs and interest.
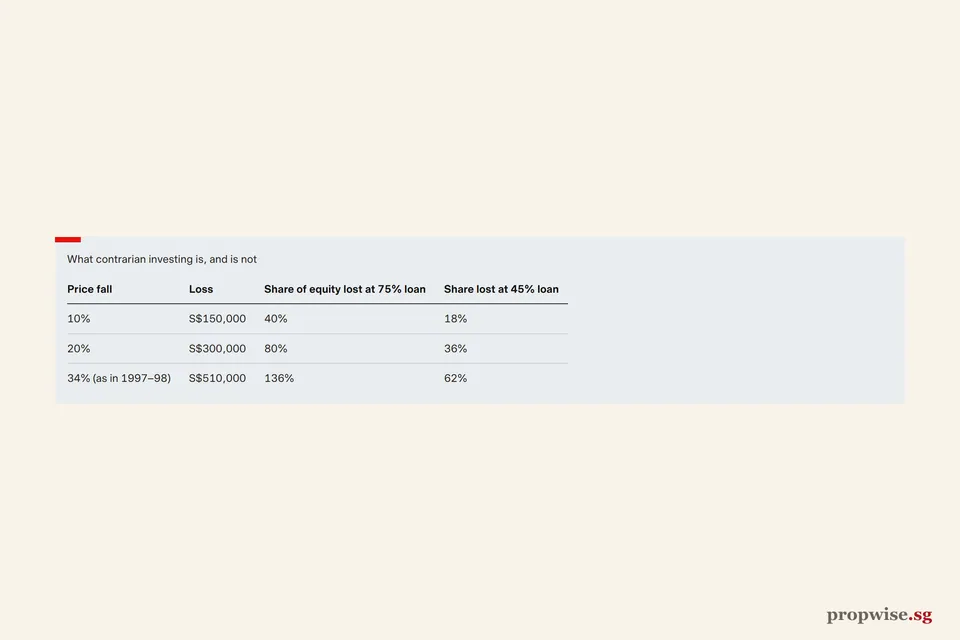
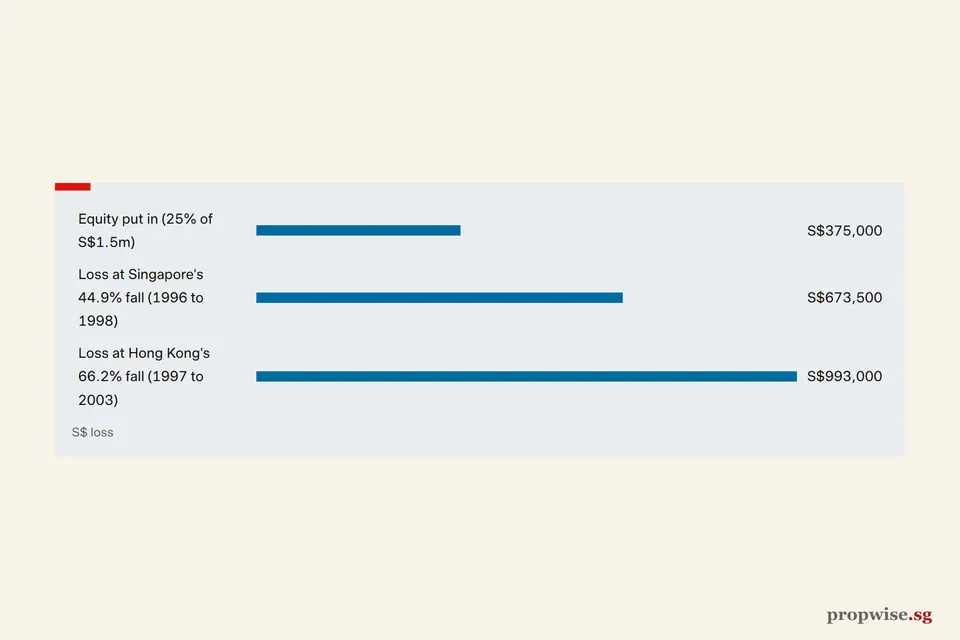
Two things stand out. First, none of the three buyers lost money in the long run on an index basis. Second, the pain came from the path. The 1996 buyer saw the market fall 45% over two and a half years and waited 14 years to break even. With a mortgage, that is a very different experience from the index line. Our guide to being a contrarian property investor shows how leverage magnifies those falls.
Acting versus waiting: the cost of each
FOMO only counts one cost, the cost of waiting. Here are both, as made-up examples on a S$1.5m home bought by a Singapore Citizen as a first home (ABSD 0%), with a 25% down payment of S$375,000.
Example A: you buy now, then must sell in year three. BSD on S$1.5m is S$44,600. Say a job move forces a sale after more than two but not more than three years, and the home sells for S$1.4m, down 6.7%. Seller’s Stamp Duty for a home bought from 4 July 2025 is 8% in that period, or S$112,000. Your loss is S$100,000 (price) + S$44,600 + S$112,000 = S$256,600, which is 68% of your equity, before interest and agent fees.
Example B: you wait 12 months. Say prices rise 5% while you wait, so the same home costs S$1.575m. That is S$75,000 more, and BSD rises by S$3,750 to S$48,350, since the amount above S$1.5m is taxed at 5%. The cost of waiting is S$78,750, less the rent you may save or the interest your cash earns.
S$
Source: IRAS, Buyer's Stamp Duty (October 2026); IRAS, Seller's Stamp Duty. A: sold at S$1.4m (-6.7%) after more than two years: price loss S$100,000, BSD S$44,600, SSD 8% S$112,000. B: prices rise 5%: S$75,000 more plus S$3,750 more BSD, before rent saved or interest earned. Before interest and agent fees.
The point is that the second number is real, and the first is the one the sales script hides. If you can hold for at least four years and the mortgage works at the 4% stress-test rate, the forced-sale risk falls. If you cannot, it is the larger risk. Run your own figures in the mortgage calculator.
When fear of inflation drives the purchase
A close cousin of FOMO is the argument that cash in the bank loses value, so you must buy property now. Cash does lose to inflation, and that matters. But property bought at a peak can lose to inflation too. In our guide on the data, a buyer at the 1996 peak had to wait until Q1 2025 for the price index to regain its 1996 level after inflation. Buying property because you fear inflation is a defensive move.
A pause rule that works
- 1Before you visitWrite your ceilingBase it on recent transactions nearby and your own loan limit. Do not revise it in the gallery.
- 2Before you visitGet loan approval firstTest the loan at the 4% stress-test rate.
- 3Before you payKnow your walk-away costOn a new launch the developer may keep 25% of the booking fee: S$25,000 on a S$100,000 fee.
- 4After the visitWait a fixed timeFor example 72 hours between seeing a unit and paying a fee.
- 5Before you decideAsk the no-one-else questionWould you still buy if nobody else wanted it?
- 6ThroughoutCheck price, volume, rents and vacancyRead the signals, not the queue.
Source: Propwise checklist, using IRAS, MAS and URA rules cited in this guide (October 2026).
- Write your ceiling before you visit. Base it on recent transactions in the same development or area, and your own loan limit. Do not revise it in the gallery.
- Get loan approval first. Our showflat checklist lists what banks ask for.
- Know your walk-away cost. If you hold an option for a new launch and let it lapse, the developer may keep 25% of the booking fee, as we explain in the truth about new launches. On a S$100,000 fee that is S$25,000, which is far cheaper than a purchase you doubt.
- Wait before you pay. Set a fixed pause, for example 72 hours, between seeing a unit and paying a fee. A deal that survives three days is still a deal.
- Ask the “no one else” question. Would you still buy this if nobody else wanted it? If the answer is no, the crowd is doing the deciding.
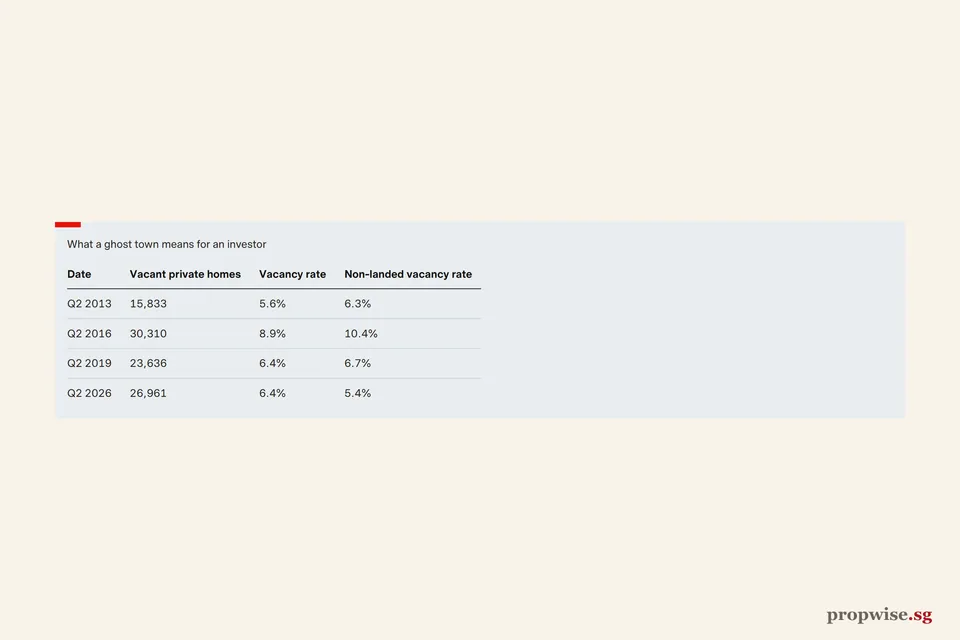
- Check the signals, not the crowd. Look at price, volume, rents and vacancy. Our note on what volumes tell us shows how.
Bottom line
FOMO feels like opportunity, but it is a timetable set by someone who earns when you say yes. The data show that a rushed purchase at a peak can be a long wait to break even, and that waiting also has a cost. Decide what you can afford to hold, set your price and your walk-away rule in writing, and let the numbers, not the queue, say when.