Singapore Cooling Measures: ABSD, LTV, TDSR, MSR and SSD (2026)
Singapore's 2026 cooling measures in one place: ABSD, LTV, TDSR, MSR and the 4-year SSD, with worked examples of the cash and income a second property needs.
Before you buy a home in Singapore, and especially before you buy a second one, five rules decide how much cash you need and how much you can borrow: ABSD, the loan-to-value (LTV) limit, the TDSR, the MSR and the Seller’s Stamp Duty. None of them were relaxed in 2026, and two of them (SSD and the HDB loan limit) were tightened in the last two years. If you last read about them in 2017, almost every number has changed.
At a glance
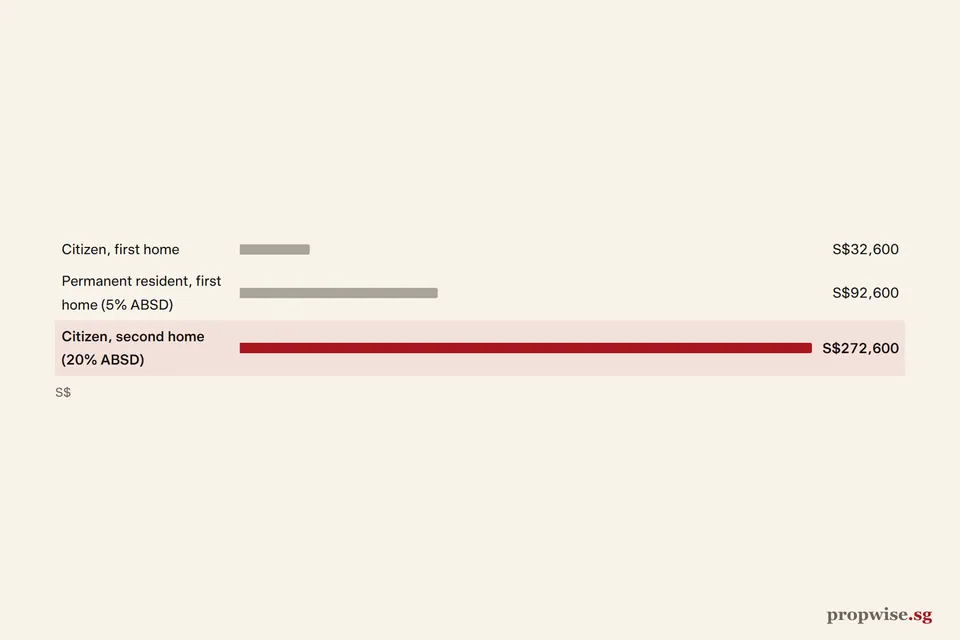
- ABSD for a Singapore Citizen is 0% on the first home, 20% on the second and 30% on the third. PRs pay 5% / 30% / 35%. Foreigners pay 60% on any home.
- LTV: a bank lends at most 75% on your first housing loan, 45% if you already have one, and 35% if you have two or more.
- TDSR: all your monthly debt repayments, tested at a 4% interest rate, must stay within 55% of gross income. MSR caps the mortgage at 30% of income for HDB flats and new ECs.
- SSD applies if you sell within 4 years (for homes bought from 4 July 2025), at 16% / 12% / 8% / 4%.
- Old numbers are gone: the 60% TDSR, 7% ABSD and 3-year SSD in older articles no longer apply.
- Singapore Citizen
- 0% / 20% / 30%
- Singapore PR
- 5% / 30% / 35%
- Foreigner
- 60% on any home
- No housing loan
- 75%
- One loan
- 45%
- Two or more
- 35%
- Cap
- 55% of gross income
- Test rate
- 4% (HDB loans 3%)
- Cap
- 30% of gross income
- Applies to
- HDB flats and new ECs from a developer
- Sold in year 1
- 16%
- Year 2
- 12%
- Year 3
- 8%
- Year 4
- 4%
Source: IRAS, ABSD and SSD (October 2026); MAS, loan-to-value limits; MAS, MSR and TDSR rules.
Measure 1: Additional Buyer’s Stamp Duty (ABSD)
ABSD is a tax you pay on top of the normal Buyer’s Stamp Duty (1% to 6% of the price). It applies to private homes and HDB flats alike, and it is due within 14 days of signing, so plan to pay it in cash first. The current rates took effect on 27 April 2023 and are unchanged as at October 2026:
| Buyer | 1st home | 2nd home | 3rd and later |
|---|---|---|---|
| Singapore Citizen | 0% | 20% | 30% |
| Singapore PR | 5% | 30% | 35% |
| Foreigner | 60% | 60% | 60% |
| Company or trust | 65% | 65% | 65% |
Source: IRAS — ABSD.
Three details catch people out:
- Joint buyers pay the highest rate among them, on the whole price. A Singapore Citizen with no home who buys with a sibling who already owns a flat pays 20% on the full price, not on half.
- Your status on the purchase date counts. If you still own your first home on the day you accept the option to purchase (OTP) for the next one, the new home is your second.
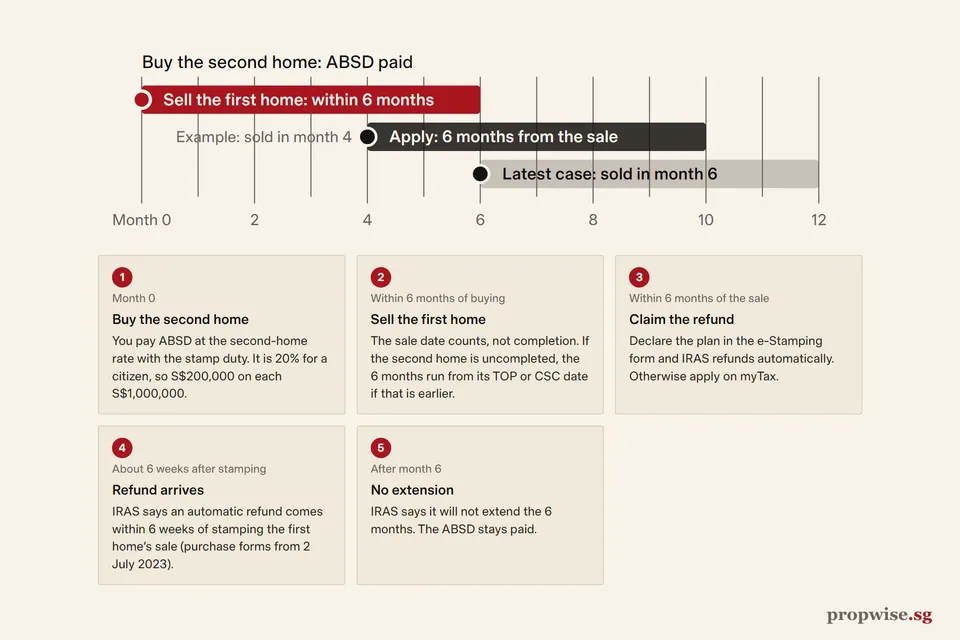
- Married couples have a refund route. A couple with at least one citizen who buys a second home together pays the 20% upfront, then gets it back if they sell the first home within six months of buying a completed property (or of the TOP of an uncompleted one). Single citizens have no such refund unless they are 55 or older and buy a lower-value home.
The full rate tables and more examples are in our stamp duty guide.
Measure 2: loan-to-value (LTV) limits
LTV is the share of the price (or valuation, if lower) that a bank may lend. The MAS limits depend on how many housing loans you already have:
| Your existing housing loans | Max LTV | Min cash downpayment | LTV if tenure > 30 years or past age 65 |
|---|---|---|---|
| None | 75% | 5% | 55% |
| One | 45% | 25% | 25% |
| Two or more | 35% | 25% | 15% |
The cut-off for the lower column is a tenure above 30 years (25 years for an HDB flat) or a loan that runs past age 65. Companies and other non-individual borrowers get only 15%.
If you take an HDB loan, the limit is 75%. HDB cut it from 80% on 20 August 2024. It was 90% before December 2021.
The trap the 2017 version of this article warned about still applies: banks lend on the lower of price and valuation. If you pay S$1.5m and the bank values the unit at S$1.45m, it lends 75% of S$1.45m, which is S$1,087,500 instead of S$1,125,000. Your share rises by S$37,500, and the S$50,000 above valuation must be paid in cash. Ask for an indicative valuation before you sign the OTP.
Measures 3 and 4: TDSR and MSR
The Total Debt Servicing Ratio caps all your monthly debt repayments (home loans, car loans, other property loans and part of any loan you guarantee) at 55% of gross monthly income. It was 60% until 16 December 2021.
The bank does not test you at today’s rate. It uses a 4% medium-term rate for residential loans, set by MAS on 30 September 2022. HDB loans are tested at 3%. That matters in 2026. Three-month SORA was about 1.24% on 14 Oct 2026, and after the US Fed hike packages cost about 1.5–1.8% floating and 2.0–2.2% fixed (The Business Times, 2 Oct 2026), so your real instalment will be far below the instalment that the bank tests.
- 3-month compounded SORA (Singapore)
- US federal funds rate (effective)
Latest: SORA 1.24% (14 Oct 2026); Fed 3.88% (13 Oct 2026).
SORA is the benchmark for floating-rate home loans in Singapore. The US rate is shown for context: it moves SORA only indirectly, through the Singapore dollar and bank funding costs.
Table view
| Period | 3-month compounded SORA (Singapore) | US federal funds rate (effective) |
|---|---|---|
| Oct 2026 | 1.24% | 3.88% |
| Sep 2026 | 1.23% | 3.88% |
| Aug 2026 | 1.18% | 3.63% |
| Jul 2026 | 1.14% | 3.63% |
| Jun 2026 | 1.08% | 3.63% |
| May 2026 | 1.06% | 3.62% |
| Apr 2026 | 1.03% | 3.64% |
| Mar 2026 | 1.07% | 3.64% |
| Feb 2026 | 1.12% | 3.64% |
| Jan 2026 | 1.15% | 3.64% |
| Dec 2025 | 1.19% | 3.64% |
| Nov 2025 | 1.25% | 3.89% |
| Oct 2025 | 1.32% | 4.11% |
| Sep 2025 | 1.46% | 4.09% |
| Aug 2025 | 1.56% | 4.33% |
| Jul 2025 | 1.86% | 4.33% |
| Jun 2025 | 2.06% | 4.33% |
| May 2025 | 2.27% | 4.33% |
| Apr 2025 | 2.40% | 4.33% |
| Mar 2025 | 2.55% | 4.33% |
| Feb 2025 | 2.73% | 4.33% |
| Jan 2025 | 2.90% | 4.33% |
| Dec 2024 | 3.08% | 4.33% |
| Nov 2024 | 3.21% | 4.58% |
| Oct 2024 | 3.39% | 4.83% |
| Sep 2024 | 3.49% | 4.83% |
| Aug 2024 | 3.57% | 5.33% |
| Jul 2024 | 3.64% | 5.33% |
| Jun 2024 | 3.63% | 5.33% |
| May 2024 | 3.66% | 5.33% |
| Apr 2024 | 3.65% | 5.33% |
| Mar 2024 | 3.68% | 5.33% |
| Feb 2024 | 3.64% | 5.33% |
| Jan 2024 | 3.66% | 5.33% |
| Dec 2023 | 3.70% | 5.33% |
| Nov 2023 | 3.75% | 5.33% |
| Oct 2023 | 3.75% | 5.33% |
| Sep 2023 | 3.70% | 5.33% |
| Aug 2023 | 3.70% | 5.33% |
| Jul 2023 | 3.68% | 5.33% |
| Jun 2023 | 3.65% | 5.07% |
| May 2023 | 3.61% | 5.08% |
| Apr 2023 | 3.61% | 4.83% |
| Mar 2023 | 3.58% | 4.83% |
| Feb 2023 | 3.23% | 4.58% |
| Jan 2023 | 3.12% | 4.33% |
| Dec 2022 | 3.03% | 4.33% |
| Nov 2022 | 2.87% | 3.83% |
| Oct 2022 | 2.45% | 3.08% |
| Sep 2022 | 2.07% | 3.08% |
| Aug 2022 | 1.55% | 2.33% |
| Jul 2022 | 1.27% | 2.32% |
| Jun 2022 | 0.72% | 1.58% |
| May 2022 | 0.52% | 0.83% |
| Apr 2022 | 0.32% | 0.33% |
| Mar 2022 | 0.27% | 0.33% |
| Feb 2022 | 0.25% | 0.08% |
| Jan 2022 | 0.20% | 0.08% |
| Dec 2021 | 0.19% | 0.08% |
| Nov 2021 | 0.16% | 0.08% |
| Oct 2021 | 0.16% | 0.07% |
| Sep 2021 | 0.13% | 0.08% |
| Aug 2021 | 0.13% | 0.08% |
| Jul 2021 | 0.13% | 0.10% |
| Jun 2021 | 0.14% | 0.10% |
| May 2021 | 0.17% | 0.05% |
| Apr 2021 | 0.19% | 0.07% |
| Mar 2021 | 0.23% | 0.07% |
| Feb 2021 | 0.20% | 0.07% |
| Jan 2021 | 0.17% | 0.07% |
| Dec 2020 | 0.17% | 0.09% |
| Nov 2020 | 0.12% | 0.08% |
| Oct 2020 | 0.12% | 0.09% |
| Sep 2020 | 0.10% | 0.09% |
| Aug 2020 | 0.10% | 0.09% |
| Jul 2020 | 0.08% | 0.09% |
| Jun 2020 | 0.14% | 0.08% |
| May 2020 | 0.27% | 0.05% |
| Apr 2020 | 0.53% | 0.05% |
| Mar 2020 | 0.90% | 0.10% |
| Feb 2020 | 1.14% | 1.58% |
| Jan 2020 | 1.20% | 1.55% |
| Dec 2019 | 1.27% | 1.55% |
| Nov 2019 | 1.31% | 1.55% |
| Oct 2019 | 1.46% | 1.83% |
| Sep 2019 | 1.53% | 1.83% |
| Aug 2019 | 1.59% | 2.12% |
| Jul 2019 | 1.67% | 2.40% |
| Jun 2019 | 1.72% | 2.40% |
| May 2019 | 1.68% | 2.38% |
| Apr 2019 | 1.62% | 2.44% |
| Mar 2019 | 1.54% | 2.43% |
| Feb 2019 | 1.59% | 2.40% |
| Jan 2019 | 1.52% | 2.40% |
The Mortgage Servicing Ratio is a second, tighter cap. The mortgage alone may not exceed 30% of income. It applies only to loans for HDB flats, and for ECs bought from a developer while their minimum occupation period runs. It does not apply to private condos or landed homes.
Example: you borrow S$1,125,000 over 30 years. At the 4% test rate the instalment is about S$5,371 a month. With no other debts, TDSR needs a gross income of at least S$5,371 ÷ 0.55 ≈ S$9,765 a month. If the same loan were for an HDB flat or a new EC, MSR would need S$5,371 ÷ 0.30 ≈ S$17,903. At an actual 1.8% rate, the real instalment would be about S$4,047. Run your own numbers in the Propwise mortgage calculator.
Measure 5: Seller’s Stamp Duty (SSD)
SSD is a tax on selling a home soon after you buy it. On 4 July 2025 the holding period went from three years to four, and each rate rose by four points:
| Sold within | Bought on or after 4 Jul 2025 | Bought 11 Mar 2017 – 3 Jul 2025 |
|---|---|---|
| 1 year | 16% | 12% |
| 2 years | 12% | 8% |
| 3 years | 8% | 4% |
| 4 years | 4% | 0% |
| After 4 years | 0% | 0% |
Source: IRAS — SSD.
SSD is charged on the sale price or market value, whichever is higher, not on your profit. Say you bought a condo for S$1.5m in September 2025 and sell it for S$1.6m in October 2027, two years and one month later. SSD is 8% × S$1.6m = S$128,000. That is more than the S$100,000 gain, before agent and legal fees. Plan to hold any purchase for at least four years.
Worked example: a citizen couple buying a second property
Take a married citizen couple who own an HDB flat past its minimum occupation period. They want to buy a S$1.5m condo and keep the flat. (They must wait out the MOP first. ABSD applies because the flat counts as their first property.)
| Cost | Flat fully paid off | Flat still has a loan |
|---|---|---|
| Buyer’s Stamp Duty | S$44,600 | S$44,600 |
| ABSD at 20% | S$300,000 | S$300,000 |
| Maximum bank loan | 75% = S$1,125,000 | 45% = S$675,000 |
| Downpayment | S$375,000 (min S$75,000 cash) | S$825,000 (min S$375,000 cash) |
| Total upfront | S$719,600 | S$1,169,600 |
The BSD works out as 1% of the first S$180,000, 2% of the next S$180,000, 3% of the next S$640,000 and 4% of the last S$500,000: S$1,800 + S$3,600 + S$19,200 + S$20,000 = S$44,600.
If the couple decide to move into the condo and sell the flat within six months, the S$300,000 ABSD comes back to them. If they keep the flat as an investment, it does not. For many families, the 20% ABSD is the single biggest reason to “sell one, buy one” rather than accumulate.
S$, total upfront
Source: Propwise worked example, using IRAS and MAS rules (October 2026). ABSD of S$300,000 is refunded if the couple sell the first home within six months.
What changed since this article first ran
The 2017 version listed four measures. Here is what has moved since then:
- ABSD for a citizen’s second home went from 7% to 12% (July 2018), 17% (2021) and 20% (2023). For foreigners it went from 15% to 20% (2018), 30% (2021) and 60% (2023).
- TDSR fell from 60% to 55%. The stress-test rate rose from 3.5% to 4%.
- LTV for long loans fell. For a tenure above 30 years or past age 65, the limits are now 55% / 25% / 15% (first / second / third loan), lower than the limits in force when this article first ran; they were cut in July 2018.
- SSD became a 4-year tax again from 4 July 2025.
- HDB loans shrank from 90% to 75% LTV.
- 1July 2018ABSD for a citizen's second homeUp from 7% to 12%. LTV limits for long loans cut.
- 22021ABSD for a citizen's second homeUp to 17%. TDSR falls from 60% to 55% on 16 December 2021.
- 327 April 2023ABSDCitizen's second home 20%. Foreigners 60%.
- 420 August 2024HDB loan limitCut to 75% LTV (80% before; 90% before December 2021).
- 54 July 2025Seller's Stamp DutyHolding period back to four years, with rates of 16%, 12%, 8% and 4%.
Source: MAS, 2018 measures (October 2026); MND, 16 December 2021 measures; MAS, 4 July 2025 SSD change; MND, 27 April 2023 ABSD rates.
- Private homes (URA price index)
- HDB resale flats (HDB Resale Price Index)
- Policy measures (select one for details)
Latest: Private 219.4 (Q2 2026); HDB 202.8 (Q2 2026).
Table view
| Period | Private homes (URA price index) | HDB resale flats (HDB Resale Price Index) |
|---|---|---|
| Q2 2026 | 219.4 | 202.8 |
| Q1 2026 | 218.3 | 203.4 |
| Q4 2025 | 216.4 | 203.6 |
| Q3 2025 | 215.1 | 203.7 |
| Q2 2025 | 213.2 | 202.9 |
| Q1 2025 | 211.1 | 201.0 |
| Q4 2024 | 209.4 | 197.9 |
| Q3 2024 | 204.7 | 192.9 |
| Q2 2024 | 206.1 | 187.9 |
| Q1 2024 | 204.3 | 183.7 |
| Q4 2023 | 201.5 | 180.4 |
| Q3 2023 | 196.0 | 178.5 |
| Q2 2023 | 194.4 | 176.2 |
| Q1 2023 | 194.8 | 173.6 |
| Q4 2022 | 188.6 | 171.9 |
| Q3 2022 | 187.8 | 168.1 |
| Q2 2022 | 180.9 | 163.9 |
| Q1 2022 | 174.8 | 159.5 |
| Q4 2021 | 173.6 | 155.7 |
| Q3 2021 | 165.3 | 150.6 |
| Q2 2021 | 163.5 | 146.4 |
| Q1 2021 | 162.2 | 142.2 |
| Q4 2020 | 157.0 | 138.1 |
| Q3 2020 | 153.8 | 133.9 |
| Q2 2020 | 152.6 | 131.9 |
| Q1 2020 | 152.1 | 131.5 |
| Q4 2019 | 153.6 | 131.5 |
| Q3 2019 | 152.8 | 130.9 |
| Q2 2019 | 150.8 | 130.8 |
| Q1 2019 | 148.6 | 131.0 |
| Q4 2018 | 149.6 | 131.4 |
| Q3 2018 | 149.7 | 131.6 |
| Q2 2018 | 149.0 | 131.7 |
| Q1 2018 | 144.1 | 131.6 |
| Q4 2017 | 138.7 | 132.6 |
| Q3 2017 | 137.6 | 132.8 |
| Q2 2017 | 136.6 | 133.7 |
| Q1 2017 | 136.7 | 133.9 |
| Q4 2016 | 137.2 | 134.6 |
| Q3 2016 | 137.9 | 134.7 |
| Q2 2016 | 140.0 | 134.7 |
| Q1 2016 | 140.6 | 134.7 |
| Q4 2015 | 141.6 | 134.8 |
| Q3 2015 | 142.3 | 134.6 |
| Q2 2015 | 144.2 | 135.0 |
| Q1 2015 | 145.5 | 135.6 |
| Q4 2014 | 147.0 | 137.0 |
| Q3 2014 | 148.6 | 139.1 |
| Q2 2014 | 149.7 | 141.5 |
| Q1 2014 | 151.3 | 143.5 |
| Q4 2013 | 153.2 | 145.8 |
| Q3 2013 | 154.6 | 148.1 |
| Q2 2013 | 154.0 | 149.4 |
| Q1 2013 | 152.4 | 148.6 |
| Q4 2012 | 151.5 | 146.7 |
| Q3 2012 | 148.8 | 143.1 |
| Q2 2012 | 147.9 | 140.3 |
| Q1 2012 | 147.2 | 138.5 |
| Q4 2011 | 147.4 | 137.7 |
| Q3 2011 | 147.0 | 135.4 |
| Q2 2011 | 145.1 | 130.4 |
| Q1 2011 | 142.3 | 126.4 |
| Q4 2010 | 139.2 | 124.4 |
| Q3 2010 | 135.5 | 121.3 |
| Q2 2010 | 131.7 | 116.6 |
| Q1 2010 | 125.1 | 112.1 |
| Q4 2009 | 118.4 | 109.0 |
| Q3 2009 | 110.3 | 105.0 |
| Q2 2009 | 95.3 | 101.4 |
| Q1 2009 | 100.0 | 100.0 |
| Q4 2008 | 116.4 | 100.8 |
| Q3 2008 | 123.9 | 99.4 |
| Q2 2008 | 126.9 | 95.4 |
| Q1 2008 | 126.7 | 91.3 |
| Q4 2007 | 122.1 | 88.0 |
| Q3 2007 | 114.4 | 83.2 |
| Q2 2007 | 105.6 | 78.1 |
| Q1 2007 | 97.6 | 75.8 |
| Q4 2006 | 93.1 | 74.9 |
| Q3 2006 | 89.6 | 74.2 |
| Q2 2006 | 87.3 | 74.3 |
| Q1 2006 | 85.8 | 73.6 |
| Q4 2005 | 84.5 | 73.5 |
| Q3 2005 | 83.3 | 73.2 |
| Q2 2005 | 82.3 | 73.5 |
| Q1 2005 | 81.9 | 77.2 |
| Q4 2004 | 81.3 | 77.1 |
| Q3 2004 | 80.7 | 76.3 |
| Q2 2004 | 80.4 | 76.2 |
| Q1 2004 | 80.3 | 75.3 |
| Q4 2003 | 80.6 | 75.1 |
| Q3 2003 | 80.7 | 74.3 |
| Q2 2003 | 81.1 | 72.5 |
| Q1 2003 | 81.6 | 71.0 |
| Q4 2002 | 82.3 | 69.9 |
| Q3 2002 | 82.6 | 69.9 |
| Q2 2002 | 82.2 | 69.2 |
| Q1 2002 | 82.8 | 69.1 |
| Q4 2001 | 83.8 | 69.6 |
| Q3 2001 | 87.6 | 70.6 |
| Q2 2001 | 90.3 | 72.1 |
| Q1 2001 | 91.1 | 73.2 |
| Q4 2000 | 94.9 | 75.8 |
| Q3 2000 | 97.6 | 77.6 |
| Q2 2000 | 100.4 | 79.3 |
| Q1 2000 | 98.9 | 80.3 |
| Q4 1999 | 95.9 | 79.8 |
| Q3 1999 | 91.1 | 78.1 |
| Q2 1999 | 84.3 | 72.2 |
| Q1 1999 | 75.4 | 71.2 |
Policy measures marked on this chart (23)
- 2025-07-03 Seller's Stamp Duty holding period back to four years, rates raised by 4 pp
- 2024-08-19 HDB loan LTV cut to 75% and Enhanced CPF Housing Grant raised
- 2023-04-26 ABSD rates raised, April 2023
- 2023-02-14 CPF Housing Grant raised for first-time resale buyers, Budget 2023
- 2023-02-14 Buyer's Stamp Duty raised for higher-value properties, Budget 2023
- 2022-09-29 Property measures, September 2022: higher TDSR and MSR rate floor, HDB loan LTV 80%, 15-month wait-out
- 2021-12-15 Property cooling measures, December 2021: higher ABSD, TDSR 55%, HDB loan LTV 85%
- 2018-07-05 Property cooling measures, July 2018: higher ABSD and lower LTV limits
- 2018-02-19 Budget 2018: Proximity Housing Grant enhanced
- 2018-02-19 Budget 2018: top BSD rate raised to 4% above S$1m
- 2017-03-10 SSD holding period cut to 3 years; TDSR relaxed for equity withdrawal
- 2013-08-27 HDB loan and resale measures, August 2013
- 2013-06-28 MAS introduces the Total Debt Servicing Ratio (TDSR) framework
- 2013-01-11 Property cooling measures, January 2013
- 2012-10-05 Maximum loan tenure of 35 years and tighter LTV limits, October 2012
- 2011-12-07 Additional Buyer's Stamp Duty introduced, December 2011
- 2011-01-13 Property cooling measures, January 2011
- 2010-08-30 HDB measures after National Day Rally 2010: DBSS income ceiling, 5-year MOP for non-subsidised flats
- 2010-08-30 Property cooling measures, August 2010
- 2010-02-19 Seller's Stamp Duty introduced and LTV limit cut to 80%, February 2010
- 2009-09-14 Interest-only loans and Interest Absorption Scheme disallowed, September 2009
- 2005-07-19 Property policy review, July 2005: LTV limit raised to 90%, CPF housing rules eased, foreign ownership rules eased
- 2001-10-12 Second off-budget package, October 2001: property tax rebate, stamp duty cut, gains tax removed, land sales eased
The 15-month wait-out for private owners buying a resale flat without an HDB loan was removed on 28 July 2026. This is the only recent easing, and it helps downgraders, not investors.
Bottom line
The 2026 rules reward owner-occupiers and penalise accumulation and quick flips. Before you look at showflats, work out three numbers: your ABSD rate, your LTV tier, and the loan your income supports at the 4% test rate. Then add four years of holding costs to your plan. For the loan side, see our guides to TDSR and LTV limits.