BTO Criteria and HDB Flat Types: How to Choose a Flat
BTO criteria, the S$16,000 income ceiling, HDB flat types and sizes, Standard, Plus or Prime, lease and grants, with real HDB resale prices by town.
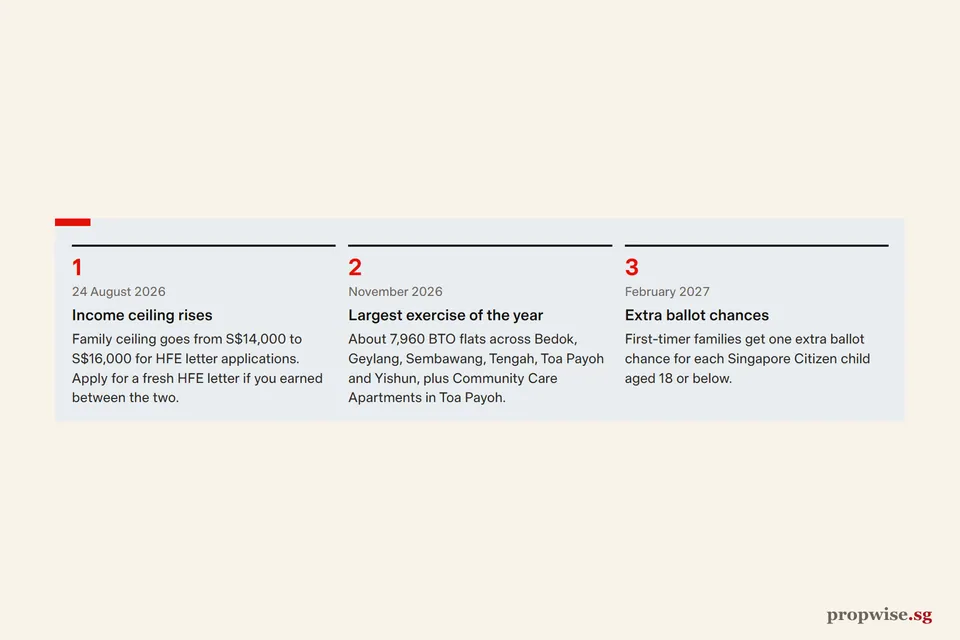
To buy a new BTO flat, one buyer must be a Singapore citizen and a family must earn S$16,000 a month or less. Singles aged 35 or over face a S$8,000 ceiling. After that, choosing the right flat comes down to five decisions, in order: budget, new or resale, flat type, class (Standard, Plus or Prime) and location.
Get the order wrong and you end up with a flat you love but cannot finance. Or one you can afford but must keep for ten years when you need to move in five. Both are hard to undo, and HDB does not take returns.
At a glance
- BTO criteria: one citizen buyer, aged 21 or over (35 for singles), income within the ceiling, and no private property in the past 30 months.
- Work out your budget first. Your HDB loan instalment can be at most 30% of gross monthly income, tested at a 3% rate.
- New (BTO) flats are much cheaper, but you wait about three to four years.
- Resale flats let you move in within months and choose the exact block. A first-timer family can get up to S$230,000 in grants.
- Plus and Prime flats have a 10-year minimum occupation period (MOP) and cannot be rented out whole. Standard flats have a 5-year MOP.
- Check the remaining lease. To use CPF in full, it must cover the youngest buyer to age 95.
What are the BTO criteria?
HDB checks four things before you can book a new flat: citizenship, age, income and property. You confirm all four in one step, the HDB Flat Eligibility (HFE) letter, which also tells you your loan and grants.
| Criterion | Families | Singles |
|---|---|---|
| Citizenship | At least one Singapore citizen; the other a citizen or PR | Singapore citizen |
| Age | 21 or over | 35 or over |
| Monthly income ceiling | S$16,000 (S$24,000 for extended families) | S$8,000 |
| Flat types | All, including 3Gen if you live with a parent | 2-room Flexi |
| Private property | None owned, and none sold in the past 30 months | Same |
Source: HDB. Rules as at November 2026.
The income ceiling rose from S$14,000 to S$16,000 for families for HFE applications from 24 August 2026. The singles ceiling rose from S$7,000 to S$8,000 at the same time.
Our rules page keeps the full history. The full list of conditions is on HDB’s eligibility page.
The 30-month rule is the wait-out for subsidised flats. A separate 15-month wait-out for resale flats bought without a grant was removed on 28 July 2026. Private owners can now buy such a flat at once, if they sell their private home within six months.
1. How much can you afford? Start with your budget
For an HDB loan, the mortgage servicing ratio (MSR) caps the monthly instalment at 30% of gross household income. HDB calculates eligibility at a floor rate of 3%, although the actual HDB loan rate is 2.60%.
The loan can cover up to 75% of the price, and the maximum term is 25 years.
Example. A couple earns S$9,000 a month, and 30% of that is S$2,700. At 3% over 25 years, that supports a loan of about S$569,000, which is 75% of a flat costing about S$759,000.
The other 25%, about S$190,000, must come from CPF Ordinary Account savings, cash and grants. In practice, the CPF and cash you have often limit you before the loan does.
In the 12 months to October 2026, the median 4-room flat sold for S$630,000 and the median 5-room flat for S$745,000. This couple can afford most 4-room flats and many 5-room flats, but few 5-room flats in the most popular towns. Run your own numbers in the Propwise mortgage calculator.
A bank loan for an HDB flat is tested at a 4% stress rate and has no HDB income ceiling. The same 30% MSR applies. See our HDB home loan guide.
2. New or resale?
| New flat (BTO) | Resale flat | |
|---|---|---|
| Price | Lowest. In February 2026, 4-room Standard flats at Sembawang Voyage started from S$304,000 before grants | Market price. Median 4-room S$630,000 in the 12 months to October 2026 |
| Wait | About 3–4 years; under 3 for Shorter Waiting Time flats | Usually a few months |
| Income ceiling | S$16,000 (families) | None for Standard or older flats, unless you take a grant or HDB loan |
| Main grants | EHG up to S$120,000 | EHG, CPF Housing Grant and Proximity Housing Grant, up to S$230,000 in total |
| Choice | Ballot; you may miss your town | Pick the exact block, floor and view |
| Who can buy | Citizen plus citizen or PR | PR-only households too, after 3 years as PRs (Standard and older flats) |
Source: HDB, gov.sg. Rules as at November 2026.
Grants matter a lot for resale buyers. A first-timer family buying a resale 4-room flat to live with their parents could get the CPF Housing Grant of S$80,000 (S$50,000 for 5-room and bigger). Add the Proximity Housing Grant of S$30,000, plus up to S$120,000 in Enhanced CPF Housing Grant (EHG).
The EHG is income-tested, with a ceiling of S$9,000 a month. That ceiling stayed put when the BTO ceiling rose. A household earning S$12,000 can still buy a BTO flat or use the resale grants, but gets no EHG.
Grant (S$)
Source: HDB, grants for couples and families (October 2026); HDB, Proximity Housing Grant. The EHG is income-tested, with a ceiling of S$9,000 a month. Together the three grants reach up to S$230,000.
Resale is often the only realistic choice if you need a home soon or are a PR household. The same holds if you earn over S$16,000, or want a block near your parents. If you can wait and want the lowest price, BTO wins.
Our guide on when to apply for a BTO flat covers the timing, and a first-hand account of buying a BTO flat covers the process.
3. Which HDB flat type? Sizes and prices
HDB’s flat types differ mainly in the number of bedrooms. Layouts and floor areas vary by project, so check the floor plan of each flat.
| Flat type | Bedrooms | Who it suits | Median floor area | Median resale price |
|---|---|---|---|---|
| 2-room Flexi | 1 | Singles 35+, couples, seniors | 47 sqm (506 sq ft) | S$375,000 |
| 3-room | 2 | Small families, budget buyers | 67 sqm (721 sq ft) | S$440,000 |
| 4-room | 3 | Most families | 93 sqm (1,001 sq ft) | S$630,000 |
| 5-room | 3, plus a study area | Larger families, home offices | 116 sqm (1,249 sq ft) | S$745,000 |
| 3Gen | 4 (two with attached bathrooms) | Couples living with parents | — | — |
| Executive | 3 plus extra space; resale only | Buyers who want space | 146 sqm (1,572 sq ft) | S$915,500 |
Source: HDB. Floor areas are medians of resale flats from November 2025 to October 2026; prices are medians for the 12 months to October 2026.
A 4-room flat gives you about 1,000 sq ft, and a 5-room flat adds about 250 sq ft. Newer 5-room flats are a little smaller: those completed from 2010 had a median of 113 sqm, against 122 sqm for flats from before 1990.
- 3-room
- 4-room
- 5-room
- Executive
Latest: 3-room S$438,444 (Nov 2026), down 2.6% on Nov 2025; 4-room S$635,000 (Nov 2026), up 1.5% on Nov 2025; 5-room S$738,888 (Nov 2026), down 1.2% on Nov 2025; Exec S$889,000 (Nov 2026), down 4.6% on Nov 2025.
Medians are by registration month. A month appears once it is complete.
Table view
| Period | 3-room | 4-room | 5-room | Executive |
|---|---|---|---|---|
| Nov 2026 | S$438,444 | S$635,000 | S$738,888 | S$889,000 |
| Oct 2026 | S$430,000 | S$629,444 | S$760,000 | S$913,888 |
| Sep 2026 | S$430,000 | S$628,000 | S$760,000 | S$938,000 |
| Aug 2026 | S$440,000 | S$628,000 | S$740,000 | S$925,444 |
| Jul 2026 | S$431,278 | S$625,000 | S$730,000 | S$900,000 |
| Jun 2026 | S$445,000 | S$620,944 | S$738,000 | S$910,888 |
| May 2026 | S$436,900 | S$630,000 | S$740,000 | S$928,888 |
| Apr 2026 | S$443,000 | S$638,000 | S$735,000 | S$925,000 |
| Mar 2026 | S$445,888 | S$633,500 | S$750,000 | S$910,000 |
| Feb 2026 | S$435,000 | S$620,000 | S$750,000 | S$900,000 |
| Jan 2026 | S$450,000 | S$625,000 | S$745,000 | S$890,000 |
| Dec 2025 | S$440,000 | S$631,000 | S$738,000 | S$935,000 |
| Nov 2025 | S$450,000 | S$625,888 | S$748,000 | S$931,500 |
| Oct 2025 | S$445,000 | S$625,000 | S$740,000 | S$870,000 |
| Sep 2025 | S$438,944 | S$640,000 | S$749,444 | S$915,000 |
| Aug 2025 | S$448,000 | S$627,000 | S$735,000 | S$880,000 |
| Jul 2025 | S$460,000 | S$625,000 | S$740,000 | S$905,000 |
| Jun 2025 | S$450,000 | S$635,000 | S$728,888 | S$888,000 |
| May 2025 | S$450,000 | S$630,000 | S$738,888 | S$950,444 |
| Apr 2025 | S$445,000 | S$630,888 | S$741,500 | S$920,000 |
| Mar 2025 | S$440,000 | S$628,000 | S$735,000 | S$881,400 |
| Feb 2025 | S$441,500 | S$623,800 | S$728,000 | S$900,000 |
| Jan 2025 | S$438,888 | S$618,000 | S$715,888 | S$869,444 |
| Dec 2024 | S$434,444 | S$620,000 | S$720,000 | S$874,944 |
| Nov 2024 | S$430,000 | S$603,500 | S$718,000 | S$855,000 |
| Oct 2024 | S$426,000 | S$618,944 | S$705,000 | S$897,500 |
| Sep 2024 | S$425,000 | S$610,000 | S$705,000 | S$864,044 |
| Aug 2024 | S$420,000 | S$595,000 | S$690,000 | S$869,500 |
| Jul 2024 | S$420,000 | S$600,000 | S$690,000 | S$860,000 |
| Jun 2024 | S$418,000 | S$590,000 | S$695,000 | S$868,000 |
| May 2024 | S$405,000 | S$580,000 | S$684,000 | S$840,000 |
| Apr 2024 | S$410,000 | S$569,444 | S$669,444 | S$858,000 |
| Mar 2024 | S$405,000 | S$570,000 | S$668,888 | S$830,000 |
| Feb 2024 | S$405,000 | S$570,000 | S$650,000 | S$825,000 |
| Jan 2024 | S$400,000 | S$565,000 | S$680,000 | S$840,000 |
| Dec 2023 | S$395,000 | S$564,000 | S$660,000 | S$796,500 |
| Nov 2023 | S$400,000 | S$560,000 | S$655,000 | S$820,888 |
| Oct 2023 | S$390,000 | S$558,000 | S$649,444 | S$840,000 |
| Sep 2023 | S$390,000 | S$555,000 | S$650,000 | S$820,000 |
| Aug 2023 | S$390,000 | S$559,444 | S$650,000 | S$829,000 |
| Jul 2023 | S$395,000 | S$550,000 | S$655,000 | S$822,500 |
| Jun 2023 | S$392,000 | S$545,000 | S$650,000 | S$808,000 |
| May 2023 | S$384,500 | S$550,000 | S$651,000 | S$822,500 |
| Apr 2023 | S$388,888 | S$540,000 | S$651,000 | S$819,000 |
| Mar 2023 | S$390,000 | S$544,400 | S$640,000 | S$809,000 |
| Feb 2023 | S$382,944 | S$535,000 | S$635,000 | S$797,500 |
| Jan 2023 | S$390,000 | S$530,000 | S$640,000 | S$780,000 |
| Dec 2022 | S$380,000 | S$530,000 | S$625,000 | S$789,000 |
| Nov 2022 | S$385,000 | S$530,000 | S$635,000 | S$779,000 |
| Oct 2022 | S$380,000 | S$530,000 | S$636,000 | S$758,000 |
| Sep 2022 | S$370,000 | S$523,888 | S$633,000 | S$798,000 |
| Aug 2022 | S$370,000 | S$515,000 | S$628,000 | S$780,000 |
| Jul 2022 | S$369,000 | S$520,000 | S$630,750 | S$780,000 |
| Jun 2022 | S$369,500 | S$510,000 | S$615,000 | S$755,000 |
| May 2022 | S$370,000 | S$510,044 | S$608,000 | S$745,000 |
| Apr 2022 | S$360,000 | S$503,000 | S$610,000 | S$740,000 |
| Mar 2022 | S$360,000 | S$500,000 | S$600,000 | S$718,444 |
| Feb 2022 | S$350,000 | S$485,000 | S$608,000 | S$777,000 |
| Jan 2022 | S$360,000 | S$490,000 | S$588,444 | S$720,000 |
| Dec 2021 | S$350,000 | S$490,000 | S$588,000 | S$720,000 |
| Nov 2021 | S$350,000 | S$488,000 | S$590,000 | S$710,000 |
| Oct 2021 | S$345,000 | S$488,000 | S$580,000 | S$700,000 |
| Sep 2021 | S$340,000 | S$480,000 | S$575,000 | S$718,000 |
| Aug 2021 | S$338,000 | S$475,500 | S$570,000 | S$690,000 |
| Jul 2021 | S$330,000 | S$468,000 | S$575,000 | S$676,500 |
| Jun 2021 | S$328,500 | S$470,000 | S$568,000 | S$685,000 |
| May 2021 | S$335,000 | S$470,000 | S$560,000 | S$660,000 |
| Apr 2021 | S$325,000 | S$460,000 | S$555,000 | S$690,000 |
| Mar 2021 | S$320,000 | S$455,000 | S$548,000 | S$674,000 |
| Feb 2021 | S$320,000 | S$448,000 | S$555,000 | S$660,444 |
| Jan 2021 | S$317,000 | S$448,000 | S$535,000 | S$655,000 |
| Dec 2020 | S$305,000 | S$440,000 | S$530,000 | S$650,000 |
| Nov 2020 | S$310,000 | S$430,000 | S$525,000 | S$630,000 |
| Oct 2020 | S$308,444 | S$436,000 | S$515,000 | S$632,500 |
| Sep 2020 | S$298,500 | S$420,000 | S$510,000 | S$620,000 |
| Aug 2020 | S$293,000 | S$418,000 | S$490,000 | S$615,000 |
| Jul 2020 | S$285,000 | S$410,000 | S$508,000 | S$580,000 |
| Jun 2020 | S$285,000 | S$409,000 | S$488,000 | S$581,500 |
| May 2020 | S$282,000 | S$422,000 | S$505,000 | S$575,000 |
| Apr 2020 | S$278,000 | S$410,000 | S$502,000 | S$587,500 |
| Mar 2020 | S$280,000 | S$410,000 | S$500,000 | S$612,000 |
| Feb 2020 | S$290,000 | S$400,000 | S$505,000 | S$606,500 |
| Jan 2020 | S$290,000 | S$395,000 | S$493,000 | S$590,000 |
| Dec 2019 | S$285,000 | S$405,000 | S$485,000 | S$590,000 |
| Nov 2019 | S$285,888 | S$405,000 | S$490,000 | S$612,000 |
| Oct 2019 | S$285,000 | S$400,000 | S$488,000 | S$602,888 |
| Sep 2019 | S$280,000 | S$397,000 | S$480,000 | S$605,500 |
| Aug 2019 | S$288,000 | S$400,000 | S$480,000 | S$571,900 |
| Jul 2019 | S$281,500 | S$400,000 | S$484,000 | S$597,500 |
| Jun 2019 | S$280,000 | S$400,000 | S$476,500 | S$585,000 |
| May 2019 | S$280,000 | S$395,000 | S$475,000 | S$593,500 |
| Apr 2019 | S$280,000 | S$398,500 | S$499,000 | S$585,000 |
| Mar 2019 | S$280,000 | S$400,000 | S$488,000 | S$600,888 |
| Feb 2019 | S$283,000 | S$393,888 | S$475,000 | S$600,000 |
| Jan 2019 | S$285,000 | S$395,000 | S$470,000 | S$600,000 |
| Dec 2018 | S$285,000 | S$395,000 | S$477,444 | S$600,000 |
| Nov 2018 | S$288,000 | S$395,000 | S$465,000 | S$620,000 |
| Oct 2018 | S$290,000 | S$396,000 | S$470,000 | S$606,500 |
| Sep 2018 | S$285,000 | S$400,000 | S$460,000 | S$618,000 |
| Aug 2018 | S$290,000 | S$400,000 | S$480,000 | S$630,000 |
| Jul 2018 | S$293,000 | S$405,000 | S$471,000 | S$615,000 |
| Jun 2018 | S$293,000 | S$405,000 | S$475,000 | S$590,000 |
| May 2018 | S$293,675 | S$400,000 | S$480,000 | S$628,000 |
| Apr 2018 | S$293,650 | S$405,000 | S$480,000 | S$610,000 |
| Mar 2018 | S$295,000 | S$410,000 | S$485,000 | S$585,000 |
| Feb 2018 | S$289,000 | S$400,000 | S$490,000 | S$605,000 |
| Jan 2018 | S$295,000 | S$410,000 | S$485,000 | S$628,000 |
| Dec 2017 | S$292,000 | S$405,000 | S$475,000 | S$603,500 |
| Nov 2017 | S$298,000 | S$407,000 | S$485,000 | S$605,000 |
| Oct 2017 | S$300,000 | S$400,000 | S$480,000 | S$590,000 |
| Sep 2017 | S$300,000 | S$410,000 | S$474,500 | S$611,500 |
| Aug 2017 | S$300,000 | S$414,000 | S$475,000 | S$620,000 |
| Jul 2017 | S$300,000 | S$400,004 | S$468,000 | S$605,000 |
| Jun 2017 | S$308,000 | S$408,000 | S$468,000 | S$610,000 |
| May 2017 | S$305,000 | S$408,000 | S$480,000 | S$587,500 |
| Apr 2017 | S$305,000 | S$400,000 | S$486,444 | S$592,000 |
| Mar 2017 | S$306,000 | S$418,000 | S$477,000 | S$600,000 |
| Feb 2017 | S$305,000 | S$408,000 | S$483,500 | S$587,000 |
| Jan 2017 | S$305,000 | S$410,000 | S$476,944 | S$600,000 |
Source: HDB. Data to Nov 2026.
The chart shows the median resale price of each flat type since 2017. All four rose from 2020, climbed fastest in 2021 and 2022, and flattened in 2025 and 2026.
Singles aged 35 and above can buy only 2-room Flexi flats from HDB. On resale they can buy most flat types except 3Gen, and only 2-room flats in Prime projects. 3Gen flats are for a couple living with at least one parent, and can only be resold to other multi-generation families.
Buy for the family you expect to have when your MOP ends. A 3-room flat that fits a couple can feel very small with two children, and you cannot sell for five or ten years.
4. Standard, Plus or Prime?
Every BTO project launched since October 2024 is classified. Older flats are “unclassified” and follow the Standard rules.
- Standard: 5-year MOP. You can rent out the whole flat after MOP with approval, and sell to any eligible buyer.
- Plus: in more desirable locations than Standard projects. 10-year MOP, no whole-flat rental, and a subsidy recovery of 6–8% of the resale price in launches so far.
- Prime: the most central locations, including older Prime Location Public Housing flats. 10-year MOP, no whole-flat rental, and a subsidy recovery of 9–14% so far.
In the November 2026 exercise, the two Bedok projects and Merpati Meadow in Geylang were Plus. Toa Payoh Hillside was the only Prime project. Sembawang, Tengah and Yishun were Standard.
The 10-year MOP and no-rental rule also apply when you buy a Plus or Prime flat on the resale market. You pay no subsidy recovery when you sell a flat you bought on resale. Your buyers must meet BTO eligibility rules and the S$16,000 income ceiling, and that smaller pool of buyers may hold back resale prices.
- Minimum occupation period
- 5 years
- Rent out whole flat
- After MOP, with approval
- Resale buyers
- Any eligible buyer
- Minimum occupation period
- 10 years
- Rent out whole flat
- Not allowed
- Subsidy recovery on resale
- 6% to 8% of resale price
- Minimum occupation period
- 10 years
- Rent out whole flat
- Not allowed
- Subsidy recovery on resale
- 9% to 14% of resale price
Source: HDB, Standard, Plus and Prime housing framework (October 2026). Subsidy recovery figures are those in launches so far. The 10-year MOP and rental rule also apply on resale.
The question to ask: will we still want to live here in ten years? If the answer is less than a clear yes, a Standard flat keeps your options open.
5. Location, lease and the people next door
Transport and daily life. A flat a short walk from an MRT station can save you a lot of commuting time every day, compared with one that needs a feeder bus. This is part of why central flats near MRT lines make up most million-dollar HDB resales.
Also check schools, hawker centres and clinics nearby, and see our guide to what makes a good location.
Location moves the price as much as size does. The table below shows every town’s resales in October 2026.
| # | Town | Resales | Median price, all flats | Year change, all flats | Median price, 4-room | Year change, 4-room |
|---|---|---|---|---|---|---|
| 1 | Tampines | 193 | S$750,000 | +8.7% | S$675,000 | +1.8% |
| 2 | Punggol | 146 | S$680,000 | 0.0% | S$671,944 | −4.0% |
| 3 | Woodlands | 143 | S$570,000 | −1.4% | S$528,000 | −4.0% |
| 4 | Sengkang | 140 | S$675,884 | +2.5% | S$639,444 | +2.9% |
| 5 | Bedok | 129 | S$630,000 | +28.6% | S$599,000 | +7.4% |
| 6 | Jurong West | 127 | S$575,000 | +4.9% | S$502,500 | −6.7% |
| 7 | Yishun | 120 | S$512,500 | −5.1% | S$520,000 | −8.8% |
| 8 | Toa Payoh | 110 | S$856,500 | +8.4% | S$1,038,888 | −0.1% |
| 9 | Bukit Batok | 105 | S$613,000 | −5.7% | S$568,000 | −13.0% |
| 10 | Hougang | 100 | S$675,000 | +9.8% | S$620,000 | 0.0% |
| 11 | Bukit Merah | 86 | S$901,000 | +11.2% | S$950,000 | +0.2% |
| 12 | Queenstown | 85 | S$880,000 | −3.1% | S$1,034,000 | +4.8% |
| 13 | Ang Mo Kio | 84 | S$494,444 | +3.4% | S$612,000 | +4.8% |
| 14 | Choa Chu Kang | 81 | S$572,000 | −2.7% | S$550,000 | −2.2% |
| 15 | Kallang/Whampoa | 78 | S$684,000 | −0.5% | S$825,000 | −11.3% |
| 16 | Sembawang | 72 | S$597,500 | −2.8% | S$566,500 | −5.6% |
| 17 | Bukit Panjang | 66 | S$621,000 | +6.6% | S$585,944 | −0.7% |
| 18 | Geylang | 55 | S$543,888 | −22.4% | S$701,900 | −8.7% |
| 19 | Bishan | 49 | S$930,000 | +6.3% | S$784,000 | +5.9% |
| 20 | Pasir Ris | 49 | S$750,000 | +5.0% | S$632,500* | −1.4%* |
| 21 | Clementi | 42 | S$565,500 | +1.1% | S$670,000 | −12.2% |
| 22 | Jurong East | 40 | S$565,444 | +7.4% | S$600,000* | +12.9%* |
| 23 | Serangoon | 38 | S$633,000 | −10.1% | S$649,944 | −5.8% |
| 24 | Central Area | 18 | S$620,000 | +3.0% | S$1,188,888* | −19.7%* |
| 25 | Marine Parade | 13 | S$490,000 | −12.5% | S$563,000* | −14.7%* |
| 26 | Bukit Timah | 4 | S$599,444* | – | S$592,584* | – |
| All HDB towns | 2,173 | S$650,000 | +4.8% | S$629,444 | +0.7% |
Source: HDB. Data to Oct 2026.
In October 2026 the median 4-room flat sold for more than S$1 million in Toa Payoh and Queenstown. In Woodlands and Jurong West it was about half that.
The same budget buys a 4-room flat in one town and a 5-room flat in another, so decide which matters more before you view. Each town’s prices and rents are on its town page.
Parents. Living with or within 4 km of your parents qualifies you for the Proximity Housing Grant on resale. It also gives you priority under the Family Care Scheme for new flats.
Lease. HDB flats have 99-year leases and return to the state at the end. CPF use is limited if the remaining lease does not cover the youngest buyer to age 95, and the EHG is pro-rated on the same test.
Example: a 40-year-old buying a flat with 60 years left is covered to age 100, so there is no cut. With 50 years left, the lease runs only to age 90, so CPF use and the EHG are reduced. Older flats are cheaper for a reason, so price in the lease as well as the size.
The ten highest resale prices of October 2026 show what buyers pay most for.
| # | Town | Block and street | Flat type | Storey | Area (sqm) | Area (sq ft) | Remaining lease | Price |
|---|---|---|---|---|---|---|---|---|
| 1 | Queenstown | Blk 96 Dawson Road | 5-room | 40–42 | 111 | 1,195 | 94 yrs | S$1,818,000 |
| 2 | Bishan | Blk 273A Bishan Street 24 | 5-room | 37–39 | 120 | 1,292 | 84 yrs | S$1,711,000 |
| 3 | Central Area | Blk 1A Cantonment Road | 5-room | 46–48 | 105 | 1,130 | 83 yrs 3 mths | S$1,710,000 |
| 4 | Bishan | Blk 273B Bishan Street 24 | 5-room | 31–33 | 120 | 1,292 | 83 yrs 11 mths | S$1,688,000 |
| 5 | Kallang/Whampoa | Blk 9 Boon Keng Road | 5-room | 34–36 | 117 | 1,259 | 83 yrs 4 mths | S$1,640,000 |
| 6 | Bishan | Blk 273A Bishan Street 24 | 5-room | 31–33 | 120 | 1,292 | 83 yrs 11 mths | S$1,588,000 |
| 7 | Central Area | Blk 1A Cantonment Road | 4-room | 28–30 | 95 | 1,023 | 83 yrs 4 mths | S$1,588,000 |
| 8 | Toa Payoh | Blk 138A Lorong 1a Toa Payoh | 5-room | 31–33 | 117 | 1,259 | 84 yrs 8 mths | S$1,588,000 |
| 9 | Queenstown | Blk 86 Dawson Road | 5-room | 25–27 | 104 | 1,119 | 88 yrs 11 mths | S$1,561,000 |
| 10 | Queenstown | Blk 23 Ghim Moh Link | 5-room | 37–39 | 113 | 1,216 | 85 yrs 7 mths | S$1,561,000 |
Source: HDB. Data to Oct 2026.
All ten flats had 83 years or more of lease left, and all were on the 25th floor or higher. All were in mature, central towns: Queenstown, Bishan, Central Area, Kallang/Whampoa and Toa Payoh.
A long lease, a high floor and a central address together set the top of the market. For the floor effect alone, see do higher floors cost more.
Ethnic Integration Policy and SPR quota. In resale, each block and neighbourhood has ethnic and PR limits. Non-Malaysian PR households can buy only if the block (8%) and neighbourhood (5%) are within the PR quota.
Check the quota for a flat before you fall in love with it. It also affects who you can sell to later.
What about ECs and DBSS flats?
An executive condo (EC) is a condo built by a private developer, sold with a subsidy to families. A family can buy a new EC on income of up to S$18,000 a month.
ECs on land tendered from 8 May 2026 carry a 10-year MOP. After 15 years they can be sold to any buyer. Our EC eligibility guide has the detail.
A DBSS flat is an HDB flat that a private developer designed, built and priced. The government suspended DBSS land sales in 2011, so these flats come only on the resale market.
A quick checklist
- Get your HFE letter to confirm your eligibility, loan and grants.
- Set a maximum price from your cash and CPF as well as the loan.
- Decide new or resale based on how soon you need the home and your income.
- Choose the flat type for your family five to ten years from now.
- If it is Plus or Prime, confirm you can commit for ten years.
- Check MRT access, schools, parents’ location and the remaining lease.
- For resale, check the EIP and PR quota, recent prices in the same block, and any cash over valuation you would have to pay.
Bottom line
There is no single best HDB flat. There is a best order for deciding. Start from what you can comfortably pay, then choose new or resale, then size, then the Standard, Plus or Prime trade-off, then the exact location.
Plan around three big rules: the 10-year MOP on Plus and Prime flats, the S$16,000 income ceiling, and resale grants of up to S$230,000 for first-timers. If you have already been balloted, our guide to choosing your BTO unit takes it from there.
Rules and rates as at 5 November 2026.
2 reader comments
Richard
Hi
Can you blog about the 99 year lease for HDB flats. Will banks continue to provide a loan for older flats. Is there a cut off point beyond which a bank will not provide a loan if a HDB flat has only X number of years lease left.
What are the resale prospects of a HDB flat with only 40 years of lease left?
Propwise.sg
Hi Richard, it depends on the bank, but my understanding that the limit for bank loans is now about 30 years of lease left. Of course, the fewer years you have on your lease, the less re-saleable (or the lower the price) you’ll be able to sell it for.